
You sign the sale papers. Relief kicks in for about five minutes. Then your accountant sends the draft tax position, and the capital gain looks big enough to punch a hole in your retirement plan.
I've seen this too many times. Owners spend years building a business, negotiate hard on price, and then treat the tax side like an admin task. That's backwards. A sale isn't finished when the contract is signed. It's finished when the after-tax cash is in your hands.
The good news is Australia has small business CGT concessions built for genuine small business owners. The bad news is they're technical, easy to misuse, and expensive to get wrong. If you need a broader primer on the sale side first, BizBuySell has a practical guide to capital gains tax for sellers. If you're also trying to work out timing, this overview on when you pay capital gains tax helps frame the lodgement side.
- The Million-Dollar Question After Selling Your Business
- First Hurdle Passing the Basic Eligibility Tests
- The Four Concessions A Tool for Every Situation
- Strategy Over Checklist The Critical Order of Application
- A Worked Example From Cafe Sale to Tax Saved
Table of Contents
- The Million-Dollar Question After Selling Your Business
- First Hurdle Passing the Basic Eligibility Tests
- The Four Concessions A Tool for Every Situation
- Strategy Over Checklist The Critical Order of Application
- A Worked Example From Cafe Sale to Tax Saved
- Paper Trails and Pitfalls Your Compliance Checklist
- Final Verdict When to Stop DIY and Call a Specialist
The Million-Dollar Question After Selling Your Business
You sell the business. The money hits the account. Then your accountant tells you a big slice of that gain may be taxable because nobody planned the concession pathway before the contract was signed.
That is the moment small business owners realise the sale price was only half the job.
The question is simple. How much of the gain do you get to keep, and how much do you hand over because the concessions were treated like a year-end checklist instead of a sale strategy?
Small business CGT concessions can reduce, ignore, or defer part of the gain on the sale of an active business asset. There are four of them, and the order you apply them can change the outcome dramatically. Get the sequence right and you can strip out a large tax bill. Get it wrong and you can burn through money that should have stayed in your retirement fund or gone back into the next venture.
Small business CGT concessions are a planning regime, not a box-ticking exercise. Treat the order casually and you will pay for it.
The expensive mistake is waiting until tax return time to ask the CGT question. By then, the asset mix is set, the paperwork is done, and the wrong entity may already be locked into the gain. I see owners focus on the headline sale price and ignore how goodwill, business premises, shares, units, or trust interests are being sold. That is how avoidable tax bills happen.
If you need a plain-English refresher on when capital gains tax applies to a business sale, read that first. Then come back to the concession strategy, because the tax does not sort itself out after settlement.
A decent guide to capital gains tax for sellers can help you frame the issue, but significant savings come from applying the rules in the right order and backing every step with evidence.
This sale may fund retirement, clear debt, or bankroll the next chapter. A sloppy approach is expensive.
First Hurdle Passing the Basic Eligibility Tests
Settlement is done. The price looks good. Then your accountant asks a question that should have been dealt with months earlier. Did the seller qualify for the small business CGT concessions?
That is the first trap.
The concessions only help if you clear the basic eligibility tests first. If you miss them, the later strategy means nothing. Worse, many owners test the wrong entity, the wrong asset, or the wrong group, then build an entire tax position on bad assumptions. That mistake gets expensive fast.

Start with the seller, not the concession
Do not start by asking which concession sounds best. Start by asking who made the gain, what was sold, and whether that asset qualifies at all.
The basic tests boil down to three questions.
-
Does the seller satisfy an entry test?
Usually that means the small business entity route based on aggregated turnover, or the maximum net asset value route based on the group's net assets. -
Was the asset an active asset?
Owning an asset near the business is not enough. It must have been used in the business in the way the law requires. -
If shares or trust interests were sold, do the extra conditions stack up?
This is where many DIY claims fall apart. Shares and units bring extra rules, and sloppy assumptions here can wipe out the concession outcome.
The ATO's eligibility overview for small business CGT concessions is the right starting point for the legal framework. Then you need to apply it to your structure, your sale documents, and your evidence.
The costly mistake is testing the trading entity in isolation
Owners often look at the business they run day to day and stop there. That is not how these rules work.
Turnover and net asset tests can pull in connected entities and affiliates. A family trust holding the premises, a spouse's company, a second entity carrying staff or equipment, or a holding company sitting over the top can all change the result. If you ignore those links, your numbers are wrong before the calculation even starts.
Entity structure matters here more than people think. If you need a refresher, read this guide on business legal structures in Australia and how they affect tax treatment.
A common failure looks like this. The trading company appears small enough on its own. The owner assumes the turnover test is met. But once related entities are grouped in, the threshold is blown. Or the turnover test fails, yet nobody checks the net asset route, even though that second gate might still save the claim. Good advice is not about memorising the tests. It is about applying them in the right order and checking every available path before giving up.
Active asset is where loose language causes real damage
“Business asset” is not the same as “active asset.”
That distinction matters.
Goodwill usually gets the attention because it is obviously tied to the business. Other assets are less straightforward. Business premises, shares, units, loan accounts, and assets used partly for business and partly for investment need closer analysis. If the asset does not meet the active asset rules for the required period, the concession claim can collapse even if the business itself is well under the thresholds.
I see this mistake with properties all the time. Owners say, “It was part of the business.” That is not evidence. You need records that show how the asset was used, by which entity, and for how long.
Check the file before you check the tax saving
Before anyone models the tax outcome, get the file in order:
- Entity map: who owns each entity, who controls it, and which entity sold the asset
- Group analysis: connected entities, affiliates, and assets held outside the trading entity
- Asset analysis: what exactly was sold and why it qualifies as an active asset
- Financial records: accounts, valuations, and working papers that support the entry test used
- Sale documents: contracts that match the actual transaction, not a vague commercial summary
This is risk management, not paperwork for its own sake. If the eligibility position is weak, every later concession is exposed. And if you test eligibility early, you still have time to fix documents, challenge assumptions, and choose the right path instead of cleaning up a mess after settlement.
The Four Concessions A Tool for Every Situation
Once you're inside the rules, you've got four tools. Not four magic tricks. Four distinct tools with different jobs.
Bad advice on this subject proves expensive. Too many guides throw the concessions into one pile and make them sound interchangeable. They're not. One can wipe out the gain. One cuts it. One can shelter part of what remains. One pushes the problem down the road. If you don't know the purpose of each, you'll choose badly.
What each concession is really for
The 15-year exemption is the premium outcome. Lawpath's summary notes that it can disregard the entire capital gain if the asset was owned for at least 15 years and the owner is over 55 and retiring, with the retirement exemption carrying a lifetime limit of $500,000 per individual. It also notes that for companies, a CGT concession stakeholder must generally hold at least 20% to qualify (Lawpath guide).
That first concession is the one owners dream about, and for good reason. If you qualify, the gain can disappear for tax purposes. But this is also where people get sloppy. They hear “retiring”, hear “owned it for ages”, and assume they're home. They aren't home until every condition is checked.
The 50% active asset reduction is more mechanical. It's often the workhorse concession in ordinary business sales. It doesn't have the glamour of the 15-year exemption, but it can still be the move that changes a painful gain into a manageable one.
Then there's the retirement exemption. Despite the name, don't reduce it to a retirement story in your head. It's a tax concession with rules, choices, and consequences. It can be powerful because it lets you disregard part of the remaining gain, but it's not something to apply casually just because it sounds beneficial.
The rollover relief is different again. It's about deferral. Sometimes that's exactly what a business owner needs. Sometimes it just delays a problem while creating fresh compliance pressure.
The best concession is the one that fits your facts, not the one with the best headline.
Comparing the four small business CGT concessions
| Concession Name | Primary Benefit | Key Requirement |
|---|---|---|
| 15-year exemption | Can disregard the entire capital gain | Asset owned for at least 15 years, with qualifying retirement or incapacity conditions |
| 50% active asset reduction | Reduces the gain by half | Asset must qualify and the basic conditions must be satisfied |
| Retirement exemption | Can disregard part of the remaining gain | Lifetime limit of $500,000 per individual |
| Rollover relief | Defers the gain | Replacement planning and ongoing compliance need to be managed carefully |
A few blunt calls from practice:
- Best for clean exits: The 15-year exemption is the strongest outcome if you qualify.
- Best for ordinary sales: The active asset reduction often does the heavy lifting where the 15-year exemption isn't available.
- Best when flexibility matters: The retirement exemption can finish the job on a reduced gain.
- Best when you're still moving pieces around: Rollover relief suits owners changing assets, not owners chasing a simple final outcome.
If you want a broader view of where these rules sit within the tax system, this explainer on capital gains tax exemptions in Australia gives useful context.
Why this matters: picking the right concession, or combination, can radically change the after-tax result from the same sale.
Strategy Over Checklist The Critical Order of Application
A business owner sells, hears the words "small business CGT concessions," and assumes it is a menu. Pick one. Maybe stack another. Job done. That lazy approach is how people overpay tax and burn through concessions they did not need to use.
The core issue is order. These rules work in a set sequence, and the sequence changes the dollars. Treat it like a checklist and you miss the strategy. Treat it like a calculation with consequences and you keep more of the sale proceeds.

The sequence drives the outcome
As noted earlier, the order is fixed. You deal with capital losses first. Then you apply the general CGT discount if it is available. Then comes the 50% active asset reduction. After that, you decide whether the retirement exemption or rollover relief should deal with what is left.
That order is not a technical footnote. It decides how much gain survives to each later step. If you change the order on paper, you change the tax result, and usually not in your favour.
Read the process the way an accountant does:
- Start with the capital gain: Get the raw number right before touching any concession.
- Apply capital losses first: Old or current year capital losses reduce the gain before anything else.
- Apply the general CGT discount if eligible: If the asset and taxpayer qualify, reduce the gain here.
- Apply the 50% active asset reduction next: This often cuts the remaining gain harder than owners expect.
- Use the retirement exemption or rollover last: These are end-stage choices, not opening moves.
If you want a broader practical guide to reducing capital gains tax on a business sale, read that separately. Then come back to the sequencing issue, because the expensive mistakes happen there.
The costly mistake. Using the retirement exemption too early
Plenty of business owners fixate on the retirement exemption because it sounds like the biggest prize. Wrong instinct.
If the active asset reduction is available, you first reduce the gain through the required sequence, then decide how much of the retirement exemption you need. That matters because the retirement exemption has a lifetime cap. Waste it on a gain that could have been reduced earlier and you have permanently lost room that may matter later.
The right question is simple: what is the smallest taxable gain left after applying the rules in the correct order?
That is the strategy.
Risk management matters just as much as tax saved
Rollover relief is another trap. Owners often grab it because deferring tax feels attractive. Sometimes it is. Sometimes it just pushes a problem into the future and adds compliance risk if the replacement asset rules are not handled properly.
Use rollover relief when it supports a real commercial plan. Do not use it as a reflex. Deferring tax without a clear replacement strategy is how businesses create future mess, future amendments, and future adviser fees.
The bottom line is blunt. The concessions are not a shopping list. They are a sequence of tools, and the order decides whether you preserve flexibility, minimise tax, and avoid wasting limited relief. Getting that order wrong is expensive.
A Worked Example From Cafe Sale to Tax Saved
Let's make this concrete. Sarah owns a café she's run for years. She sells the business asset and ends up with a capital gain. No jargon. No hand waving. Just the mechanics.

Sarah's sale in plain English
Sarah sells for $1.2 million and her cost base is $400,000. That leaves a capital gain of $800,000.
Now the important part. We don't jump straight to an exemption and hope for the best. We test whether she's in the small business CGT concessions regime, then we follow the order of application. If you're unsure how sale price and asset value get assessed in the first place, this primer on the business valuation formula is worth a look.
For this example, assume Sarah passes the basic conditions and the asset qualifies. She has owned and operated the café for 12 years, so the 15-year exemption is not in play.
Sarah's outcome doesn't depend on finding a loophole. It depends on applying ordinary rules properly.
Applying the sequence step by step
Start with the gain of $800,000.
Then apply the general CGT discount. That takes the gain down to $400,000.
After that, apply the 50% active asset reduction. That takes the remaining gain down to $200,000.
At that point, Sarah can use the retirement exemption to disregard the final $200,000. Because the retirement exemption has a lifetime limit of $500,000 per individual, that amount sits within the limit described earlier.
#SmallBusinessTax #CGT #TaxConcessions #AustralianBusiness #TaxPlanning #BusinessExit
Here's the worked flow in table form:
| Step | Calculation | Remaining gain |
|---|---|---|
| Starting position | Capital gain | $800,000 |
| General CGT discount | Reduce by 50% | $400,000 |
| 50% active asset reduction | Reduce by 50% | $200,000 |
| Retirement exemption | Disregard remaining amount | $0 |
That's the difference between reading about concessions and using them properly. Same sale. Same facts. Very different after-tax result.
A short explainer can help if you want to hear another walkthrough before talking to your adviser:
One warning. This example is useful because it's simple. Real sales often aren't. The minute you add multiple entities, property held outside the trading business, trust distributions, or sale proceeds split across different asset classes, the “easy” calculation stops being easy.
Why this matters: once you see the sequence work on a real number, it becomes obvious why sloppy ordering is so expensive.
Paper Trails and Pitfalls Your Compliance Checklist
Claiming a concession is one thing. Defending it is another.
The ATO won't accept “my accountant said it should be fine” as evidence. If your file is thin, inconsistent, or built after the fact, you've handed them a problem to investigate. A good claim needs records that line up with the law, the contract, and the tax return.
What records actually matter
Keep the documents that prove the story from start to finish:
- Acquisition records: Contracts, settlement statements, and anything showing when and how the asset was acquired.
- Sale records: The sale agreement, adjustments, and supporting schedules that show what was sold.
- Business use evidence: Lease arrangements, operating records, financials, and other material supporting active use in the business.
- Entity documents: Company registers, trust deeds, unit holdings, and anything else proving who owned the asset and who controlled the entity.
- Valuation support: If a value question affects eligibility or allocation, get evidence that would survive scrutiny.
- Tax working papers: Keep the CGT calculation, assumptions, elections, and adviser notes together in one file.
Practical rule: If someone new picked up your file in two years' time, they should be able to reconstruct the claim without guessing.
Lodgement also matters. The concession doesn't live in your head or in your email chain. It has to be reflected correctly in the return and supporting schedules. If your records and your lodged position don't match, you've created your own audit trigger.
Common Pitfall last-minute changes create ugly problems
I see this often. Owners change structure, move assets, tidy up ownership, or alter business use near the sale date because someone told them it would “make things cleaner”. Sometimes it does the opposite.
A rushed restructure can muddy the ownership history. A late shift in asset use can weaken the active asset position. A vague allocation in the sale contract can create a valuation dispute you didn't need. These problems don't always show up on settlement day. They show up when the return is lodged and someone tries to justify the claim line by line.
Use this quick pre-lodgement checklist:
- Check ownership history: Make sure legal ownership and tax records align.
- Check active use evidence: Don't rely on memory. Pull documents.
- Check group relationships: Review related entities before signing off on eligibility assumptions.
- Check calculation order: The maths must follow the required sequence.
- Check elections and records: If a concession requires a formal choice or internal record, deal with it properly and on time.
Why this matters: a claim without documents is just a story, and stories don't survive review.
Final Verdict When to Stop DIY and Call a Specialist
Here's the blunt view. If your sale is simple, your structure is simple, and the asset history is clean, a competent adviser can usually map the path without drama. But many “small” businesses aren't simple at all. They're family groups, related entities, mixed-use assets, old trusts, stale company registers, and records spread across ten folders and three software systems.
That's when DIY stops being brave and starts being reckless.
Red flag checklist
Call a specialist if any of these apply:
- You operate through a company or trust: The rules become more technical, especially around ownership interests and stakeholder requirements.
- You have related entities or family group assets: Eligibility testing gets harder fast when control and ownership sit across multiple entities.
- The sale includes more than one asset: Allocation issues can distort the CGT result if handled badly.
- You're relying on the retirement exemption: This is not the place for rough calculations or assumptions.
- You want rollover relief: Deferral brings future compliance with it. If you don't manage that properly, today's tax problem becomes tomorrow's tax problem.
- Your records are incomplete: Missing evidence turns even a good technical position into a risky claim.
- You're deciding structure after signing heads of agreement: Late planning is better than none, but it's still late.
The blunt recommendation
If you tick even one of those boxes, stop trying to solve the whole issue from blog posts and scattered notes.
Get a proper review before the return is lodged. Better yet, get advice before the contract is locked in. The biggest tax savings usually come from decisions made while the transaction is still flexible. Once the deal is done, many options are gone and all that's left is damage control.
Why this matters: the cost of expert advice is usually tiny compared with the cost of getting a major CGT claim wrong.
CGT is not a separate tax — a capital gain is included in your assessable income for the year a CGT event occurs. It applies when you dispose of a CGT asset including shares, investment properties, business assets, and cryptocurrency. Your primary residence is generally exempt, though partial exemptions apply in specific circumstances.
The capital gain is capital proceeds (sale price) minus the cost base. The cost base includes purchase price, stamp duty, legal fees, and capital improvement costs. If the asset was held for more than 12 months, apply the 50% CGT discount to reduce the gain before adding it to taxable income. Keep all acquisition records from the purchase date.
Australian resident individuals and trusts that have held a CGT asset for more than 12 months can reduce their capital gain by 50% before inclusion in assessable income. Superannuation funds receive a one-third discount. Companies do not qualify. The holding period begins on the purchase date and ends on the disposal contract date.
Shares are CGT assets. When you sell shares, the gain or loss is proceeds less cost base (purchase price plus brokerage). Gains on shares held more than 12 months qualify for the 50% discount. Capital losses can only offset capital gains — they cannot reduce other income. Carry forward unused losses to offset future gains.
The main residence exemption can entirely or partially exempt the gain from selling your home. Full exemption applies if the property was your main residence throughout the ownership period, was never used to produce income, and sits on land of two hectares or less. Partial exemption applies where it was rented or used for business during part of the ownership period.
If you're selling a business asset, dealing with overdue returns, or trying to work out whether the small business CGT concessions apply to your situation, Australia Wide Tax Solutions can help you get the numbers right before an avoidable mistake becomes an expensive one. Their team works with individuals and business owners across Australia on capital gains tax, business accounting, BAS, late lodgements, and practical tax planning, with clear advice that focuses on the after-tax result.
It's late June. You've got a BAS due, the bank feed is full of half-labelled transactions, and a box of curled receipts is sitting under the desk like a tax problem you can ignore by not looking at it. You can't. In Australia, small businesses claim over $50 billion in deductions annually, and the ATO notes average refunds of $8,700 for compliant small businesses in 2023 according to ATO-based guidance.
Most business owners don't miss deductions because they're lazy. They miss them because they treat expense claims like a shopping list instead of a system. That's why they either underclaim out of fear or overclaim and walk straight into avoidable trouble. If you want to know how to claim business expenses properly, start with records, apportionment, and timing. The list of deductions comes after that.
- That Shoebox Full of Receipts Is Costing You Money
- The ATOs Three Golden Rules for Expense Claims
- Identifying Your Most Common Business Deductions
- Substantiation: The Art of Proving Your Claims
- Putting It Together: Apportionment, GST, and Your BAS
Table of Contents
- That Shoebox Full of Receipts Is Costing You Money
- The ATOs Three Golden Rules for Expense Claims
- Identifying Your Most Common Business Deductions
- Substantiation The Art of Proving Your Claims
- Putting It Together Apportionment, GST, and Your BAS
- Claiming Major Purchases Depreciation and Instant Write-Offs
- Your Next Steps An Error-Free Claims Checklist
That Shoebox Full of Receipts Is Costing You Money
A sole trader plumber buys materials from three suppliers, fuel from two servos, software on a monthly subscription, and the odd tool on the way to a job. By tax time, none of that feels organised. Some receipts are faded. Others are missing. The bank statement shows money went out, but not always what it was for.

That mess costs money in two directions. First, you miss legitimate deductions because you can't identify or prove them. Second, you waste hours reconstructing basic bookkeeping that should've been captured when the expense happened. If you're still typing receipt details by hand, stop. Tools for automated receipt processing via OkraPDF can pull structured data out of receipts, which makes categorising and retaining records far less painful.
A messy file is a tax problem
The ATO doesn't care that you were busy. It cares whether the expense was business-related, whether any private use has been excluded, and whether you can prove the claim. A receipt system doesn't need to be fancy, but it does need to be consistent.
Three setups usually work in practice:
- Simple operator setup: business bank account, one card for business purchases, receipt photos saved straight away.
- Software setup: Xero or MYOB with bank feeds and supplier rules.
- Hybrid setup: spreadsheet plus cloud folder, if volume is low and you're disciplined.
A shoebox is not a record-keeping system. It's delayed admin with interest attached.
If your current process relies on memory, rebuild it before the next quarter. A practical starting point is this guide to ways of record keeping for tax and business use. Why this matters: the businesses that claim cleanly aren't guessing at year end. They've made the claim easy to prove months earlier.
The ATOs Three Golden Rules for Expense Claims
You don't start with “Can I claim it?” You start with the three tests the ATO applies. If the claim fails one of them, the category doesn't matter.

ATO statistics show that of the $22.4 billion in work-related expenses claimed, adjustments are most common when one of the three golden rules is broken, according to this ATO-based summary. That same framework applies to business claims. The rule set is simple. Applying it properly isn't.
Rule one means a real connection to income
The expense must be incurred in earning your assessable income. Rent for your shop fits. Advertising fits. Accounting software usually fits. School shoes for your child don't become deductible because you answered work emails while buying them.
The problem isn't the obvious stuff. It's the grey-area spending that owners try to force into a business label after the fact. If the purpose is mixed, only the business portion is claimable.
Rule two means private use must be carved out
Many otherwise valid claims fail at this stage. Your mobile phone can be partly deductible. Your ute can be partly deductible. Home internet can be partly deductible. None of that means the full amount is fair game.
Common Pitfall
- Branded car myth: Putting your logo on the side of a car doesn't turn private travel into business use.
- Phone bill shortcut: Using your personal phone for client calls doesn't make the whole monthly plan deductible.
- Home expense overreach: Working from the kitchen table doesn't justify claiming every household cost.
Practical rule: If you can't explain how you worked out the business percentage, the claim is weak.
The legal backbone for this sits in the ordinary deductibility rules under tax law, but the practical version is easier to remember. Business use only. Private use excluded. Proof kept. If you need a plain-English companion piece, this article on what is a tax deductible expense is useful.
Rule three means records, not intentions
Wanting to claim an expense isn't evidence. A bank transaction alone often isn't enough because it may not show what was purchased, from whom, or why. The ATO wants records that tie the payment to the business purpose.
That's why rushed claims assembled from memory are risky. A clean claim is built from documents created at the time of purchase, not from stories built months later. Why this matters: once you understand the rules, you stop arguing with the tax law and start structuring your records to fit it.
Identifying Your Most Common Business Deductions
I see the same problem every year. A business owner has spent money that should be deductible, but the claim falls apart because the expense was coded badly, mixed with private spending, or treated as an immediate deduction when it should have been handled as a capital item.
The useful question is not just what can you claim. It is what kind of cost it is, when the deduction is available, and how you prove the business portion if the expense is mixed-use.
A practical way to sort deductions is by function. Running costs sit in one group. Asset purchases sit in another. Property expenses need separate attention because repairs, improvements, borrowing costs, and holding costs do not all get the same treatment. If you want a broader self-employed overview, this guide to claimable business expenses for sole traders is a useful companion.
Operating costs you can usually claim
For sole traders and SMEs, the regular deductions usually come from ordinary operating costs. These are the recurring expenses that keep the business trading.
| Expense Type | Example | Deductibility Status |
|---|---|---|
| Office supplies | Printer paper, stationery, postage | Generally deductible if used for business |
| Advertising | Online ads, flyers, website hosting | Generally deductible if tied to business activity |
| Professional fees | Tax agent, bookkeeping, legal advice related to the business | Usually deductible |
| Vehicle costs | Fuel, servicing, registration | Claim only the business portion |
| Software | Xero, MYOB, job management platforms, design tools | Usually deductible if used for business |
| Insurance | Public liability, business contents, professional indemnity | Usually deductible |
| Rent and utilities | Commercial premises rent, electricity for business site | Usually deductible |
| Home office costs | Running expenses for business use at home | Apportioned claim only |
| Rental property expenses | Council rates, agent fees, eligible repairs | Depends on the nature of the expense and use |
That table is the easy part. The actual work is in the grey areas.
A builder using a ute for site visits, school drop-off, and weekend trips cannot claim the lot. A consultant working from home cannot throw the full internet bill into the tax return. A café owner paying for accounting software with a package that also covers a separate side project needs to split the cost properly. Those are the claims that get adjusted because the category might be right, but the percentage is wrong.
Different businesses also attract different scrutiny. Trades usually rack up tools, protective equipment, vehicle costs, insurances, and contractor payments. Consultants often claim software, phone, home office running costs, industry subscriptions, and training that relates to their current income-earning work. Retailers need clean treatment of merchant fees, POS systems, freight, packaging, and stock-related spending. For more Australian examples by category, see this guide to small business tax deductions in Australia.
Property investors get caught on repairs versus improvements
Property claims are where poor classification gets expensive.
A repair generally fixes wear and tear and puts something back into working order. An improvement gives you something better than what was there before, changes the character of the asset, or forms part of a larger upgrade. That difference affects whether you claim it now, over time, or as part of the property's cost base.
A leaking tap replaced with a similar tap will often be a repair. Replacing an entire kitchen with better finishes, extra cabinetry, and new appliances is usually not a repair just because the old kitchen was tired. I spend a lot of time correcting rental schedules where owners have bundled new assets, structural work, and genuine repairs into one line called "maintenance". That shortcut creates problems fast.
The safest approach is to separate property spending as you go. Keep invoices detailed. Note what was done. If one bill includes both repair work and improvement work, split it before year-end while the facts are still clear.
Substantiation: The Art of Proving Your Claims
An expense without proof is just a claim waiting to be cut back. The ATO compliance position is blunt. Claims are disallowed in 68% of reviews due to a lack of substantiation, particularly missing logbooks or diaries, and records must be kept for five years according to ATO compliance data.

What counts as proof
A proper record should show the supplier, date, amount, and what you bought. For some lower-value items, a diary record supported by a bank transaction may help. For larger or more scrutinised claims, get the tax invoice and keep it legible.
The tax invoice threshold that often matters in practice is more than $82.50 GST-exclusive, with records retained under the substantiation rules noted in the verified data. Digital copies are fine if they're clear and retrievable. That means a phone photo can work. A blurry image buried in your camera roll is asking for trouble.
Pro-Tip
- Capture immediately: photograph the receipt before it fades.
- Name consistently: supplier, date, amount, and category in the file name or app notes.
- Store centrally: don't split records across text messages, email folders, and random downloads.
- Match monthly: reconcile receipts against the bank feed while the purchase is still fresh.
Xero and MYOB are practical for ongoing bookkeeping. The ATO app can also help if your setup is simpler. For clients with catch-up work, Australia Wide Tax Solutions handles BAS preparation and tax lodgements, which is useful when the issue isn't just missing receipts but years of untidy records.
Vehicle records are where good claims go bad
Vehicle claims attract mistakes because owners mix methods, estimate usage, or rely on memory. For motor vehicles, the accepted methods in the verified data include the logbook method using a representative 12-week period, or the cents-per-kilometre method with the applicable cap and rate for the relevant year. The record-keeping requirement matters as much as the method itself.
A logbook often works better when business use is high and consistent. The cents-per-kilometre method is simpler, but simple doesn't mean sloppy. You still need a reasonable basis for the kilometres claimed.
This short explainer is worth watching before you try to backfill a year of fuel and travel from memory.
Keep the evidence that proves the method, not just the final number you typed into the return.
Why this matters: substantiation isn't admin for admin's sake. It's the difference between a defensible deduction and a claim that disappears the minute someone asks for backup.
Putting It Together: Apportionment, GST, and Your BAS
Business owners often find themselves in a difficult situation at this stage. They understand that an expense is partly business. They even know some GST may be claimable. Then they lodge a BAS with rough percentages and inconsistent coding, and the numbers no longer agree with the year-end return.
Around 55% of BAS errors stem from misclassifying items or incorrectly claiming GST credits, especially on mixed-use expenses, and late lodgers can face a General Interest Charge of up to 11.5% p.a. (FY25) according to the ATO guidance summarised in this BAS error resource.
Apportionment is where judgment matters
Apportionment means splitting an expense between business and private use on a fair basis. That sounds straightforward. It isn't, unless you keep a method and stick to it.
For example:
- Mobile phone: review a representative period and work out business call and data use.
- Home internet: estimate business usage based on actual working patterns.
- Home office running costs: use the accepted fixed-rate method where appropriate. The verified data refers to 67 cents per hour for 2024-25 for eligible work-from-home running costs.
- Vehicle expenses: apply the method you've chosen and keep the supporting records.
Common Pitfall
Claiming 100% of the GST on an expense with a private component is one of the most common BAS mistakes. If only part of the expense relates to business use, only that part of the GST credit is available.
GST doesn't fix a bad deduction. If the underlying expense is partly private, the GST claim is partly private too.
BAS errors usually start with lazy coding
The trouble rarely starts at lodgement. It starts months earlier when transactions are coded without thinking. A café owner uses the same card for stock, groceries, and a family fuel stop. A consultant lets software subscriptions renew on a personal card and sorts them out later. A landlord pays for repairs and improvements from the same account with no notes.
That's how BAS prep turns into detective work. Use clear chart-of-account categories, review mixed-use expenses before quarter end, and don't leave GST treatment to guesswork. If you need a practical walk-through, this guide on how to prepare a Business Activity Statement is worth keeping open while you reconcile. Why this matters: BAS accuracy affects cash flow, compliance risk, and how much rework you create for yourself at year end.
Claiming Major Purchases, Depreciation, and Instant Write-Offs
Big purchases need a different mindset. Buying a laptop, office furniture, or a work vehicle isn't the same as buying printer paper. These items are usually capital assets, which means the cost may need to be claimed over time rather than all at once.

The simplified depreciation rules under Division 40 have been a major change in Australian tax practice, and the verified data notes an immediate deduction threshold of $20,000 extended through 2023-24 for eligible businesses, while separate verified data also refers to a $150,000 instant write-off threshold for 2024-25 announced in the May 2024 Budget for eligible entities under the relevant settings. The key point is simple. Check the rule that applies for your year and eligibility before assuming you can deduct the full amount immediately.
Immediate deduction or depreciation
Take a common example. A sole trader buys a laptop used entirely for business. If it qualifies under the instant asset write-off rules that apply for that year and the business is eligible, the deduction may be immediate. If it doesn't qualify, the asset is generally depreciated over its effective life under the depreciation rules.
Now change the facts. The same sole trader uses the laptop partly for personal streaming and family admin. The claim has to be apportioned for business use first. The tax treatment only starts after that percentage is worked out.
A vehicle purchase raises the same issue. Owners focus on the sticker price. The primary questions are:
- Eligibility: Does the business meet the turnover and asset conditions for the year?
- Use: What percentage is business use?
- Timing: When was the asset first used or installed,, ready for use?
- Evidence: do the invoice and finance records line up with the claim?
For a deeper look at the immediate deduction side of the rules, keep this guide to what is an instant asset write-off handy. Why this matters: the tax outcome on a major purchase depends on timing, use, and eligibility, not on what the salesperson told you.
Your Next Steps An Error-Free Claims Checklist
The businesses that claim cleanly at tax time usually do the work in small steps during the year. Good records are not about admin for its own sake. They are what let you prove the claim, apply the right business-use percentage, and avoid redoing six months of transactions when the BAS or return is due.
Use this checklist to tighten the part of your process that is causing errors.
- Pick one system: use Xero, MYOB, the ATO app, or a spreadsheet with a cloud folder. Any of them can work if you use them consistently.
- Separate business and private spending: a dedicated business bank account makes coding cleaner and makes mixed-use problems easier to spot early.
- Review recurring charges: scan bank and card statements for software, memberships, subscriptions, and direct debits. Match them to tax invoices and check whether any are partly private.
- Start usage records now: for cars, phones, internet, and home office costs, keep the logbook, diary, or working papers from the start. Reconstructing business use later usually falls apart under review.
- Set a quarterly check-in: reconcile transactions, review GST coding, and test whether your expense categories still reflect how the business is operating before the BAS is lodged.
- Train the person doing the data entry: if staff or a bookkeeper post transactions, give them a written procedure with examples of common edge cases. A short SOP cuts repeat mistakes. If you need a model for documenting workflow, this guide on using Learniverse to automate procedure training is a practical example of turning ad hoc admin into a repeatable process.
Some claims need extra care. A sole trader using one mobile for both client calls and personal use needs a reasonable method for apportionment. A property investor paying for repairs through the same account used for private spending needs records that show what relates to the rental. An SME claiming software, vehicles, and contractor costs across multiple entities needs coding that matches the legal structure, not just the bank feed description.
DIY works for straightforward records. Once you are dealing with overdue lodgements, mixed-use assets, rental property adjustments, capital purchases, or messy books, professional advice can prevent expensive errors.
If you need help sorting overdue returns, preparing BAS, or working out how to claim business expenses without creating audit problems, Australia Wide Tax Solutions can help you get the records straight, apportion claims properly, and lodge with confidence.
Tax depreciation allows businesses and investors to deduct the cost of income-producing assets over their ATO-determined effective life. Rather than claiming the full cost in the purchase year, you deduct a portion annually using the prime cost or diminishing value method. The effective life of each asset determines how many years it is depreciated.
The instant asset write-off allows eligible businesses to immediately deduct the full cost of qualifying depreciable assets in the year they are first used or installed. Eligibility criteria, thresholds, and turnover limits change regularly — confirm current rules with the ATO for the 2025-26 income year rather than relying on prior-year thresholds, which are frequently amended.
Prime cost depreciates the asset at a constant percentage of original cost, producing equal annual deductions. Diminishing value applies a higher percentage to the remaining undeducted value, generating larger deductions in early years that reduce over time. The choice affects when deductions are taken but not the total amount ultimately claimed.
Residential property investors can claim plant and equipment depreciation (Division 40) on removable items like appliances and carpet, and the capital works deduction (Division 43) on structural components at 2.5% per year for buildings constructed after 15 September 1987. Legislation from May 2017 restricts Division 40 claims on second-hand residential assets for properties acquired after that date.
Keep purchase receipts, invoices, and documents establishing the date and cost of each depreciable asset. For property, retain construction contracts, settlement statements, and a quantity surveyor's schedule. The ATO can request records for up to five years after the relevant income year. Without records, depreciation claims can be reduced or disallowed on audit.
You give a good employee a perk because cash is tight. Maybe you cover their car parking. Maybe you pay a health insurance bill. It feels practical, decent, and far simpler than another pay rise.
Then payroll asks whether it creates FBT. Your employee later finds an unfamiliar figure on their income statement. They don't owe tax on that figure directly, but it can still affect HELP repayments, family assistance, and other income tests. That's the part many owners miss when they ask how to run a business well. Good intentions don't cancel bad tax treatment.
Most business owners don't get into trouble because they're reckless. They get into trouble because a benefit looked too small or too ordinary to matter.
- The 'Free Lunch' That Isnt Free for Your Business
- Decoding Reportable Fringe Benefits and RFBA
- The Gross-Up Calculation Demystified
- Your Reporting Duties as an Employer
- How RFBA Impacts Your Employees Finances
Table of Contents
- The 'Free Lunch' That Isnt Free for Your Business
- Decoding Reportable Fringe Benefits and RFBA
- The Gross-Up Calculation Demystified
- Your Reporting Duties as an Employer
- How RFBA Impacts Your Employees Finances
- Strategic Planning and Common Compliance Pitfalls
- Your Next Steps for FBT Compliance
The 'Free Lunch' That Isnt Free for Your Business
On Tuesday, you're trying to keep a good staff member from walking out the door. They've had a big quarter. You can't justify a salary jump yet, so you offer something that feels harmless. Covered parking near the office. A phone. Maybe a gym membership because morale matters.
By Friday, you've created a tax question.
That's how this usually starts. Not with fraud. Not with some elaborate scheme. Just with a business owner trying to do right by their team and assuming a non-cash perk sits outside the tax system.
The everyday decision that turns into a tax issue
A fringe benefit is often just an employer-paid expense or perk connected to someone's job. The business sees goodwill. The ATO asks a harder question. Was something of value provided to an employee or their associate because of employment?
If the answer is yes, Fringe Benefits Tax may be in play. And if the benefit crosses the reporting line, the employee may end up with a reportable amount on their income statement.
Practical rule: If you'd describe it as "just something extra we cover for them", stop and check it before you process it.
That sounds technical, but the business lesson is simple. Running a business isn't just selling well or hiring well. It's building systems that catch the hidden costs of ordinary decisions.
Why this matters for small businesses in particular
Australia had 2,589,595 small businesses, making up 97.2% of all businesses, and those small businesses employed over 5.1 million people. The same ABS release also notes that 60% fail within three years and 20% in the first year (ABS business counts and entries and exits). Those numbers matter because tax mistakes rarely arrive alone. They show up alongside cash flow pressure, weak records, rushed payroll, and owners doing ten jobs at once.
If you're still getting comfortable with the basics, a plain-English guide to fundamental business definitions can help put the commercial side and the compliance side on the same map.
Here's the blunt truth. Owners love to treat perks as culture. The ATO may treat them as taxable benefits. If your records are loose, the problem gets expensive fast.
Why this matters: a business survives on margins and discipline, not on assumptions that a "free lunch" is free.
Decoding Reportable Fringe Benefits and RFBA
The jargon confuses people because the terms sound alike. They aren't alike. If you mix them up, you can explain the wrong thing to your employee and report the wrong thing in payroll.

The four terms that people mix up
It's similar to a sponsored dinner.
The fringe benefit is the meal itself. It's the non-cash thing provided because of employment. That could be a car, parking, private expense payment, entertainment, or another benefit depending on the facts.
The FBT is the tax the employer may have to pay for providing that meal. The employee doesn't generally pay this tax. The business does.
A reportable fringe benefit is a fringe benefit that falls into the group that must be reported when the employee's total crosses the reporting threshold.
The RFBA, or Reportable Fringe Benefits Amount, is the figure that ends up recorded for the employee. It isn't their salary. It isn't taxed like normal wages. But it can still affect income-tested calculations.
The reporting trigger matters. If an employee has reportable fringe benefits with a grossed-up value of more than $2,000 in an FBT year, you generally need to report that amount on their income statement.
If you want a more technical walk-through of the tax itself, this guide on what is FBT tax is a useful companion.
Common benefits at a glance
| Benefit Provided | FBT / RFBA Status | AWTS Pro-Tip |
|---|---|---|
| Car parking | Often needs review for FBT treatment and possible reporting consequences | Don't assume parking is too minor to matter. Ask who used it, why it was provided, and how you valued it. |
| Employer-paid private expense | Often a fringe benefit and may become reportable | If the business pays a personal bill, flag it immediately in bookkeeping rather than burying it in general expenses. |
| Work device used mainly for work | May be exempt or treated differently depending on the facts | Keep evidence showing the business purpose. Vague claims like "they use it for work sometimes" won't help in a review. |
| Entertainment or meals | Can be tricky because the treatment depends on the type of benefit and method used | Entertainment is where owners get casual. Don't get casual. |
| Salary packaged benefit | May create both employer FBT issues and employee RFBA consequences | Explain the downstream employee effects before they agree to the package. |
A useful test is this. Ask two separate questions. "Do we owe FBT?" and "Will this be reportable to the employee?" They are related, but they are not the same question.
People searching how to run a business often want one neat rule for every perk. That rule doesn't exist. The value sits in classifying the benefit correctly, then treating tax payment and employee reporting as two separate tasks.
Why this matters: once you separate the vocabulary, the rest of the compliance process becomes much easier to manage.
The Gross-Up Calculation Demystified
The gross-up calculation scares people because it looks like accountant-only maths. It isn't. It's just the ATO's way of comparing a non-cash benefit with the pre-tax salary someone would have needed to buy that benefit themselves.

Why the ATO grosses up benefits
If an employee receives a perk instead of cash, the ATO doesn't want to compare apples with toolboxes. Cash salary is earned before tax. A benefit is received in another form. So the ATO grosses up the taxable value to estimate the equivalent gross salary.
That is the logic. Fair comparison.
There are two broad gross-up categories. Type 1 applies where the employer can claim a GST credit on the benefit. Type 2 applies where the employer can't. Which one you use depends on the underlying benefit and GST credit position, not on what feels convenient in payroll.
Get the category right before you touch the calculator. Wrong classification makes a neat spreadsheet useless.
If you've never worked through the timing and valuation side before, this refresher on fringe benefits tax time helps tie the moving parts together.
A simple worked example
Say your business provides an employee with a benefit worth $5,000. Start there. That's the taxable value before gross-up.
Then ask the key question. Could the business claim a GST credit on that benefit?
- If yes, you use the Type 1 gross-up rate.
- If no, you use the Type 2 gross-up rate.
I won't invent a rate here because the only safe way to handle rates is to use the current ATO figures that apply to the relevant FBT year. Rates can change, and lazy copying causes errors.
So the practical method looks like this:
-
Identify the benefit
Work out what was provided. Not the nickname used in the office. The legal character of the benefit. -
Calculate taxable value
In this example, that's $5,000. -
Check GST credit entitlement
That decides whether the benefit is Type 1 or Type 2. -
Apply the correct gross-up rate
The result becomes the grossed-up figure used for reporting analysis. -
Compare the employee's total reportable benefits with the reporting threshold
If the grossed-up total is more than $2,000 for the FBT year, reporting can be triggered.
A lot of owners get stuck because they focus on the formula before they classify the benefit. That's backwards. Tax is like building a house. If the slab is crooked, measuring the kitchen perfectly won't save it.
Common pitfall
- Using one gross-up rate for everything because it's quicker.
- Skipping GST analysis because bookkeeping hasn't been reconciled.
- Treating reimbursement and direct payment as identical when the facts may differ.
- Forgetting aggregation across benefits given to the same employee during the FBT year.
Why this matters: the gross-up step is where a modest-looking perk turns into a reportable figure with real consequences for payroll and staff communication.
Your Reporting Duties as an Employer
FBT reporting isn't glamorous. Neither is BAS. Both keep businesses out of trouble. Owners who treat these tasks as admin clutter usually pay for it later in cash, time, or ATO correspondence.
Treat FBT like BAS, not like an afterthought
For Australian SMEs, BAS compliance efficiency is a serious operational measure. Late BAS lodgements can trigger penalties starting at 2% of unpaid GST plus 2% per 28-day period thereafter, and firms with over 95% on-time delivery were reported to have 25% lower client churn and 12% higher year-on-year revenue growth (CPA Australia). I don't cite that to blur BAS and FBT into one tax. I cite it because the business habit is the same. Timely, accurate reporting protects the business.
That same discipline should sit behind your FBT process. Not because the ATO likes paperwork, but because your business needs one clean source of truth.
If you're reviewing your systems, a practical look at payroll software solutions can help you think through how data should move from payroll to reporting without manual chaos.
Your employer checklist
You need a working process, not good intentions. A solid checklist usually includes the following:
-
Identify benefits early
Flag potential fringe benefits when they are approved or paid. Don't wait until year-end and hope someone remembers why the company paid a personal invoice. -
Calculate taxable value
Work out the value using the correct method for that benefit type. FBT errors often begin with rough estimates that were never checked. -
Decide whether an FBT return is required
If tax is payable, the return and payment need to follow the ATO rules for the relevant year. -
Report any RFBA correctly
If the employee's reportable amount crosses the line, it must be shown on their income statement. -
Keep evidence
Logbooks, declarations, invoices, reimbursement records, and supporting notes matter. In an audit, memory is worthless.
A lot of this sits beside STP workflows, which is why this overview of Single Touch Reporting STP is worth having on hand when you map your payroll obligations.
Records are your first line of defence
Good records do more than prove numbers. They explain decisions.
Keep notes on who received the benefit, why it was provided, the dates involved, how you valued it, and whether GST credits applied. That last point matters more often than owners think.
If your file can't answer "what was provided, to whom, when, and why", it isn't an FBT file. It's a guess.
Why this matters: employer duties around FBT are manageable when they are part of a system, and expensive when they rely on memory.
How RFBA Impacts Your Employees Finances
Most employers stop thinking once they've dealt with the business tax side. That's a mistake. An employee can look at their income statement, see a reportable figure, and panic. If nobody explained it earlier, trust takes a hit.

Why employees care even when they pay no FBT
The employee usually doesn't pay the FBT itself. But the RFBA can still change how other systems assess them.
Think of it as financial amplification. In finance, this principle allows an amount to have a greater practical effect. The ATO uses a similar idea for some income tests. According to the ATO material on income tests, an employee's RFBA can affect calculations for up to 1.2 million Australians who access government benefits or have student debt (ATO income tests guidance).
That matters because your employee may say, "But I never received that amount in cash." They're right. The system may still count it for specific purposes.
If you're weighing packaged benefits against other remuneration options, this guide to what can you salary sacrifice is a helpful starting point.
Where RFBA shows up in real life
Here is where the confusion becomes personal.
-
HELP and HECS style debts
A reportable amount can increase the income figure used for repayment calculations. The employee may feel they have less breathing room even though their cash salary didn't jump by the same amount. -
Family assistance and other government support
Income-tested entitlements can shift when RFBA is included in the relevant calculation. -
Medicare levy surcharge assessments
For some employees, the broader income test position matters here too, especially when private health insurance choices are already in play.
The issue isn't just the number. It's timing. Employees often discover the effect after the benefit was agreed, after the year has been processed, and after their personal budget is already set.
An attractive package can still be a bad surprise if nobody explains the downstream effects.
A short explainer can help staff absorb the concept before you discuss package changes.
A better way to talk to staff about benefits
Don't present a benefit as "tax free" unless you're certain that's accurate in the context that matters. Even when the employee doesn't pay FBT directly, the benefit can still affect assessed income elsewhere.
Use plain language:
- Explain what the business is paying for
- Explain whether it may create an RFBA
- Explain that RFBA can affect income tests
- Tell the employee to consider their own HELP, family support, and health cover position before agreeing
This is one of the underrated parts of how to run a business. Staff don't just judge what you pay. They judge whether you warned them about the consequences.
Why this matters: transparency about RFBA protects trust, and trust is harder to rebuild than a payroll file.
Strategic Planning and Common Compliance Pitfalls
Most FBT problems don't come from obscure law. They come from ordinary sloppiness under pressure. Cash flow gets tight, wage pressure rises, and owners start using perks to solve morale problems without checking the tax treatment first.

The traps that catch ordinary businesses
One common trap is misclassification. A payment gets coded as staff welfare or office costs when it's really a personal benefit. Once that happens, the wrong data flows through bookkeeping, payroll, and year-end reporting.
Another is the casual use of the phrase "minor benefit". Owners hear that some small or infrequent benefits can be treated more favourably, then stretch that idea beyond recognition. In practice, the facts matter. Frequency matters. Records matter.
Car benefits create their own mess. If your logbook habits are poor, your certainty is fake.
Good FBT planning starts with scepticism. If a benefit seems too easy to ignore, it probably isn't.
International arrangements add another layer. There were 1.2 million Australians living abroad in 2025, and 22% of expat returns were late in 2025, highlighting how often remote compliance goes wrong (ABS overseas migration release). Fringe benefits can become especially messy when staff move between countries, remain on Australian payroll, or trigger dual-residency questions.
That isn't unique to Australia. Employment rules get technical fast across borders. If you want a comparison point for how detailed workforce obligations can become elsewhere, this guide to California labor compliance is a useful reminder that "we'll tidy it up later" is not a legal strategy.
Smarter ways to plan benefits
A better approach is to choose benefits with your eyes open.
-
Use salary packaging carefully
Salary sacrifice can be useful, but only if the employee understands the downstream effects and the employer understands the reporting consequences. -
Prefer cleaner options where possible
Some benefits are easier to support, easier to document, or more likely to fit exemptions or exclusions depending on the facts. Complexity is a cost. Treat it like one. -
Review overseas staff separately
Don't fold international workers into the standard local checklist and assume the answer will hold. -
Check interaction with other reportable items
Employees may already have other reportable amounts in the picture. This guide to reportable superannuation contributions helps show why remuneration planning should be done as one package, not in silos.
Common pitfall box
-
Contractor confusion
If a person is really an employee in substance, calling them a contractor won't magically remove risk. -
Patchy declarations
Missing paperwork turns a manageable issue into an argument you may lose. -
Overseas assumptions
Remote work and travel don't make Australian obligations disappear. -
Perk creep
One-off benefits have a habit of becoming regular practice. Repetition changes the risk profile.
Why this matters: strategy is what stops a nice gesture from becoming a tax problem with staff fallout attached.
Your Next Steps for FBT Compliance
If you're serious about how to run a business well, don't leave benefits in the "we'll sort that at year-end" basket. That's where expensive admin stories begin.
Economic pressure doesn't excuse weak systems. It exposes them. One cited measure showed Australian small business insolvencies rose 28% in 2025, while compliant businesses using integrated accounting grew 12% year-on-year versus a 5% average, reinforcing that proactive management of obligations like FBT and BAS supports resilience (analysis on underserved entrepreneurs and compliance pressure).
A practical action list
Start with a blunt review of what you're already giving people.
-
List every non-cash perk
Cars, parking, reimbursements, devices, entertainment, insurance, and any personal expense paid by the business. Don't rely on memory. Pull ledger accounts and payroll notes. -
Match each item to a tax treatment
Is it a fringe benefit, exempt, excluded, or something you need advice on? If you can't classify it confidently, flag it. Guessing is not efficiency. -
Check whether any employee may cross the reporting threshold
This matters for income statements and employee conversations, not just tax returns. -
Gather your support records
Invoices, declarations, logbooks, and GST treatment notes should all be together before deadline pressure kicks in. -
Review your payroll and bookkeeping workflow
If FBT data sits in email chains and memory, the process is broken.
When to get help quickly
Some situations deserve immediate advice rather than more reading:
- You offered benefits instead of pay rises during a tough trading period.
- Your records are incomplete and you aren't sure what was reported before.
- You have overseas staff or expat issues mixed into the arrangement.
- An employee is asking why their assessed income looks higher than expected.
- You have late or unlodged obligations and need to get compliant without making the mess bigger.
The cheapest time to fix an FBT issue is before you lodge the wrong figure. The second cheapest time is now.
The best operators I deal with aren't perfect. They're organised, honest about what they don't know, and quick to clean up weak spots. That's what keeps a business stable.
Why this matters: FBT compliance is not just a tax task. It's a business discipline that protects cash flow, staff trust, and decision-making.
FBT is paid by employers on non-cash benefits provided to employees in connection with employment. Common benefits include company cars for private use, below-market loans, and entertainment. The employer pays FBT at a flat rate of 47% on the taxable value of benefits. The employee does not pay FBT directly but the benefit may affect their adjusted taxable income.
The FBT year runs from 1 April to 31 March. Returns must be lodged and any liability paid by 21 May following the end of the FBT year. Tax agents may have extended dates. Employers who provide no fringe benefits do not need to lodge an FBT return, but should document the basis for not lodging.
Eligible battery electric vehicles and hydrogen fuel cell cars first used on or after 1 July 2022, with a purchase price below the luxury car tax threshold, can be provided as a fringe benefit without FBT applying. Plug-in hybrids lost exemption eligibility from 1 April 2025. The exempt benefit still generates a reportable fringe benefits amount for the employee.
Benefits with a GST-inclusive taxable value under $300 that are provided infrequently and irregularly are exempt from FBT. Examples include occasional restaurant meals and ad-hoc gifts. The exemption cannot be used for regular or systematic benefits — each occurrence must be assessed individually. Keep records showing the value and frequency of benefits relied upon.
Salary sacrifice does not reduce the employer's FBT liability in most cases. However, employees at public benevolent institutions, health promotion charities, and certain public hospitals can salary sacrifice significant amounts before FBT applies due to concessional FBT treatment. Private sector employees generally do not receive this concession — confirm with a tax adviser before establishing an arrangement.
If you need help untangling fringe benefits, cleaning up late reporting, or checking whether a staff perk has created a hidden obligation, Australia Wide Tax Solutions can help you get clear answers quickly. Their team works with business owners, individuals with overdue returns, property investors, and Australians living overseas, with practical support across tax returns, BAS, salary sacrifice questions, rental schedules, capital gains, and audit-risk issues.
If you're running a small business in Australia, you know it's a constant juggling act. But of all the balls you have in the air, tax compliance is the one you absolutely can't afford to drop. Getting it wrong isn't just a headache; it's a direct threat to your bottom line.
- Why Australian Small Business Tax Is So Complex
- What a Small Business Tax Accountant Actually Does
- Key Signs You Need an Accountant Immediately
- How to Choose the Right Accountant for Your Business
- Navigating Tax with Australia Wide Tax Solutions
Why Australian Small Business Tax Is So Complex

Picture your business revenue like water filling up a bucket. Every dollar you earn from your hard work goes straight in. The trouble is, the Australian tax system is riddled with complexities that can poke small, almost invisible holes in that bucket.
These leaks aren't a sudden gush of water; they're the slow, steady drips you barely notice. It might be an expense you categorised incorrectly, a deduction you didn't know you could claim, or a simple miscalculation on your Business Activity Statement (BAS). Month to month, it seems minor. But by the end of the financial year, those drips have drained away a significant chunk of your profit. You can get a better handle on this in our guide explaining what is BAS in accounting.
The Multi-Billion Dollar Tax Gap
This isn’t just a turn of phrase—it's a massive, quantifiable problem. The Australian Taxation Office (ATO) measures the "tax gap," which is the difference between the tax they calculate should be paid and what they actually receive. For small businesses, this gap is colossal.
In 2022–23, the ATO estimated the net small business income tax gap was a staggering $27.2 billion. This means only about 83% of the theoretical tax liability was actually paid. You can read the ATO's full findings on the small business income tax gap on their website.
This figure tells a clear story: the system is incredibly complex, and mistakes are common. Even fundamental concepts that seem straightforward, like understanding ce este TVA (what is VAT), can trip up business owners trying to do the right thing.
Without an expert on your side, you're left trying to plug these leaks on your own, risking your hard-earned money and inviting ATO scrutiny. This is where a professional small business tax accountant becomes your financial plumber. They find and patch those leaks, maximise your deductions, and make sure your bucket stays as full as possible.
What a Small Business Tax Accountant Actually Does

Many business owners only think about their small business tax accountant when the tax deadline is looming. But seeing them as just a once-a-year number-cruncher is a huge missed opportunity. A great accountant is more like a financial co-pilot, helping you navigate the complexities of Australian tax law all year round.
Their real job isn't just lodging your tax return. It's about providing a constant 'financial health check' on your business, spotting trouble before it costs you, and making sure you stay compliant and profitable. They shift from being just another expense to one of your most valuable strategic partners.
Beyond the Annual Tax Return
While getting your end-of-year tax return lodged is absolutely critical, it’s really just the tip of the iceberg. A dedicated small business accountant offers a whole range of services that protect your cash flow and keep your business on track.
Here’s what they are actually doing behind the scenes:
- Business Activity Statement (BAS) Preparation: They handle the nuts and bolts of your GST, PAYG withholding, and other tax obligations, ensuring your BAS is accurate and lodged on time, every time.
- Strategic Tax Planning: This is where you get the most value. They work with you to legally structure your business and finances to minimise your tax bill and keep more of your hard-earned money.
- Bookkeeping Support and Oversight: While they don't always replace your bookkeeper, they make sure your financial records are clean and correct. Many now use tools like automated data entry software for accountants to keep things efficient and error-free.
- Compliance and ATO Liaison: If the ATO comes knocking with questions or a review, your accountant is your first line of defence. They handle the communication and sort out any issues on your behalf.
When you bring in a professional, you're doing more than just outsourcing paperwork. You're gaining an expert advisor who knows the rules of the game inside and out—and can help you play it better. The right accountant is an essential part of your growth strategy.
From Cost Centre to Strategic Partner
At the end of the day, a modern small business accountant provides two things: peace of mind and financial clarity. They take care of the stressful compliance work that pulls you away from what you do best—running your business. As we cover in our guide, there are some serious benefits of using a tax agent in Australia.
This partnership makes sure your business not only meets its tax obligations but is also set up for long-term financial success. They find deductions you never knew about, offer advice on big purchases, and help you build a more resilient operation.
Key Signs You Need an Accountant Immediately
Thinking you need professional help isn't a sign of failure—it's the mark of a smart business owner who knows when to call in an expert. Too many entrepreneurs wait for a full-blown crisis before they pick up the phone to a small business tax accountant. The truth is, the warning signs are usually flashing long before that.
Think of it like the check engine light in your car. You can ignore it for a while, but that won't fix the underlying problem. It just makes a major breakdown on the side of the road more likely. Your business finances have similar warning lights, and they demand immediate attention.
When Your Finances Send an SOS
Certain situations are undeniable red flags. If you recognise any of these in your business, it’s time to stop what you’re doing and get an expert on your side. The longer you put it off, the more tangled and expensive the fix becomes.
Here are the most common distress signals we see:
You're Behind on BAS or Tax Lodgements: This is one of the most urgent signs there is. Falling behind with the ATO means penalties and interest charges are piling up, and they can spiral out of control fast. An accountant can talk to the ATO for you and map out a clear plan to get you back on track.
You’ve Received an ATO Audit or Review Notice: Nothing gets the heart racing like an official letter from the tax office. Trying to navigate an audit on your own is incredibly risky. A good accountant knows exactly what the ATO is looking for and can manage the entire process to secure the best possible outcome for you.
Your Cash Flow Is Unpredictable: Are you profitable on paper but always scraping by to pay the bills? This is a classic symptom of poor cash flow management. An accountant can dig into your numbers, pinpoint the bottlenecks, and help you build a more financially resilient business. It's why a regular business health check-up is so vital to stay ahead of these issues.
Proactive Triggers for Hiring an Accountant
It’s not all about crisis management. There are strategic moments in your business’s journey where an accountant’s advice isn’t just helpful—it’s invaluable. Getting expert input before you make a big move is the key to setting yourself up for tax-efficient success. Even when things look good, sharp financial oversight is crucial. For instance, recent Xero research shows small business sales have been volatile, with growth of only +3.0% y/y in the June quarter—a reminder that you always need to be on top of your numbers.
Consider bringing an accountant on board when you are:
Planning a Major Asset Purchase: Buying significant equipment, vehicles, or property has huge tax implications. An accountant can advise on the smartest way to structure the purchase to maximise your tax benefits, whether that’s through the instant asset write-off or by structuring depreciation schedules correctly.
Hiring Your First Employee: Taking on staff adds a whole new layer of complexity. Suddenly you're dealing with payroll, superannuation, and PAYG withholding. An accountant will make sure you’re set up correctly from day one, helping you sidestep costly payroll mistakes that can come back to bite you.
How to Choose the Right Accountant for Your Business
Picking a tax accountant is one of the biggest decisions you'll make as a small business owner. This isn't just about handing over a shoebox of receipts to get your tax return lodged. It's about finding a strategic partner who will protect your business, spot opportunities, and help you grow.
Getting this choice right can be the difference between just surviving and genuinely thriving. You need to treat this process like you're hiring a key member of your team—because that’s exactly what you’re doing.
This flowchart gives you a quick visual on when it's time to stop DIY-ing and call in a professional.

As you can see, falling behind on your tax is a massive red flag. It’s a clear signal you need an expert to get you back on track with the ATO, fast.
Your Accountant Hiring Checklist
Before you start booking calls, get your non-negotiables sorted. This checklist ensures you're only talking to legitimate, qualified professionals who actually understand the maze of Australian tax law.
Here’s what you absolutely must confirm:
- Professional Credentials: Are they a Certified Practising Accountant (CPA), a Chartered Accountant (CA), or a registered tax agent with the Tax Practitioners Board (TPB)? These aren't just letters after their name; they're your guarantee of their training and ethical standards.
- Relevant Industry Experience: Have they actually worked with businesses like yours before? An accountant who gets the unique cash flow challenges of a construction business or the specific deductions for an e-commerce store is worth their weight in gold.
- Tech-Savviness: Do they live and breathe modern cloud accounting software like Xero, MYOB, or QuickBooks? A tech-forward accountant means streamlined processes and real-time advice, not clunky spreadsheets.
Ticking these boxes confirms they have the baseline skills. The real test is finding out how they think, communicate, and plan. That’s where the interview comes in.
Key Interview Questions to Ask
Once you’ve got a shortlist, it’s time to dig deeper. Your goal isn't to talk about fees—not yet. It's to understand their service style and how they partner with their clients. Don't be afraid to ask direct questions.
To make sure you find the right fit, it's helpful to have a structured set of questions ready. Here are some essentials we recommend asking any potential accountant.
Essential Accountant Interview Questions
| Category | Question to Ask | What to Listen For |
|---|---|---|
| Communication | How do you prefer to communicate with your clients? How often will I hear from you? | You want a style that matches yours. Do you prefer quick emails, scheduled phone calls, or face-to-face meetings? A good accountant proactively communicates, not just when a deadline is looming. |
| Tax Strategy | What is your approach to proactive tax planning? | Bad answer: "We'll sort it out at tax time." Good answer: "We look at your numbers quarterly to find savings opportunities and help you plan for tax payments well before 30 June." |
| ATO Dealings | How do you handle an ATO audit or enquiry for a client? | The only acceptable answer is that they manage the entire process for you. They should act as your shield, your representative, and your advocate, so you can focus on running your business. |
| Service & Value | What do you do for clients beyond just lodging their tax returns? | Listen for mentions of cash flow forecasting, business structuring advice, or performance reports. You're looking for a partner, not just a data entry clerk. |
| Technology | Which accounting software are you most experienced with, and how do you use it to help your clients? | They should be experts in the major platforms and be able to explain how technology helps them provide better, faster, and more strategic advice. |
Asking these questions gives you a much clearer picture of whether they are just a compliance-focused number cruncher or a genuine strategic advisor who can add real value to your business.
Understanding Common Pricing Models
Finally, you need to talk money. The right fee structure should fit your budget and the level of service you need. The most important thing here is transparency—no surprise bills.
Here are the most common models you’ll encounter:
- Fixed-Fee: A set price for a defined scope of work, like your quarterly BAS lodgements and annual tax return. This is great for budget certainty.
- Hourly Rate: You pay for the time spent on your accounts. This can work for one-off projects or quick questions but can be unpredictable for ongoing work.
- Monthly Retainer: A recurring monthly fee for a package of ongoing services and advisory support. This is the best model for businesses that want a true financial partner they can call on anytime.
Navigating Tax with Australia Wide Tax Solutions
Choosing a small business tax accountant isn’t just about getting your compliance paperwork filed. It's about finding a partner who genuinely understands what it takes to run a business in Australia and is invested in your financial wellbeing. At Australia Wide Tax Solutions, we've built our entire service model around the real-world problems business owners face, offering practical support that goes far beyond ticking boxes.
We get it. You're not just running a business; you're building a livelihood. Your time is your most precious resource, which is why we’ve made our services incredibly convenient. Forget blocking out half your day to travel to an office. Our secure online appointments let you connect with an expert accountant from anywhere—whether you're in a regional town or working from overseas.
Solutions for Real-World Business Problems
Every business hits a few bumps in the road, and tax is often one of the biggest. We don't just talk theory; we deliver targeted solutions for the challenges you’re actually up against.
Our specialised services are designed to fix common business headaches:
- Late or Unlodged Returns: Falling behind with the ATO is stressful. Our team is brilliant at getting you back on track. We handle all the ATO communications, work to minimise any penalties, and still fight to get you the maximum refund you're entitled to.
- Complex BAS Preparation: Business Activity Statements can turn into a nightmare of paperwork and calculations. We can take the entire process off your hands, ensuring everything is calculated correctly and lodged on time so you can dodge costly mistakes and get back to running your business.
This kind of practical support is vital. Australia’s small business community is a true powerhouse, with nearly 2.7 million businesses generating almost $590 billion in revenue and employing 42% of the private-sector workforce. To see just how important this sector is, you can explore detailed insights on small business tax reform. We're here to help you protect your contribution to that success.
More Than an Accountant—A True Partner
We believe in empowering our clients, not just processing their numbers. Alongside our hands-on support, we provide a whole suite of resources like easy-to-use tax calculators and checklists. These tools help you make smarter financial decisions every single day, not just once a year at tax time.
Our mission is simple: to provide personalised, efficient service with a maximum refund guarantee. We're not just another number-cruncher; we are your strategic partners, dedicated to helping you protect your assets and build a more profitable future.
From our offices in Sydney and Brisbane to our appointment-only services in Greece for Australian expats, we offer seamless, nationwide support. Australia Wide Tax Solutions gives you the deep expertise of a large firm combined with the personal care and attention you'd expect from a local accountant, giving you total confidence to meet your tax obligations and smash your business goals.
Your Top Questions About Business Tax Accountants, Answered
Thinking about getting professional tax help often brings up a lot of questions around cost, value, and whether it’s truly necessary. If you’re a business owner weighing this decision, you’re in good company. We hear these questions all the time.
Here are some clear, straight-to-the-point answers to the most common queries we get from business owners. Our aim is to cut through the jargon and give you the confidence to make the right call for your business's financial future.
How Much Does a Small Business Tax Accountant Cost in Australia?
It's best to think of an accountant's fee as an investment, not just a cost. The price tag really depends on your business’s complexity, its size, and how much support you're after. Most accountants will use one of three common pricing models, so you know what you’re in for.
Here’s what you’ll likely come across:
- Fixed-Fee Packages: Many firms, including ours, offer bundled pricing for recurring jobs like your quarterly BAS and annual tax return. These packages can run anywhere from $1,500 to over $5,000 a year, which gives you certainty for budgeting.
- Hourly Rates: For one-off projects or a quick bit of advice, an accountant might charge by the hour. You can expect this to be between $150 and $450 per hour.
- Monthly Retainers: For businesses that need ongoing strategic advice, a monthly retainer is the way to go. These often start from $300 per month and build a real partnership between you and your accountant.
At Australia Wide Tax Solutions, we believe in up-front, transparent pricing that’s tailored to what you actually need. You get maximum value without any nasty surprises when the bill arrives.
Can an Accountant Help with My Overdue Tax Returns?
Yes, absolutely. Dealing with late tax returns is a core part of what a good small business tax accountant does. The stress of having overdue lodgements hanging over your head is immense, and an accountant can lift that weight immediately.
They become your official representative, speaking directly with the ATO for you. This is a game-changer when it comes to negotiating payment plans or asking for penalties and interest to be reduced or waived.
A specialist firm like Australia Wide Tax Solutions focuses on helping clients with late and unlodged returns. Our job is to get you compliant as quickly and painlessly as possible, all while working to secure the maximum refund you're entitled to, even for past financial years. An accountant creates a clear path forward and removes the stress of dealing with the ATO alone.
What Is the Difference Between a Bookkeeper and an Accountant?
That's a great question, and it’s easy to get them mixed up. The roles are very different but work together.
Think of it like building a house. Your bookkeeper is the builder on the ground, meticulously laying every brick and making sure the day-to-day work gets done right. They handle tasks like:
- Recording daily transactions
- Reconciling your bank accounts
- Managing payroll and sending invoices
The accountant is the architect who designed the blueprint. They take all the work the builder has done and ensure the final structure is sound, compliant, and built for the long haul. Their job includes:
- Preparing official financial statements
- Lodging tax returns and Business Activity Statements (BAS)
- Providing strategic tax planning advice to legally minimise what you owe
- Helping you make smart, long-term business decisions based on the numbers
A bookkeeper organises your financial past; an accountant helps you strategically shape your financial future.
Do I Need an Accountant If I Use Software Like Xero or MYOB?
Yes, we strongly recommend it. Tools like Xero or MYOB are fantastic for keeping your financial data organised, but a tool is only as good as the person using it. It's no substitute for professional expertise.
Imagine your accounting software is a high-performance car—it’s powerful and has all the features you need. Your accountant, however, is the expert driver who knows all the road rules, the hidden shortcuts that save you money, and how to steer clear of traffic jams (like an ATO audit).
An accountant takes the data from your software and provides insights the program simply can't. They interpret what the numbers mean, spot tax-saving opportunities you might miss, ensure you’re compliant with ever-changing Australian tax laws, and guarantee your reporting is 100% accurate. The software organises your numbers; the accountant gives them meaning.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
Ready to gain clarity and confidence in your business finances? The team at Australia Wide Tax Solutions is here to provide personalised, expert support for all your tax and accounting needs. Book your appointment online today and discover how a true financial partner can help you thrive.
An Activity Statement is the form Australian businesses use to report and pay key taxes like GST and employee tax withholdings to the Australian Taxation Office (ATO). Think of it as your business’s regular ‘tax check-in’. The two main types are the Business Activity Statement (BAS) for GST-registered businesses and the Instalment Activity Statement (IAS) for everyone else.
- What Is an Activity Statement in Plain English
- How to Read Your Business Activity Statement (BAS)
- Who Needs to Lodge an Activity Statement and When
- Navigating Lodgement Deadlines and Avoiding Penalties
- Your Step-by-Step Guide to Lodging Your Activity Statement
What Is an Activity Statement in Plain English
Let's cut through the confusing tax jargon for a moment.
Imagine your business is a small shop. Throughout the month, you collect a little extra on every sale for the government (that's the GST). At the same time, you set aside money from your employees' wages for their income tax (PAYG Withholding). An Activity Statement is simply the form you use to tell the ATO exactly how much you’ve collected and then pay it to them.
But it’s a two-way street. The form is also where you claim back the GST you paid on things you bought for your business, like new equipment or office supplies. This ensures you only hand over the net difference.
The Activity Statement is essentially the scorecard that keeps your business and the ATO on the same page. It reconciles the taxes you've collected on the government's behalf with the tax credits you're entitled to claim.
The Two Main Types of Activity Statements
While many people use the term "BAS" as a catch-all, there are actually two distinct forms you might receive from the ATO. Getting this right is the first step to staying compliant.
- Business Activity Statement (BAS): This is the one most businesses deal with. You'll use a BAS if your business is registered for Goods and Services Tax (GST). It’s an all-in-one form for reporting your GST, PAYG withholding for staff, PAYG instalments for your own income tax, and a few other tax obligations. You can get a deeper look at the fundamentals in our guide explaining what BAS is in accounting.
- Instalment Activity Statement (IAS): This is a much simpler version. You’ll receive an IAS if you are not registered for GST but still need to report other taxes to the ATO. This is common for businesses that need to remit PAYG withholding for employees or pay their own PAYG instalments to pre-pay income tax throughout the year.
The table below breaks down the key taxes you'll find on a typical Activity Statement.
Key Taxes Reported on Your Activity Statement
This table breaks down the primary taxes on a typical Business Activity Statement, helping you quickly identify what applies to your business.
| Tax Component | What It Means for You | Who It Typically Affects |
|---|---|---|
| GST | Reconciling the Goods and Services Tax you’ve collected on sales against the GST you’ve paid on purchases. | All businesses registered for GST (turnover of $75,000+ or voluntary registration). |
| PAYG Withholding | Reporting and paying the income tax you’ve withheld from your employees' wages and salaries. | Any business with employees. |
| PAYG Instalments | Pre-paying your estimated income tax in instalments throughout the year so you don't face a large bill at tax time. | Sole traders, partners, and other individuals who earn business or investment income. |
| FBT Instalment | Paying your estimated Fringe Benefits Tax liability for benefits provided to employees, like a company car for private use. | Businesses that provide fringe benefits to staff and have a liability over a certain threshold. |
Understanding these components is crucial because it directly impacts your business's cash flow and compliance. Missing one can lead to trouble down the road.
Why Is It So Important for Your Business
Your Activity Statement isn't just another bit of paperwork; it's a fundamental part of Australia's tax system. Introduced alongside the GST on 1 July 2000, the BAS has become the backbone of tax compliance for over 4.5 million businesses as of 2025. You can explore more government statistics on the Australian economy at the ABS website.
For the businesses we work with every day at Australia Wide Tax Solutions, lodging an Activity Statement correctly and on time is non-negotiable. It ensures you meet your legal obligations, helps you manage cash flow by giving you a clear picture of your tax liabilities, and—most importantly—prevents stressful and expensive penalties from the ATO for late or incorrect reporting.
How to Read Your Business Activity Statement (BAS)
Cracking open your first Business Activity Statement can feel intimidating. It often looks like a wall of codes, boxes, and tax jargon that makes little sense at first glance.
But once you know what you’re looking at, that jumble of numbers starts to tell a clear story about your business's financial health over the last quarter. Think of it less as a chore and more as a financial snapshot—a tool you can use to stay on top of your obligations.
Let's walk through it with a simple, real-world example. Imagine you’re a digital marketing consultant. Every time you invoice a client, you include GST. And every time you buy software or a new laptop for your business, you pay GST. The BAS is simply where these two sides of the coin meet.
The diagram below shows exactly how your day-to-day business activities flow through to the ATO via your Activity Statement.

This visualises the direct line connecting what you do every day in your business, the ATO’s reporting framework, and the BAS form that makes it all official.
Decoding the GST Section
For most businesses, the heart of the BAS is the GST section. This is where you'll spend most of your time.
- G1 Total Sales: This is your starting point—the total amount you've invoiced during the period. It includes all your sales, whether they had GST on them or not. For our consultant, this would be the total of all their client invoices for the quarter.
- 1A GST on Sales: Here, you report only the GST component you collected on behalf of the ATO. If our consultant invoiced a total of $11,000, they would report $1,000 at 1A (which is 1/11th of the total sales figure).
- 1B GST on Purchases: This is where you get your money back. You report the total GST you paid on business-related purchases and expenses. Think software subscriptions, fuel, office supplies, or that new laptop.
The final calculation is simple: 1A (GST collected) minus 1B (GST paid). If you get a positive number, you owe that amount to the ATO. If it's negative, congratulations—the ATO owes you a refund.
At its core, the BAS is a balancing act. It ensures you only pay the net difference between the GST you collected for the government and the GST you paid as a business expense.
Understanding Your Payroll and Income Tax Obligations
If you have staff or you're a sole trader paying your own income tax in advance, your BAS will cover these areas too.
- W1 Total Salary, Wages, and Other Payments: If you have employees, you report the total gross amount you paid them right here.
- W2 Amount Withheld from Payments at W1: This is the income tax (PAYG Withholding) you've held back from your employees' pay. You're now passing this on to the ATO on their behalf.
For sole traders, the PAYG Instalment section is just as important. This is how you pre-pay your own income tax throughout the year to avoid a massive bill at tax time. The ATO will either give you a set amount to pay (T1) or a rate to calculate the payment yourself (T2).
Since its introduction with the GST back in 2000, the Business Activity Statement has become a cornerstone of the Australian tax system, processing trillions in business transactions. With GST collections projected to hit a staggering $87.6 billion in the 2024-25 financial year, getting it right is crucial. At Australia Wide Tax Solutions, we see that 78% of the small-to-medium businesses we work with prefer quarterly lodgement cycles, which speaks to its power as a regular tool for financial management. You can find more insights about BAS in Australia from recent analyses.
Who Needs to Lodge an Activity Statement and When
Figuring out if you need to lodge an activity statement can feel confusing, but the rules are actually quite clear once you know what to look for. Not every business owner has to do it, and understanding where you stand is the first step to avoiding missed deadlines and unnecessary stress.
The main trigger for lodging a Business Activity Statement (BAS) comes down to one thing: GST registration. If your business has a current or projected annual turnover of $75,000 or more, the law says you must register for GST. Once you're registered, lodging a BAS becomes a non-negotiable part of your tax life. This threshold ensures smaller operators and side-hustles aren’t tangled up in the same reporting as larger companies. For non-profit organisations, that bar is set higher at $150,000.
At its core, the requirement to lodge is all about accountability. If you're collecting GST on behalf of the government or withholding tax from employee wages, the ATO needs a formal way for you to report and hand over those funds. The activity statement is that official channel.
But it’s not just about GST. If your business has employees, you have to withhold tax from their wages under the Pay As You Go (PAYG) withholding system. This obligation means you must report those amounts to the ATO through an activity statement, even if you’re not registered for GST.
Your Lodgement Frequency
How often you need to report to the ATO depends on the size and turnover of your business. Your lodgement frequency is automatically set when you register for an Australian Business Number (ABN) and GST.
- Quarterly: This is the default for most small to medium-sized businesses. If your annual turnover is less than $20 million, you’ll generally lodge your BAS every three months. It's the most common cycle we see with our clients.
- Monthly: Once your business grows and your annual turnover hits $20 million or more, you’ll be moved to a monthly lodgement schedule. Some smaller businesses also opt for monthly reporting to keep a tighter grip on their cash flow.
- Annually: This is reserved for very small businesses that have voluntarily registered for GST but still have an annual turnover below the $75,000 threshold.
Don't Forget the Instalment Activity Statement (IAS)
So, what happens if you have tax obligations but you're not registered for GST? This is where the Instalment Activity Statement (IAS) comes into play. You’ll need to lodge an IAS if you handle PAYG withholding for employees but don't meet the GST registration threshold.
On top of that, individuals and sole traders who earn significant business or investment income might be asked by the ATO to pay PAYG instalments. This is a system designed to help you pre-pay your income tax in smaller chunks throughout the year, so you don't get hit with a massive tax bill when you lodge your annual return. If this applies to you, the ATO will send you an IAS to report and pay these amounts.
Navigating Lodgement Deadlines and Avoiding Penalties
Getting your activity statements lodged on time isn’t just good housekeeping—it's absolutely critical for avoiding some hefty penalties from the Australian Taxation Office (ATO). The first step to staying in control of your business finances and keeping the ATO happy is knowing exactly when your lodgements are due.
For most small and medium businesses, this means lodging on a quarterly basis. Getting ahead of these dates is non-negotiable, as the ATO has a very strict compliance framework.
Standard Quarterly BAS Lodgement Deadlines for 2026-2027
To keep you on track, here is a clear schedule of the standard ATO lodgement and payment due dates for quarterly Business Activity Statements for the upcoming financial year.
| Quarter | Period Covered | Due Date |
|---|---|---|
| Quarter 1 | 1 July 2026 – 30 September 2026 | 28 October 2026 |
| Quarter 2 | 1 October 2026 – 31 December 2026 | 28 February 2027 |
| Quarter 3 | 1 January 2027 – 31 March 2027 | 28 April 2027 |
| Quarter 4 | 1 April 2027 – 30 June 2027 | 28 July 2027 |
It's vital to remember that these aren't just suggestions. Missing these dates triggers a cascade of financial consequences that can turn a simple oversight into a significant debt.
The Real Cost of Being Late
The ATO doesn’t mess around with late lodgements. For a small business, a penalty is calculated at a rate of one penalty unit for every 28-day period (or part thereof) that your statement is overdue, capped at a maximum of five penalty units.
But that’s not all. On top of the initial penalty, the ATO applies a General Interest Charge (GIC) to any tax you haven't paid. This interest compounds daily, meaning a small debt can snowball with alarming speed.
Late filings are a massive issue. In the 2024-25 period alone, there were 180,000 overdue BAS lodgements. This resulted in a staggering $52 million in penalties, with fines ranging from $313 to $3,130 per late lodgement, plus the GIC on top. You can dig into these figures in the latest Treasury economic and fiscal updates.
The combination of a Failure to Lodge (FTL) penalty and compounding daily interest creates a double-hit that can seriously impact your business's cash flow. What might start as a small unpaid GST amount can spiral into a debt several times larger if left unaddressed.
The Advantage of Using a Tax Professional
Here’s a crucial tip: one of the biggest advantages of working with a registered tax professional like us at Australia Wide Tax Solutions is gaining access to extended lodgement deadlines. Because we lodge electronically for our clients, the ATO gives us special agent-only due dates.
This can give you up to an extra four weeks to lodge and pay your quarterly BAS.
That extra breathing room is invaluable. It dramatically reduces compliance stress, gives you more time to get your records in order, and is the single best way to avoid the harsh penalties that come with being late. If you’re finding it hard to keep up, our guide on tax deadlines and how to avoid fines is packed with more detailed strategies.
Your Step-by-Step Guide to Lodging Your Activity Statement
Lodging your Activity Statement shouldn't be a quarterly headache. When you have a solid process, it becomes just another part of your business rhythm. This guide breaks it all down into simple, repeatable steps, turning what feels like a complicated chore into a straightforward task.

Step 1: Get Your Records in Order
Before you even touch the form, you need clean and accurate records. Good bookkeeping isn't just a "nice-to-have"; it’s the absolute foundation of a painless BAS lodgement.
Start by pulling together all the key documents for the reporting period. Here’s your must-have checklist:
- Sales Records: A complete summary of your business sales, making sure to separate taxable sales from any GST-free ones.
- Expense Records: Every single receipt and invoice for business purchases where you paid GST. Don't miss any – these are your credits!
- Bank Statements: All your business bank and credit card statements. Use these to double-check your transactions so nothing slips through the cracks.
- Payroll Summary: If you have staff, you'll need the total gross wages you paid (W1) and the total tax you withheld from their pay (W2).
Having this information organised and ready to go makes everything that follows a thousand times easier. For a deeper dive, our guide on https://awts.net.au/blog/how-to-prepare-business-activity-statement/ is an invaluable resource.
Step 2: Choose How You'll Lodge
With your numbers sorted, it's time to decide how you're going to file your statement. You have a few options, and the right one depends on your business and your confidence level.
Choosing your lodgement method comes down to a trade-off between convenience, cost, and how comfortable you are with the process. What’s perfect for a sole trader might not work for a growing business with a team.
Here are the main ways to lodge:
| Lodgement Method | The Good | The Not-So-Good |
|---|---|---|
| Accounting Software | Highly automated, slashes manual errors, and links directly with your bookkeeping (e.g., Xero, MYOB). | You'll need a paid subscription and some initial setup time. |
| Directly via myGov | It’s free and gives you direct access to your ATO online services. | It's a completely manual process, which means the risk of making an error is much higher. |
| Registered Agent | Guarantees accuracy, gives you access to expert advice, and often comes with extended deadlines. | Involves a professional fee for the service. |
Many business owners find online portals a good middle ground. If you’re going it alone, you can find a solid guide on how to lodge BAS online to walk you through it.
Step 3: Settle the Account
Once you've lodged, the final piece of the puzzle is settling up with the ATO. If the GST you collected on sales (1A) is more than the GST you paid on purchases (1B), you'll have a bill to pay.
The ATO offers plenty of ways to pay, including BPAY, credit/debit card, or setting up a direct debit.
On the flip side, if you’re owed a refund, the ATO will usually deposit it straight into your nominated bank account within 14 days. This final step closes the loop on your Activity Statement for the period, keeping you compliant and on track.
Take Control of Your Business Tax Obligations
Getting your head around what an activity statement is is a great first step. But real control comes from getting the lodgement right, every single time.
For most business owners we talk to, managing BAS or IAS lodgements feels like a constant battle. It’s a grind of time-consuming admin, the ever-present risk of costly mistakes, and the stress of a deadline that’s always just around the corner. This is where getting the right professional support can turn a major headache into a smooth, strategic part of your business.
At Australia Wide Tax Solutions, we offer BAS services specifically designed to take this pressure completely off your shoulders. Our expert accountants make sure every detail is accurate, every credit you're entitled to is claimed, and every lodgement is on time, guaranteed.
The Benefits of Expert Support
Working with us is about more than just ticking a compliance box; it’s about giving you genuine peace of mind. Here’s what our clients gain:
- Extended Lodgement Deadlines: As registered tax agents, we get access to later due dates from the ATO, giving you valuable breathing room to get your information together.
- Maximised Credits: We comb through your expenses to ensure you claim every single dollar of GST credit you're entitled to. This directly improves your cash flow.
- Guaranteed Accuracy: Our professional review process eliminates the risk of those small errors that can attract unwanted ATO attention and painful penalties.
We provide expert guidance tailored for small businesses and property investors, all backed by convenient online services and offices right across Australia. When our team is handling your activity statements, you can get back to focusing your energy on what you actually love doing—running and growing your business.
Let us help you turn your tax obligations into a seamless and efficient part of your financial strategy.
Frequently Asked Questions About Activity Statements
Even after you get your head around the basics, a few specific questions always seem to pop up right when it's time to lodge. We hear these all the time from business owners, so let's tackle the most common ones to clear up any confusion for good.
What Happens if I Make a Mistake on My BAS?
It’s a common worry, but don't panic—it's usually fixable. If you find a mistake on a BAS you've already lodged, you can often correct it on your next activity statement. The ATO allows this as long as the error is within certain time and value limits.
For bigger or more complicated errors, you might need to formally revise the original statement. A tax professional can quickly figure out the best way to handle it, ensuring you stay compliant without creating a bigger headache down the track.
Do I Have to Lodge a BAS with No Business Activity?
Yes, absolutely. If you're registered for GST, you have to lodge an activity statement for every single reporting period, even if you made zero sales and had zero expenses. This is what's known as lodging a 'nil' BAS.
Failing to lodge, even when you don't owe any tax, can still trigger penalties for lodging late. Lodging a nil BAS is a non-negotiable step that tells the ATO you're on top of your obligations, you just had nothing to report for that period.
Lodging a 'nil' BAS is a crucial signal to the ATO. It communicates that you are actively managing your tax obligations, preventing your business from being flagged for non-compliance.
Can I Get an Extension on My BAS Due Date?
Requesting a deferral directly from the ATO is possible in truly exceptional circumstances, but it’s definitely not a standard option. The most reliable way to get an extension is to work with a registered tax or BAS agent.
Agents have access to a special lodgement program with later due dates for their clients. This often gives you up to an extra four weeks to get everything prepared and filed without risking a penalty.
Of course, your questions might go beyond just activity statements. For other frequently asked questions, you can find great resources that provide extra context.
Feeling overwhelmed by your BAS or IAS? Let the experts at Australia Wide Tax Solutions take the stress out of tax time. We ensure your lodgements are accurate, on time, and optimised to maximise your credits. Contact us today to streamline your business tax obligations.
#TaxTips #SmallBusinessAU #BAS #ATO #AccountingSolutions #AWTS #BusinessCompliance #ActivityStatement #AustralianTax #Bookkeeping
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
Keeping on top of your Business Activity Statement (BAS) is non-negotiable, and thankfully, the BAS due dates for 2025 follow a predictable quarterly rhythm. Typically, your BAS is due on the 28th of the month right after the end of a quarter.
- Your Quick Reference Guide to 2025 BAS Due Dates
- A Detailed Look at Quarterly BAS Deadlines
- Monthly and Annual BAS Lodgements: Who Fits Where?
- The Strategic Advantage of Using a Registered Agent
- Understanding the Penalties for a Late BAS
For instance, the BAS for the October-December 2024 quarter needs to be lodged by 28 February 2025. Similarly, the January-March 2025 quarter has a deadline of 28 April 2025. Hitting these dates is absolutely essential if you want to steer clear of penalties from the Australian Taxation Office (ATO).
Your Quick Reference Guide to 2025 BAS Due Dates
So, what exactly is a Business Activity Statement? It’s a reporting form that any Australian business registered for Goods and Services Tax (GST) has to lodge with the ATO. It’s designed to bundle several tax obligations into one report, making it simpler to stay compliant. If your business turns over less than $20 million in GST, you'll almost certainly be reporting on a quarterly basis.
This guide lays out the key lodgement and payment deadlines for the 2025 calendar year. Knowing these dates is the first step toward managing your business's financial health and avoiding unnecessary fines. The timeline below gives you a quick visual summary of the different reporting schedules—monthly, quarterly, and annual—that apply to different businesses.
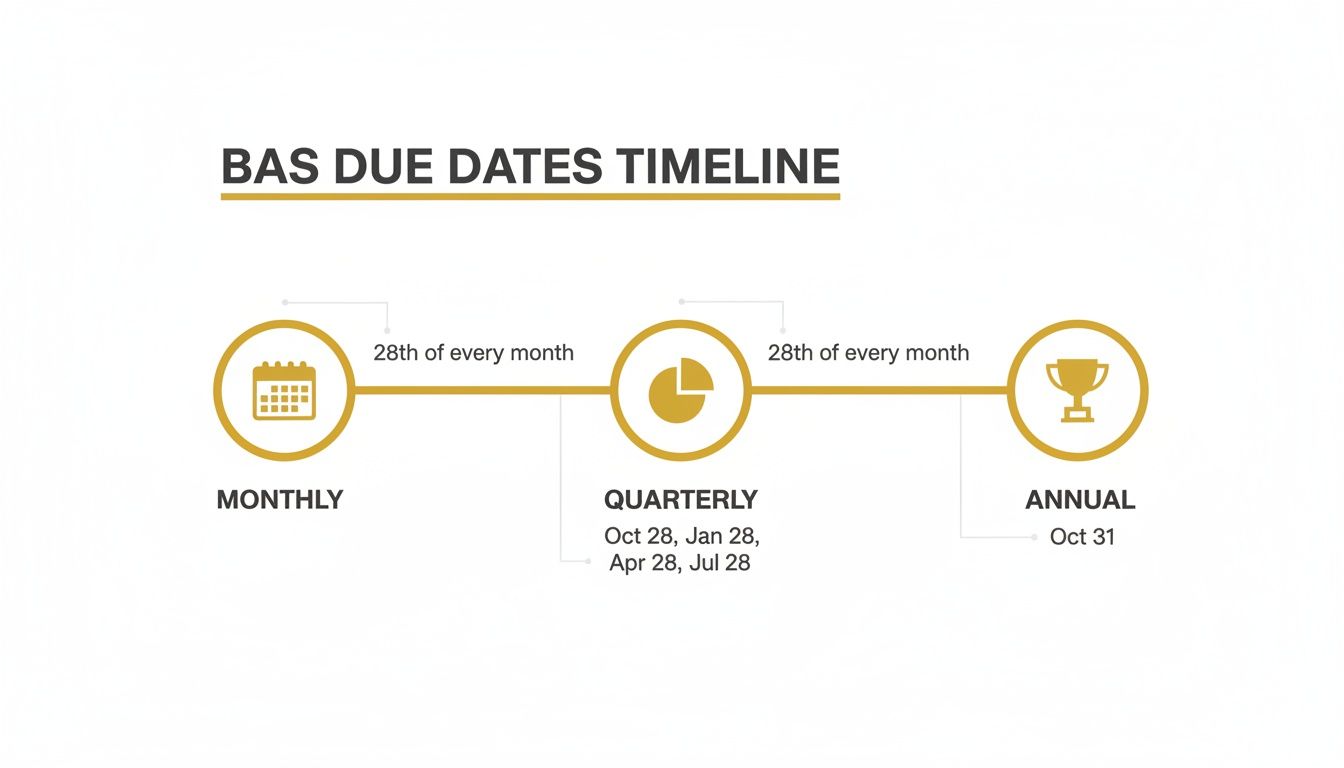
The key takeaway here is pretty clear: your lodgement frequency is directly tied to the size and turnover of your business, with the vast majority of small businesses landing in that quarterly cycle.
Who Needs to Lodge a BAS?
First things first, you need to be certain about your obligations. You're required to lodge a BAS if your business is registered for GST. This kicks in for most businesses once their annual turnover hits $75,000 or more (or $150,000 for non-profits).
Your BAS is used to report on a few key tax areas all at once:
- Goods and Services Tax (GST) you've collected on sales, minus any GST credits you can claim on purchases.
- Pay As You Go (PAYG) Withholding for the tax you’ve withheld from employee salaries.
- Pay As You Go (PAYG) Instalments to cover your own estimated income tax bill.
- Other taxes like fringe benefits tax (FBT) or fuel tax credits, if they apply to you.
If you want to get a better handle on what a BAS involves and why it's such a fundamental part of business accounting, our detailed article explains what BAS is in accounting. Having that foundational knowledge makes navigating the BAS due dates for 2025 a whole lot easier.
A Detailed Look at Quarterly BAS Deadlines
For most small businesses in Australia, lodging your BAS quarterly is the standard. It’s the default rhythm for keeping on top of your tax obligations. This applies to any business with a GST turnover of less than $20 million, and it strikes a good balance between staying compliant and not getting buried in paperwork. Getting these BAS due dates for 2025 right is one of the fundamentals of keeping the ATO happy.
The quarterly system simply chops the financial year into four reporting periods. For each quarter, you’ll need to pull together your GST info, PAYG withholding, and any other relevant tax figures, then lodge and pay by a set date. The deadlines are predictable, which helps a lot when you’re trying to plan your bookkeeping and manage cash flow.
Key Quarterly BAS Periods and Dates for 2025-2026
It's easy to get mixed up, as the 2025 calendar year straddles two different Australian financial years. You have to be careful to track the deadlines for both to make sure nothing slips through the cracks.
Here are the specific quarterly deadlines you need to circle in your calendar.
Covering the 2024-2025 Financial Year:
- Quarter 2 (October - December 2024): Due by 28 February 2025
- Quarter 3 (January - March 2025): Due by 28 April 2025
- Quarter 4 (April - June 2025): Due by 28 July 2025
Covering the 2025-2026 Financial Year:
- Quarter 1 (July - September 2025): Due by 28 October 2025
- Quarter 2 (October - December 2025): Due by 28 February 2026
Just remember, if a due date lands on a weekend or public holiday, the ATO gives you a pass—you can lodge and pay on the next business day without any drama.
The Power of Using a Registered BAS Agent
Handing your BAS over to a professional does more than just give you peace of mind. It unlocks some serious perks, with the biggest one being deadline extensions. The ATO offers concessional lodgement programs exclusively to registered BAS and tax agents, giving their clients a valuable buffer to get their books finalised.
Let's put that into perspective. Imagine you run a busy cafe in Sydney. You're juggling suppliers, staff, and customers, and suddenly the Quarter 1 BAS deadline for the 2025-26 financial year is staring you down. That period, from 1 July to 30 September 2025, has a standard lodgement date of 28 October 2025 if you're lodging it yourself.
But if you work with a registered BAS agent who lodges it electronically for you, that deadline gets pushed back to 25 November 2025. That extra month can be a complete lifesaver, giving you time to reconcile everything properly without the last-minute panic. You can find more details on how these extensions work across different quarters by exploring lodgement date insights from tax professionals.
This extension provides crucial breathing room, turning a stressful compliance scramble into a structured, calm process. It gives you and your agent the time needed to ensure total accuracy, seriously cutting down the risk of mistakes and a potential ATO audit.
Monthly and Annual BAS Lodgements: Who Fits Where?
While most businesses get into a comfortable quarterly BAS rhythm, your reporting schedule isn't a one-size-fits-all deal. The Australian Taxation Office (ATO) actually sets your frequency based on your turnover, creating different rules for big players and tiny operators. Knowing exactly where your business stands is key to hitting the right BAS due dates in 2025.
For the big end of town, the cycle is much faster. If your business has a GST turnover of $20 million or more, you’re on the hook for monthly BAS lodgements. This keeps a steady stream of tax information and payments flowing to the ATO, which makes sense given the sheer volume of transactions these larger companies handle.
This monthly schedule also helps big businesses manage their tax liabilities in smaller, more predictable chunks, which is a massive help for accurate cash flow forecasting.
Monthly Lodgement Deadlines
The rule for monthly lodgers is beautifully simple: your BAS is due on the 21st day of the month right after the end of the reporting period. Critically, there are no lodgement extensions available from registered agents for monthly BAS, so this date is set in stone.
- Example for a large wholesaler: Imagine a large import-export company in Sydney with a GST turnover of $25 million. They have to report monthly. For all their business activity in January 2025, their BAS lodgement and payment deadline is 21 February 2025. For February's activity, the due date is 21 March 2025, and so on throughout the year.
This constant rhythm keeps their financial data current and makes tax compliance a regular part of their monthly accounting process, rather than a monster task that builds up every quarter.
Annual Lodgement Rules and Dates
On the complete opposite end of the scale, some very small businesses can radically simplify their paperwork by reporting just once a year. This option is generally available to businesses that have voluntarily registered for GST and have an annual GST turnover of less than $75,000 (or $150,000 for non-profits).
The standard due date for an annual BAS is 31 October, following the end of the financial year. Conveniently, this lines up with the deadline for individual tax returns, letting business owners tackle both obligations in one go.
A sole trader running a small online craft store who voluntarily registered for GST is a perfect example. Annual reporting is a game-changer for them. Instead of wrestling with quarterly paperwork, they can consolidate all their GST info for the 2024-25 financial year and lodge their single BAS by 31 October 2025.
There's a handy exception, too. If you aren't required to lodge a tax return, the deadline for your annual BAS is pushed out to 28 February of the following year. And, as always, using a registered tax or BAS agent often opens up different due dates, making life even easier for micro-businesses.
The Strategic Advantage of Using a Registered Agent
Managing your Business Activity Statements is about more than just hitting deadlines. It's a core financial task where getting the numbers right is everything. Bringing a registered BAS or tax agent on board isn't just about outsourcing the work; it's a strategic move that turns a stressful compliance chore into a smoothly managed part of your business.
These professionals bring the expertise needed to sidestep the kind of costly errors that can quickly attract the wrong sort of attention from the Australian Taxation Office (ATO).
More importantly, working with a registered agent gets you access to the ATO's lodgement concession program. This is a game-changer for many businesses, as it provides valuable extensions on your quarterly BAS due dates for 2025. That extra time isn't just a buffer—it's crucial breathing room to get your accounts finalised without rushing. You can do a proper reconciliation, ensuring every GST credit is claimed and every dollar of PAYG withholding is accounted for correctly.
Comparing Due Dates: A Clear Advantage
The difference in deadlines between lodging yourself and using an agent is significant. This isn't just about avoiding a late lodgement; it’s a smart way to manage your finances better.
Let's look at a straight comparison for the main quarterly periods in the 2025-26 financial year:
| Reporting Period (2025-26) | Standard Due Date (Self-Lodged) | Registered Agent Due Date | Extra Time Gained |
|---|---|---|---|
| Quarter 1 (Jul - Sep 2025) | 28 October 2025 | 25 November 2025 | 4 weeks |
| Quarter 3 (Jan - Mar 2026) | 28 April 2026 | 26 May 2026 | 4 weeks |
| Quarter 4 (Apr - Jun 2026) | 28 July 2026 | 25 August 2026 | 4 weeks |
As you can see, you get an entire extra month for most quarters. The one exception is Quarter 2 (covering Oct-Dec), where the standard 28 February deadline already accounts for the Christmas and New Year break, so no further agent extension is typically offered. This extra time allows you to finalise your records without being under the pump, which always leads to better quality reporting.
Beyond Extensions: The Broader Benefits
The real value of using a registered agent goes well beyond just getting more time. Their expertise acts as a powerful defence against the financial pain and administrative headaches that come with non-compliance.
- Fewer Mistakes: Agents are trained to spot the common slip-ups in GST calculations, payroll figures, and income reporting. This protects you from those unintentional errors that could easily trigger an audit.
- Less Stress: Handing off the complexities of BAS prep frees up your time and mental energy. It lets you get back to focusing on what you do best—running and growing your business.
- Proactive Tax Management: A good agent does more than just lodge forms. They'll offer advice on managing cash flow around your BAS payments and keep you up to speed on any changes in tax law that affect you.
By bringing in an agent, you’re not just buying time. You're investing in accuracy, compliance, and genuine peace of mind. This proactive step dramatically reduces your risk of copping the Failure to Lodge penalties and General Interest Charges we detail in our section on penalties.
Understanding the Penalties for a Late BAS
Missing one of the key BAS due dates in 2025 is more than just a minor slip-up; it can trigger some pretty significant and escalating financial penalties from the Australian Taxation Office (ATO). The consequences go far beyond a simple late fee, hitting your business's cash flow and damaging your compliance record. Knowing what these penalties are is the first step to making sure you never have to pay them.
The main penalty you’ll face for missing a deadline is the Failure to Lodge (FTL) penalty. This is an automated system that applies a fine for every 28-day period (or even part of a period) that your BAS is outstanding. The amount isn't arbitrary—it's calculated using a system of penalty units, which the government adjusts from time to time.
How FTL Penalties Are Calculated
The size of the FTL penalty is directly tied to the size of your business. The ATO does this to ensure the fines are proportionate to turnover, but it means bigger businesses feel the sting much more.
- Small entities: If your business has a turnover of less than $1 million, you'll face a penalty for each 28-day block, capped at five penalty units.
- Medium entities: For businesses with turnover from $1 million up to $20 million, that penalty rate is doubled.
- Large entities: For those with turnover exceeding $20 million, the penalty rate is five times the base amount.
This tiered system means that an oversight that costs a small business a few hundred dollars could easily cost a larger company thousands for the exact same mistake.
The Real Cost of a Late BAS
Let's break it down with an example. A single penalty unit is currently $330. If a small business lodges its BAS just one day late, it immediately gets hit with a $330 penalty. If that BAS is still unlodged 30 days later, another $330 penalty is applied, bringing the total to $660. This can climb up to a maximum of $1,650 for a single late statement.
The reality is that the ATO is ramping up its enforcement activities. The penalty system works a bit like driver demerit points—initial fines get worse with each overdue cycle, hitting repeat offenders the hardest. With over 14.1 million individual tax returns lodged by April 2025 (a 3% jump from the previous year), it’s clear that more people are coming under increased ATO scrutiny.
On top of the FTL penalty, the ATO also applies a General Interest Charge (GIC) on any unpaid tax. This isn't a one-off charge; it's calculated daily and compounds, meaning your debt just keeps growing until both the outstanding tax and the FTL penalty are paid in full.
This one-two punch of penalties makes late lodgement a very expensive mistake. If you do find yourself falling behind, our guide on managing late BAS payments offers practical strategies to get back on track.
A Practical Checklist for Accurate BAS Preparation
Good preparation is the secret to lodging a Business Activity Statement without the usual last-minute panic. If you’re systematic about it, you can avoid common mistakes, claim every credit you're entitled to, and have everything ready long before the BAS due dates in 2025. A simple checklist can turn what feels like a complex chore into a manageable process.
This is a tool that helps you pull your financial data together methodically, whether you're lodging the BAS yourself or just getting the figures ready for your accountant. It's really about building a solid, repeatable habit that cleans up your bookkeeping and gives you real confidence in the numbers you're reporting.

To make this even easier, we've put together an actionable checklist. You can use this table each quarter to track your progress and make sure nothing gets missed.
Quarterly BAS Preparation Checklist
| Task | Status (To Do / Complete) | Notes |
|---|---|---|
| FINANCIAL RECONCILIATION | ||
| Reconcile all bank & credit card accounts | Match all transactions in your accounting software. | |
| Clear out any 'suspense' or unallocated accounts | Every transaction needs a proper home. | |
| Review accounts receivable and payable reports | Ensure invoices/bills are in the correct period. | |
| GST & SALES VERIFICATION | ||
| Check all sales for correct GST coding | GST-free vs. taxable sales. | |
| Verify you have a valid tax invoice for all GST credits claimed | No tax invoice = no GST credit claim. | |
| Review non-deductible expenses (e.g., entertainment) | Make sure you haven't claimed GST on these. | |
| PAYROLL & PAYG | ||
| Reconcile PAYG withholding from payroll reports to the ledger | The figures must match perfectly. | |
| Confirm gross wages reported on the BAS match payroll summaries | A common ATO check area. | |
| FINAL REVIEW & LODGEMENT | ||
| Generate BAS report from software and review all figures | Do the numbers look reasonable? | |
| Lodge the BAS via your preferred method | E.g., Online services for business, registered agent. | |
| Set a reminder for the payment due date | Lodge and pay are separate steps! |
Following these steps methodically will put you in a great position for a smooth, accurate BAS lodgement every single time. Now, let's break down the key areas in more detail.
Financial Reconciliation and Review
Before you even glance at the BAS form, your core financial accounts need to be spot-on. This is the foundation, and getting it right is non-negotiable for correct reporting.
- Reconcile All Bank Accounts: Go through every transaction in your business bank accounts, credit cards, and loan accounts. Make sure they are all matched and accounted for in your bookkeeping software. No exceptions.
- Clear Suspense Accounts: Take a look at your general ledger for anything sitting in "suspense" or "uncategorised" accounts. These are red flags. They must be properly allocated before you finalise your BAS.
- Review Accounts Receivable and Payable: Check that your outstanding invoices and bills are correctly dated. This ensures they land in the right reporting period, which is crucial for accurate GST timing.
To get your BAS right, you need to understand the mechanics behind the numbers. A great resource for this is a guide on how to work out VAT, as the principles of calculating tax on transactions are fundamental to GST.
GST and Sales Verification
Your Goods and Services Tax figures are the absolute heart of the BAS. A quick double-check here can prevent you from overpaying the ATO or, just as bad, claiming credits you aren't actually entitled to.
Honestly, the most common BAS errors we see come from incorrect GST coding. Taking ten minutes to review your sales and purchase transactions can save you from massive headaches and potential ATO penalties down the line.
Here’s exactly what to verify:
- Check All Sales for Correct GST: Run a sales report and scan it to make sure GST has been applied to all your taxable sales. At the same time, confirm your GST-free sales are coded correctly.
- Verify GST Credits on Purchases: Go through all your business purchases. You must hold a valid tax invoice for every single GST credit you intend to claim. The ATO is very strict on this.
- Account for Non-Deductible Expenses: Look at expenses like client entertainment or certain travel costs to ensure you haven’t incorrectly claimed GST credits on them. It's an easy mistake to make.
Payroll and PAYG Withholding
Finally, your payroll data must line up perfectly with what you report on the Business Activity Statement. Any discrepancies here will eventually be flagged.
- Reconcile PAYG Withholding: Match the total PAYG withholding from your payroll reports for the quarter with the corresponding liability account in your general ledger. The two figures should be identical.
- Confirm Gross Wages: Ensure the total gross wages figure you report on the BAS is exactly what your payroll summary reports show for the period. This is another critical number the ATO uses for data matching.
How to Lodge and Pay Your BAS Correctly
Once your Business Activity Statement is prepared and looks spot on, the final steps are lodging the form and paying whatever you owe the Australian Taxation Office (ATO). The ATO has several electronic methods designed to make this whole process as painless as possible, helping you hit those crucial BAS due dates for 2025 without any last-minute panic.
For many business owners, the most direct path is using the ATO’s Online services for business. It’s a secure government portal where you can lodge your BAS, look at old statements, and manage your tax accounts from one spot. It's a reliable, straightforward option if you handle your own compliance.
Another very efficient way to get it done is by lodging through Standard Business Reporting (SBR) enabled software. If you're already using an accounting platform like Xero, MYOB, or QuickBooks, you can usually lodge your BAS right from the software. This is a game-changer because it connects your bookkeeping directly to your reporting, slashing the risk of manual data entry errors.
Choosing Your Lodgement Method
How you choose to lodge often comes down to your business setup and how comfortable you are with digital tools. Each method has its own clear advantages.
- Online Services for Business: This is ideal for sole traders and small businesses who manage their own books and prefer to deal directly with the ATO's own platform.
- SBR-Enabled Software: Absolutely perfect for businesses that have their finances sorted in accounting software. It keeps everything neat and tidy within a single system.
- Registered BAS or Tax Agent: This is the best option if you want an expert to cast their eye over everything, check for accuracy, and get you access to those handy extended lodgement deadlines.
Lodging electronically isn't just a nice-to-have anymore; it's the standard way of doing things. It gives you a secure digital receipt of your submission and makes sure the ATO gets your info instantly—which is vital when a deadline is breathing down your neck.
Making Your BAS Payment
Just remember, lodging your BAS and paying it are two separate actions. Submitting the form on time is critical, but making sure the payment actually lands with the ATO by the due date is just as important.
The ATO offers a few different payment options to suit everyone. BPAY is one of the most common, letting you pay straight from your bank account using the unique biller code and reference number on your BAS. You can also pay online through the ATO website with a credit or debit card, but keep in mind a card payment fee might apply.
For a completely set-and-forget process, you can set up a direct debit from your ATO Online services account. This gives the ATO permission to withdraw the amount you owe on the due date, ensuring you never miss a payment. If you want to get a deeper understanding of the entire lodgement and payment cycle, our detailed guide on the Business Activity Statement lodgement process breaks it all down for you.
Answering Your Top BAS Deadline Questions
When it comes to your Business Activity Statement, a few common questions pop up time and time again. Getting these sorted is key to staying on the right side of the ATO and avoiding any last-minute panic as the BAS due dates for 2025 roll around. We've compiled the most frequent queries we get from business owners just like you.
One of the biggest questions is about due dates that land on a weekend or public holiday. Good news here: the Australian Taxation Office (ATO) gives you a bit of breathing room. The deadline automatically shifts to the next business day, so you can lodge and pay then without any risk of a penalty.
Correcting Mistakes and Asking for More Time
So, what happens if you spot a mistake right after you’ve lodged your BAS? Don't stress, it happens more often than you think, and the ATO has a clear process for fixing things. For most minor errors with GST or fuel tax credits, you can simply adjust it on your next BAS, as long as the mistake is within the ATO's defined limits.
For bigger stuff, especially anything related to PAYG withholding, you'll likely need to go back and revise the original BAS you submitted. The golden rule is to act fast and be upfront with the ATO—it goes a long way in maintaining a good compliance record.
Another hot topic is whether you can apply for a lodgement extension yourself. While registered BAS and tax agents get automatic extensions for their clients, you can ask the ATO for a deferral directly if you're facing exceptional circumstances.
To apply, you’ll need a solid reason, like a natural disaster, a serious personal illness, or another major event that's genuinely stopped you from lodging on time. You absolutely must get in touch with the ATO before the due date to talk through your situation.
Just remember, these kinds of deferrals are decided case-by-case and aren't a sure thing. If you want consistent, reliable extensions and professional oversight, partnering with a registered agent is still the sharpest strategy for managing your BAS obligations.
Feeling the pressure of BAS deadlines and compliance? The expert team at Australia Wide Tax Solutions can take BAS preparation and lodgement completely off your plate. We ensure everything is accurate and on time, so you can get back to what you do best—running your business. Contact us today to make your tax obligations simple by visiting https://www.awts.net.au.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
Before you even think about filling out a single form, the first thing to figure out is whether you actually need to register for GST. For most Australian businesses, there's a magic number you need to know: $75,000 in annual turnover. If your business income crosses that line, GST registration isn't optional—it's mandatory.
- Do You Really Need to Register for GST?
- Get Your Information Ready for a Smooth Registration
- The Easiest Ways to Complete Your GST Registration
- You’re Registered for GST – Now What?
- Common GST Mistakes and How to Avoid Them
Getting this right from the start can save you a world of administrative headaches down the track.
Do You Really Need to Register for GST?
This is the first question every single business owner in Australia should ask themselves. The answer usually comes down to your turnover, but it's not always that simple. The ATO has specific rules and some important nuances that can easily catch you out if you're not careful.
Understanding these thresholds isn't just a box-ticking exercise; it's about setting up your business finances correctly from day one.
Understanding the Turnover Thresholds
For most businesses, the main trigger for mandatory GST registration is hitting a specific turnover figure. But it's not the same for everyone.
To give you a quick overview, here are the key thresholds you need to be aware of.
GST Registration Thresholds at a Glance
| Entity Type | Mandatory Registration Turnover Threshold | Special Conditions |
|---|---|---|
| Most Businesses | $75,000 or more (GST-exclusive) | Turnover is based on current or projected gross income, not profit. |
| Non-Profit Organisations | $150,000 or more (GST-exclusive) | Applies to charities, community groups, and other NFP entities. |
| Taxi & Rideshare | $1 | No threshold. Registration is required from the very first dollar earned. |
It's vital to remember that before you can even think about registering for GST, you must have an Australian Business Number (ABN).
Now, let's break down what "turnover" really means. It’s the total value of all sales your business makes, not just your profit. This includes:
- Sales of goods and services here in Australia.
- Income from any exports (even if they are technically 'GST-free').
- Every other stream of business income you have.
A common pitfall we see all the time is business owners thinking turnover is calculated only within a single financial year. It's actually calculated on a rolling 12-month basis. You could easily cross the threshold in the middle of February, not just on 30 June.
Special Cases for Immediate Registration
While that $75,000 figure covers most businesses, some industries play by different rules.
The big one is for anyone providing taxi, limousine, or rideshare services. If you drive for a company like Uber or Didi, you must register for GST from the very first dollar you earn. There is no minimum turnover threshold. Period.
This rule exists because these services fall under the 'taxi travel' industry classification, which has always had its own specific GST obligations. If you fail to register immediately, you could be facing some serious penalties and back-dated tax bills from the Australian Taxation Office (ATO). You can dive deeper into this in our article about when you need to register for GST.
Voluntary GST Registration
So, what happens if your turnover is well below $75,000? You actually have the choice to register for GST voluntarily.
Sure, this means you'll have to start charging GST on your sales and lodging Business Activity Statements (BAS). But it also unlocks a major benefit: you can claim GST credits. These are essentially refunds for the GST included in the price of goods and services you buy for your business.
For a new business spending big on equipment, stock, or setup costs, registering voluntarily can be a really smart financial move. It can significantly improve your cash flow by letting you claim back the GST you paid on all those initial expenses.
Get Your Information Ready for a Smooth Registration
Nothing stalls an online application faster than having to stop and search for a missing document. Trust me, the single best thing you can do to make GST registration quick and painless is to get your paperwork in order before you start.
Think of it as your pre-flight checklist. Getting these items together first prevents that frustrating stop-start dance with the online portal and helps you submit an accurate application right from the get-go.
Core Business Identifiers You Will Need
At a bare minimum, the Australian Taxation Office (ATO) will ask for a few key pieces of information to identify your business.
These are completely non-negotiable, so make sure you have them on hand:
- Australian Business Number (ABN): Your ABN is the cornerstone of your business identity. If you don't have one yet, you absolutely must apply for it first. We cover this in our guide to registering an Australian Business Number (ABN) in Australia.
- Tax File Number (TFN): You'll need your personal TFN if you’re a sole trader. If you operate as a company, trust, or partnership, you’ll need the business's TFN instead.
When you're pulling all this together, using a good document management software can seriously streamline the process. It just makes life easier by keeping your important records organised and accessible when you need them most.
Business Details and Financial Projections
Beyond the basic identifiers, the application will dig into the specifics of how your business actually runs. Having clear answers ready for these questions will save you a huge amount of time.
For example, a freelance copywriter applying for GST will need to confirm their business structure (most likely a sole trader) and give a solid estimate of their projected turnover. On the other hand, a new retail shop owner should have their expected annual sales figures ready to justify the registration from day one.
A crucial tip: be realistic with your turnover projections. The ATO uses this information to get a clear picture of your business activity. Even if you're registering voluntarily, your projected figures should still reflect a genuine commercial enterprise.
You should also be prepared to provide:
- Your desired GST registration start date. This can be today, a date in the future, or in some specific cases, a past date (this is called backdating).
- Your chosen accounting basis. You'll need to select either 'cash' or 'accrual' for reporting GST. This is a key decision, so know which one suits your business.
- Your primary business activity. Be ready to clearly describe what your business does. The ATO uses this to assign you an industry code.
The Easiest Ways to Complete Your GST Registration
Alright, you've got your key business details sorted. Now for the main event: the actual GST registration. The good news is the Australian Taxation Office (ATO) gives you a few different ways to get this done, so you can pick whatever works best for you. For most business owners I talk to, doing it online is the clear winner for speed and convenience.
Before you dive in, just make sure you have your ABN, TFN, and identity documents ready to go. Think of it like a quick pre-flight check.
Essentially, your ABN and TFN are the foundations, and proving you are who you say you are is the final piece of the puzzle.
Getting It Done Online
The most direct and efficient route for most people is registering online. You can tackle this through the Australian Business Register (ABR) website or via the ATO's online services, which you access securely with your myGovID.
The great thing about the online portal is that it lets you add GST (and other tax registrations like PAYG withholding) to an existing ABN. This streamlines everything into one straightforward task rather than having you jump through multiple hoops.
The Two Big Questions You'll Have to Answer
As you work through the online form, you’ll hit two crucial questions. Your answers will have a real impact on your bookkeeping down the track, so it pays to understand them before you click "submit".
- When do you want your registration to start? You can choose today's date, a future date, or even backdate it. Backdating is a must if you've already shot past the $75,000 turnover threshold, but be aware it means you'll be on the hook for GST from that earlier date.
- How will you account for GST? You have to pick either a 'cash' or 'accrual' basis. This decision determines when you report and pay the GST you owe.
For most small businesses, especially service-based ones, the 'cash' basis is usually much simpler. It means you only account for GST on money that has actually landed in your bank account, which lines up perfectly with your real-world cash flow. The 'accrual' basis, on the other hand, means you have to report GST the moment you issue an invoice—even if your client hasn't paid you yet.
What if I Don't Want to Do It Online?
While the online portal is fantastic, it's not the only way. It's good to know the alternatives are there if you're not comfortable with the digital process or you'd just rather have an expert handle it.
Even if you go old-school, the ATO typically processes registrations within 28 days, so it’s smart to get the ball rolling well before you hit that $75,000 turnover mark.
Let’s quickly weigh up the other options.
Using a Registered Tax or BAS Agent
This is the "do it for me" choice. An agent, like our team here at Australia Wide Tax Solutions, takes care of the entire registration for you from start to finish.
- Pros: You get complete peace of mind that it's done correctly. An agent provides expert advice on those tricky decisions like the start date and accounting basis, and it saves you a ton of time. It's the perfect option if your business structure is a bit complex or you just want it handled right, the first time.
- Cons: Naturally, this professional service comes with a fee.
Registering Over the Phone
You can also just call the ATO directly. An operator will walk you through all the questions over the phone.
- Pros: You get to speak to a real person at the ATO who can answer any immediate questions you might have during the process.
- Cons: You’ll likely have to wait on hold, and you still need to have all your information organised and ready to read out clearly and accurately.
Ultimately, the best method comes down to your own confidence, how complex your business is, and what you feel your time is worth. For the vast majority, online is the way to go, but knowing that expert help is available is a pretty good safety net to have.
You’re Registered for GST – Now What?
Getting that GST registration confirmation is a fantastic milestone for your business. It's a sign of growth. But before you get too comfortable, it's important to understand that this is where the real work begins. Your business operations now need to adapt to your new tax responsibilities to stay compliant with the Australian Taxation Office (ATO).
This transition isn't just about adding 10% to your prices; it's about weaving your GST obligations into the fabric of your daily workflow. From how you invoice to the way you keep records, a few key changes are needed right away.
Master Your Business Activity Statement
Your most important new responsibility is lodging your Business Activity Statement (BAS). Think of the BAS as your regular report card to the ATO. It’s where you tell them how much GST you’ve collected on sales and how much GST you’ve paid on business purchases.
The difference between these two figures determines whether you owe the ATO more money or if you’re getting a refund. Timely lodgement isn't just a suggestion—it's non-negotiable and crucial for avoiding penalties. For a deeper dive, our guide on Business Activity Statement lodgement has all the details.
Your reporting frequency is directly linked to your business turnover. It scales with your size:
- Monthly if your turnover is over $20 million.
- Quarterly for most businesses turning over between $75,000 and $20 million.
- Annually for some smaller, voluntarily registered businesses.
While around 18% of businesses still lodge on paper, the vast majority—over 95%—lodge digitally for greater speed and accuracy.
Issue Compliant Tax Invoices
Now that you're registered, every invoice you issue for a taxable sale has to be a compliant tax invoice. This is more than just a standard invoice with "plus GST" added at the bottom. The ATO has specific rules.
To be valid, a tax invoice must include:
- The words "Tax Invoice" clearly displayed.
- Your business name and ABN.
- The date the invoice was issued.
- A brief description of the items sold.
- The GST amount, shown separately or with a statement like "Total price includes GST".
For example, if you're a builder invoicing a client for a $5,000 job, your invoice must clearly show $500 as the GST component, making the total $5,500. If you don't issue a compliant tax invoice, your client can't claim a GST credit for your service. That can create headaches for them and really damage your professional reputation.
Claiming Back GST Credits
One of the biggest perks of being GST-registered is claiming back the GST you pay on business expenses. This is known as a GST credit or an input tax credit, and it’s a game-changer for your cash flow.
To claim these credits on your BAS, you absolutely must hold a valid tax invoice for any purchase over $82.50 (including GST). This makes meticulous record-keeping non-negotiable.
Let's go back to our builder. Say you buy $2,200 worth of timber for a job. That price includes $200 in GST. By holding onto the tax invoice from the supplier, you can claim that $200 back from the ATO on your next BAS. Over a year, these credits add up to significant savings and make a real difference to your bottom line.
Common GST Mistakes and How to Avoid Them
Getting your head around new GST obligations can feel like you’re trying to navigate a minefield blindfolded. Even with the best of intentions, it's incredibly easy for business owners to make small mistakes that quickly snowball into major headaches.
The best way to stay out of trouble? Learn from the common slip-ups others have made. It’s the fastest way to keep your business compliant and financially healthy right from the start.
One of the most frequent errors we see is choosing the wrong registration start date. If you suddenly realise you passed the $75,000 turnover threshold three months ago, you absolutely must backdate your registration to that point. Kicking the can down the road can lead to penalties for uncollected GST, putting you on the back foot with the Australian Taxation Office (ATO) before you've even started.
Another classic trap is picking an accounting method that strangles your cash flow. While the accrual basis makes sense for bigger companies with dedicated finance teams, most small businesses find the cash basis far more practical. It neatly lines up your GST payments with the actual money hitting your bank account. This simple choice prevents that painful scenario where you owe tax on an invoice your client hasn't even paid yet.
The High Cost of Poor Record-Keeping
Messy records aren't just an admin nightmare—they're a direct hit to your bank account. Without proper tax invoices for your business purchases, you simply can't claim any GST credits. It's that black and white.
Let's say you're a café owner and you've just dropped $11,000 on a shiny new coffee machine. That price tag includes $1,000 in GST. If you lose that tax invoice, you've just waved goodbye to claiming that $1,000 back from the ATO. Over a year, these missed credits can easily add up to thousands of dollars in lost cash.
To make sure this doesn't happen to you:
- Keep every single tax invoice for business buys over $82.50. No exceptions.
- Use accounting software to snap a photo and digitally file your receipts.
- Reconcile your accounts regularly—weekly is ideal—to make sure nothing slips through the cracks.
Staying on top of your bookkeeping isn't just "good practice"; it's a fundamental financial strategy. Meticulous records ensure you claim every single credit you're entitled to, which directly pumps up your cash flow and profitability.
Understanding the Consequences of Non-Compliance
The ATO takes GST compliance very seriously. The penalties for getting it wrong aren't a slap on the wrist; they can be severe enough to cripple a small business. Failing to lodge your Business Activity Statement (BAS) on time or pay what you owe will attract significant penalties, and fast.
At Australia Wide Tax Solutions, we specialise in BAS preparation and lodgement for small businesses. Our job is to make sure you claim every possible input tax credit and steer clear of penalties that can sting up to 200% of the unpaid GST. Don't let overdue BAS pile up. Our team is here to make compliance a breeze. You can get a better sense of the landscape by checking out these insights on Australian GST rules.
Honestly, just staying organised and lodging on time is the simplest way to avoid these expensive and stressful dramas. Pop calendar reminders in your phone for BAS due dates and shunt the GST you collect into a separate bank account. These two small habits can save you a world of trouble down the line.
Your GST Registration Questions Answered
Even after you’ve gone through the motions of registering, a few tricky questions always seem to pop up. These are the details that can trip up even savvy business owners, so let’s get them sorted so you can move forward with confidence.
Getting these specifics right is every bit as important as lodging the initial application.
Can I Backdate My GST Registration?
Yes, you can. In fact, sometimes you have to. This is a classic scenario for businesses that suddenly realise they crossed the $75,000 turnover threshold in a previous quarter without even noticing. It happens more often than you'd think.
When you backdate your registration, you’re officially telling the Australian Taxation Office (ATO) that your GST obligations started on that earlier date. Just be ready for what comes next. It means you’ll need to go back and lodge any overdue Business Activity Statements (BAS) and pay the GST you should have collected for that entire period.
Picking the right date to backdate to is critical. Go back too far, and you create a mountain of unnecessary paperwork. Don't go back far enough, and you risk penalties. If you're even slightly unsure, getting advice from a tax professional is a smart move that can save you a lot of headaches later on.
Cash vs. Accrual GST Accounting
This is one of the biggest decisions you’ll make during registration, and it all boils down to timing. Your choice here has a direct and immediate impact on your business's cash flow.
Here’s the simple breakdown:
- Cash Basis: You only account for GST when money actually moves. You report GST on a sale once the customer has paid you, and you claim GST credits only after you’ve paid a supplier.
- Accrual Basis: You account for GST from the moment an invoice is issued or received, regardless of whether any money has changed hands.
For most small businesses, the cash basis is a no-brainer. It gives you a much clearer picture of the actual cash in your bank account, preventing that painful situation where you owe the ATO GST for an invoice your client hasn't even paid yet.
What Are the GST Rules for Overseas Customers?
This is a huge one for online service providers, consultants, and e-commerce stores. What happens when your clients are scattered all over the globe?
Generally, sales made to customers outside of Australia are considered 'GST-free' exports. That’s the good news—it means you don't add the 10% GST to these sales.
However—and this is the important part—the income you earn from those international sales still counts towards your annual turnover when calculating the registration threshold.
So, if your combined Australian and overseas sales push you over the $75,000 mark, you must register for GST. The silver lining? Once you're registered, you can start claiming back the GST credits on all the local business expenses you incurred to generate those international sales.
Navigating the complexities of backdating, accounting methods, and international sales can be challenging. The team at Australia Wide Tax Solutions provides expert guidance to ensure your GST registration is handled correctly from the start, protecting your business and maximising your financial position. Learn more at https://www.awts.net.au.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
So, when do you actually have to register for GST? Let's cut through the jargon.
- The 21-Day Countdown After You Hit the Threshold
- When the $75k Threshold Does Not Apply
- Voluntary GST Registration: Is It Right for You?
- How to Get Your GST Registration Sorted
- Life After Registration: Your Ongoing Responsibilities
The magic number you need to remember is $75,000. If your business's GST turnover hits this amount—or you expect it to—within any 12-month period, it’s time to register.
Crucially, this isn't about your annual profit. It’s the total sales your business makes before you subtract any expenses.
Decoding The GST Registration Threshold
The $75,000 GST turnover threshold is the key trigger. Think of it less like a fixed finish line at the end of the financial year and more like a moving window that’s always looking at your revenue.
This rule has been a cornerstone of Australian business tax since GST was introduced way back in 2000. It applies to any rolling 12-month period, which means you need to look at both your sales from the last 12 months and what you reasonably expect to make in the next 12 months.
Your Business Revenue Radar
Imagine your business has a 'revenue radar' constantly scanning your income. This radar looks backwards at the last 12 months of sales and forwards at your projected income for the upcoming year.
The second that radar shows your turnover hitting (or being very likely to hit) $75,000, your obligation to register is triggered. This proactive mindset is what keeps you off the ATO's naughty list and prevents nasty surprises down the track.
Of course, for your radar to work, you need a solid grip on your small business bookkeeping basics. Without clean records, you’re flying blind.
What Counts as GST Turnover?
This is where people often get tripped up. What exactly does the ATO include in "GST turnover"?
It’s your gross business income, which is a lot more than just the cash from your main product or service. It generally includes:
- Total income from the sales of your goods or services.
- The value of any goods you take from the business for your own personal use.
- Income from selling business assets, like that old office printer or company ute.
However, some things are left out. You don't need to count sales that aren't for payment, aren't connected to your business activities (like a personal hobby), or involve selling your entire business as a going concern.
It’s also vital to separate your genuine business activities from personal projects. If you're unsure where the line is, our guide on https://awts.net.au/blog/is-it-a-business-or-a-hobby/ can help clear things up.
The most common mistake business owners make is forgetting that GST turnover is a rolling measure. A quiet January doesn't reset the clock if the previous eleven months were strong. You must always be looking at the bigger picture.
This flowchart gives you a simple visual for making the call.
As the infographic shows, it’s a straightforward rule: if your turnover is over the threshold, registration isn’t optional—it’s mandatory.
Calculating Your GST Turnover: What to Include and Exclude
To make it even clearer, here’s a quick reference table to help you figure out what counts towards that $75,000 figure.
| Revenue Type | Include in GST Turnover? | Example |
|---|---|---|
| Sales of Goods & Services | Yes | A bakery selling $80,000 worth of cakes and bread in a year. |
| Export Sales | No | An artist selling paintings to a gallery in New York. |
| Sales of Business Assets | Yes | A courier selling their old delivery van for $10,000. |
| Input-Taxed Sales | No | A landlord receiving residential rent (this is financial supply). |
| Personal Use of Stock | Yes | A cafe owner taking home $100 worth of coffee beans each month. |
| Sale of a Business | No | Selling your entire business as a 'going concern' to a new owner. |
Keeping this table in mind will help you stay on top of your numbers and avoid accidentally crossing the threshold without realising it.
The 21-Day Countdown After You Hit the Threshold
Knowing your turnover is one thing; acting on it is the real test. The moment your business's 'revenue radar' pings to confirm you've crossed the $75,000 threshold—or you can see it's about to happen—a critical timer starts. The Australian Taxation Office (ATO) gives you exactly 21 days to get registered for GST.
Make no mistake, this isn't a friendly suggestion. It’s a hard legal deadline. That 21-day window kicks off the second your GST turnover officially passes the threshold, and ignoring it can lead to some serious financial headaches. We’re talking back-dated GST liabilities and ATO penalties that can chew a hole straight through your profits.
A Real-World Scenario
Let's put this into perspective. Imagine you're a freelance marketing consultant. For months, things have been ticking along nicely at around $6,000 per month. Then, a huge opportunity lands in your lap: two big retainer clients sign on in the same month. Suddenly, your projected annual turnover skyrockets to well over $80,000.
Your 21-day countdown starts from the day you sign those contracts—the point where you can reasonably expect to exceed the threshold. If you put it off and wait a couple of months to register, the ATO will simply backdate your registration to when you should have done it.
This is where the pain starts. It means you owe GST on every single taxable invoice you've sent since that backdated registration date, even if you never actually charged your clients for it. Trying to circle back to a client weeks later to ask for an extra 10% is an awkward, unprofessional conversation nobody wants to have.
The biggest risk of registering late is having to pay the GST out of your own pocket. For a business running on tight margins, an unexpected tax bill for 1/11th of two months' revenue can cause a serious cash flow crisis.
Proactive Strategies to Stay Ahead
Instead of letting the threshold sneak up on you, get out in front of it. Modern accounting software is your best friend here. You can set up custom reports and alerts that act as an early warning system, keeping a close eye on your rolling 12-month turnover.
Here are a few simple, actionable steps to avoid a last-minute scramble:
- Set Revenue Alerts: Jump into your accounting software (Xero or MYOB, for example) and configure an email notification to ping you when your turnover hits a certain point, say, $65,000.
- Monthly Check-ins: Carve out just 15 minutes at the start of each month to review your turnover for the previous 12 months. It's a simple habit that keeps you fully informed and in control.
- Forecast Your Pipeline: If you have a solid sales pipeline with several large projects on the horizon, don't ignore it. Factor this projected income into your calculations to see what's coming.
By understanding the deadline and actively monitoring your revenue, you can turn a potential compliance disaster into a straightforward admin task. You’ll know exactly when the time is right to register for GST and can manage your obligations with complete confidence.
When the $75k Threshold Does Not Apply
While the $75,000 turnover rule is a reliable guide for most businesses, it’s definitely not a one-size-fits-all situation. Certain industries operate under a completely different set of rules, and assuming the standard threshold applies can land you in hot water with the Australian Taxation Office (ATO).
Understanding these exceptions is absolutely critical if you operate in one of these specific sectors. For these businesses, the question of when to register for GST has a completely different answer—often requiring registration from the very first dollar earned.
Rules for Taxi and Ride-Sourcing Services
If your business involves providing taxi, limousine, or ride-sourcing services, the GST rules are strict and immediate. The $75,000 threshold simply does not apply to you. Full stop.
You must register for GST from the moment you start your business, no matter how much you expect to earn. This means if you sign up to drive for a ride-sourcing platform like Uber or DiDi and complete your very first trip, you are legally required to be registered for GST.
For taxi and ride-sourcing drivers, GST registration is not a milestone to be reached; it is a Day One requirement. Failing to register immediately means you are operating outside of tax law from your very first fare.
This special rule exists to ensure a level playing field in the passenger transport industry. You'll also need to issue proper tax invoices and start lodging Business Activity Statements (BAS) to report your GST obligations right away.
Special Threshold for Non-Profit Organisations
Non-profit organisations also play by a different set of rules, but in their case, the threshold is higher, offering a bit more breathing room.
A non-profit is only required to register for GST if its annual turnover hits $150,000 or more. That’s double the standard threshold for for-profit businesses. This higher limit acknowledges the unique community focus of these entities and helps reduce their administrative load.
This higher threshold applies to specific types of organisations:
- Charitable Institutions: This includes any organisation endorsed by the ATO as a charity.
- Trustee of a Charitable Fund: This applies to funds set up purely for charitable purposes.
- Gift Deductible Entities: Any organisation that can receive tax-deductible donations.
- Government Schools: Public primary and secondary schools also fall under this category.
If your non-profit’s turnover stays below $150,000, you don't have to register. However, you can still choose to register voluntarily if it makes financial sense for your organisation—for instance, to claim back the GST credits on significant purchases or expenses.
Voluntary GST Registration: Is It Right for You?
Just because your business turnover is safely below the $75,000 threshold doesn’t mean the GST system is off-limits. For many ambitious businesses, choosing to register for GST voluntarily is a powerful strategic move, not just another tax chore.
Making this call is about more than just compliance; it can seriously impact your cash flow and how other businesses see you in the market. It’s a trade-off, weighing immediate financial perks against new administrative duties. Thinking about this before you’re legally required to is a sign you’re on top of your finances.
The Power of Claiming GST Credits
The single biggest drawcard for voluntary registration is the ability to claim back the GST you pay on business expenses. These are known as GST credits or input tax credits.
Without being registered, that 10% GST you pay on supplies, equipment, and services is just a dead cost that eats into your profit. Once you register, that 10% becomes reclaimable from the ATO.
Let’s say you’re launching a new cafe. The initial fit-out is a huge expense, with big-ticket items like a coffee machine, fridges, and furniture.
- Commercial Espresso Machine: $11,000 (which includes $1,000 in GST)
- Refrigeration Units: $8,800 (including $800 in GST)
- Cafe Furniture & Decor: $5,500 (including $500 in GST)
In this scenario, you've shelled out $2,300 just on the GST component of these essential items. By registering for GST voluntarily from day one, you can claim this entire amount back on your first Business Activity Statement (BAS). That’s a massive cash injection right when a new business needs it the most.
Weighing the Pros and Cons
Voluntary registration isn’t a one-way street. While claiming back GST is a huge win, it comes with extra responsibilities. The main hurdle is the admin workload of tracking GST, reporting it accurately, and lodging your BAS on time. You’ll also need to add 10% GST to your own prices, which could make you less competitive if your customers are mainly individuals who can't claim it back.
Choosing to register for GST is about more than just tax; it’s about positioning your business for growth. It signals to suppliers and larger clients that you're established and operate within the formal tax system, which can seriously boost your credibility.
To help you figure out if it's the right move for you, here’s a straightforward breakdown of the pros and cons.
Voluntary GST Registration Pros vs Cons
| Consideration | Pros (Advantages of Registering) | Cons (Disadvantages of Registering) |
|---|---|---|
| Business Expenses | You can claim back the GST paid on your purchases and operating costs, improving cash flow. | You must track all GST paid and collected, increasing your bookkeeping workload. |
| Pricing & Competition | May not impact B2B sales, as your business clients can claim back the GST you charge. | You must add 10% GST to your prices, potentially making you more expensive for retail customers. |
| Administration | Encourages better financial record-keeping habits from the start. | You are legally required to lodge a Business Activity Statement (BAS) regularly (monthly or quarterly). |
| Business Credibility | An ABN registered for GST can make your business appear more established and professional to larger clients. | Missing BAS lodgement deadlines can result in penalties and interest charges from the ATO. |
Ultimately, the right choice comes down to your specific business model, your customer base, and your plans for the future. If you’re a B2B business or have high startup costs, the benefits of registering early often far outweigh the administrative headaches.
How to Get Your GST Registration Sorted
Alright, so you’ve worked out that you need to register for GST. The next part is mostly admin—think of it as officially putting your hand up and telling the Australian Taxation Office (ATO) that your business is now in the GST club.
To make this painless, it’s a smart move to get all your business details lined up before you start. A bit of prep work here saves a lot of headaches and back-and-forth later.
What You'll Need to Have Ready
Before you jump into the application, pull together these key details. It'll make the whole thing much smoother.
- Your Australian Business Number (ABN): This is non-negotiable. If you don't have an ABN yet, you'll need to sort that out first. Our guide on how to register a business in Australia walks you through it.
- Proof of Identity: You’ll need some basic details to confirm you are who you say you are.
- Business Contact Details: This means your registered business address, phone number, and a good email contact.
- What Your Business Does: Just a straightforward description of your main business activities.
- Projected GST Turnover: Your best estimate of the business's annual income.
- The Start Date: You need to pick the date your GST registration officially kicks in. The good news is this can be backdated if you’ve already shot past the threshold.
The Different Ways to Register
Once you have your info packet ready, you’ve got a few different paths you can take to get registered. Each one is designed for different needs, so you can pick the one that feels right for you.
- Do It Yourself Online: The quickest and most popular route is using the ATO’s online services. You'll use your myGovID linked to the Relationship Authorisation Manager (RAM) to get into the Business Registration Service. It’s a self-service portal that guides you through each step.
- Get a Pro to Handle It: If you're feeling a bit lost or just want to be 100% sure it's done right, using a registered tax or BAS agent is your best bet. They’ll take care of the whole process for you, giving you total peace of mind that it's all correct.
- Give Them a Call: You can also register by phoning the ATO. This is a solid option if you have some specific questions and would rather talk it through with an actual person.
Choosing how to register really comes down to convenience versus confidence. While going online is fast, having a tax professional handle it takes all the guesswork out of the equation. They make sure you’re set up correctly from day one, which can save you from a world of compliance pain down the track.
Life After Registration: Your Ongoing Responsibilities
Flipping the switch to 'GST registered' isn't the finish line; it’s really just the beginning. It introduces a new rhythm into your business operations, where your main job is to balance the GST you collect on sales against the GST you pay on your business buys.
This whole process is managed through your Business Activity Statement (BAS). The simplest way to think about the BAS is as your regular financial check-in with the Australian Taxation Office (ATO). It’s where you report the GST you’ve collected, claim back GST credits on your expenses, and then settle the difference. Getting your head around how to prepare a business activity statement is a core skill for any registered business owner in Australia.
Your Reporting Cycle
Once you're in the system, the ATO will pop you onto a reporting cycle, which just dictates how often you need to lodge your BAS. For most new businesses, this will be a quarterly schedule.
- Quarterly: This is the default setting for most small businesses. You'll lodge your BAS every three months, keeping your compliance manageable without being overwhelming.
- Monthly: If your business has a GST turnover of $20 million or more, the ATO will generally require you to report on a monthly basis.
- Annually: This is much less common and is typically reserved for very small businesses that have registered voluntarily and have a low turnover.
The key here is consistency. Lodging and paying on time, every single time, is non-negotiable. Missing those deadlines can lead to penalties and interest charges that can snowball surprisingly quickly.
A crucial point to remember: once you're registered, you have to lodge a BAS for every single reporting period. This applies even if you had zero business activity. A 'nil' BAS still needs to be filed to let the ATO know what’s going on.
Invoicing and Record Keeping
Your invoicing process will need an immediate upgrade. Every invoice you send to another business must now be a proper tax invoice. This isn't just a suggestion; it's a legal requirement. It means including specific details like your ABN, clearly stating "Tax Invoice," and showing the exact amount of GST charged.
Finally, meticulous record-keeping becomes your new best friend. The law mandates that you hold onto all business records related to your tax obligations for at least five years. This includes every tax invoice and receipt. Think of this documentation as your proof; it’s what you’ll rely on if the ATO ever has questions about your BAS lodgements. Building these habits from day one makes compliance a simple, stress-free part of your business routine.
Common Questions About GST Registration
Even with the clearest roadmap, you're bound to have questions when figuring out your GST obligations. This final section tackles some of the most common queries we hear from business owners, helping you tie up any loose ends.
What Happens if I Register Late?
This is a scenario you want to avoid. If you register for GST late, the Australian Taxation Office (ATO) will backdate your registration to the day you were first required to do so.
What does that mean for you? You’ll be liable for GST on every taxable sale you've made since that backdated start date, even if you never included GST in your prices. On top of that, you could be hit with penalties and interest charges for the delay. The best move is to act fast and get a tax professional involved to help manage the fallout and minimise any financial pain.
Can I Cancel My GST Registration?
Yes, you can, but only in specific situations. Usually, this happens if your business has shut down, been sold, or if your GST turnover has dropped below the $75,000 threshold and you expect it to stay there.
To cancel because of low turnover, you generally need to have been registered for at least 12 months. Be aware that you'll have to lodge a final BAS, and you might have to repay any GST credits you claimed on business assets you still own.
Should I Have a Separate Bank Account for GST?
While it’s not legally required, it’s one of the smartest financial habits you can build.
Opening a separate bank account just for the GST you collect is a game-changer. Think of it as parking the ATO's money somewhere safe. It prevents that money from being accidentally swallowed up by business expenses, making sure it's ready to go when your BAS payment is due.
Putting the GST portion of every sale into a dedicated account makes managing your tax obligations so much less stressful. It stops cash flow surprises dead in their tracks.
Navigating GST registration and staying compliant can feel like a minefield, but you don't have to walk it alone. The team at Australia Wide Tax Solutions offers expert accounting and BAS services to make sure you meet every obligation, accurately and on time. Let us handle the details so you can get back to what you do best: growing your business with complete confidence. https://www.awts.net.au
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
Getting your Business Activity Statement (BAS) lodgement right is a non-negotiable part of running a business in Australia. It’s the main way you report and pay critical taxes like GST and PAYG withholding to the Australian Taxation Office (ATO). Nail this process, and you’re well on your way to solid financial health and compliance.
- Getting a Handle on Your BAS Lodgement Obligations
- How to Prepare for a Smooth BAS Lodgement
- Choosing The Best BAS Lodgement Method For Your Business
- Know Your BAS Lodgement Deadlines and Payment Options
- Common BAS Mistakes and How to Avoid Them
Getting a Handle on Your BAS Lodgement Obligations
The Business Activity Statement isn't just another form to fill out. Think of it as a summary of your tax life for a given period. If your business is registered for Goods and Services Tax (GST)—which is mandatory for most businesses with a GST turnover of $75,000 or more per year (or $150,000 for non-profits)—then lodging a BAS is a must-do.
Once you're registered for GST, the ATO will automatically start sending you a BAS when it's time to lodge. The beauty of the BAS is that it bundles several tax obligations into one report, which definitely simplifies things. If you're new to this, we’ve got a great primer that breaks down the basics in our article, what is BAS in accounting.
What Does a BAS Actually Cover?
When you open up your BAS, you’ll see sections for different taxes, depending on what your business does. The usual suspects are:
- Goods and Services Tax (GST): This is the classic balancing act. You calculate the GST you’ve collected from customers and subtract the GST credits you can claim on your business expenses. The difference is what you owe the ATO (or what they owe you).
- Pay As You Go (PAYG) Withholding: Got employees? This is where you report the income tax you’ve held back from their pay packets. That money doesn't belong to you; you’re just holding it for the ATO.
- Pay As You Go (PAYG) Instalments: This is a smart system to help you pre-pay your business's income tax throughout the year. It stops you from getting hit with a massive, and often unexpected, tax bill when you lodge your annual return.
To get this all done without a headache, you need a solid system for collecting your financial data. A good tax information form can be a great start to make sure nothing gets missed.
Figuring Out Your Reporting Cycle
How often you need to lodge your BAS comes down to your GST turnover. The ATO will assign you a reporting cycle, and this sets the rhythm for your bookkeeping and lodgement deadlines.
For the vast majority of small and medium businesses in Australia, quarterly reporting is the standard. It hits the sweet spot—frequent enough to keep on top of your taxes, but not so often that it becomes a massive admin burden.
Here are the three main cycles you might be on:
- Quarterly: This is the most common setup, for businesses with a GST turnover under $20 million. It means you'll be lodging four times a year.
- Monthly: If your GST turnover hits $20 million or more, the ATO will put you on a monthly cycle. Some smaller businesses also opt for this to keep a tighter rein on their cash flow.
- Annually: This is an option for very small businesses turning over less than $75,000 who have voluntarily registered for GST. It's the simplest, but least common, cycle.
Knowing your specific cycle is the first step to a stress-free BAS process. It dictates your deadlines and helps you build a bookkeeping routine that ensures you’re always prepared to lodge accurately and on time. No last-minute scrambles.
How to Prepare for a Smooth BAS Lodgement
An accurate Business Activity Statement lodgement starts long before you even think about logging into the ATO portal. Real success is built on a solid foundation of organised, up-to-date records. Without them, you’re basically flying blind, risking simple errors that could easily spiral into audits, penalties, or missed GST credit claims.
Think of your BAS prep as gathering all the ingredients before you start cooking. Each bit of financial data is a crucial component, and having everything ready to go makes the whole process faster and way less stressful. Let’s walk through exactly what you need to have on hand.
This quick graphic breaks down the key stages of your BAS obligations, from checking your GST threshold right through to lodging the final statement.
It’s a simple reminder of the journey, making it clear where preparation fits into the bigger compliance picture.
Compiling Your Sales and Income Records
First up, you need a complete picture of every dollar your business brought in during the reporting period. This isn't just about a grand total; it’s about correctly classifying each transaction so you can calculate the right amount of GST.
You'll need to pull together:
- Tax invoices you've issued: These are the bread and butter of your sales records. Make sure they clearly show the total price, the GST amount, and your ABN.
- Bank statements: Use these to cross-reference every deposit with your sales invoices. It's the best way to make sure nothing has slipped through the cracks. Keep an eye out for any odd deposits that might be business income you forgot to invoice.
- Cash sales records: If you take cash, your daily till reconciliations or cash sales summaries are absolutely vital. These need to be meticulous, as they're often the first thing the ATO looks at.
A classic mistake we see all the time is failing to separate GST-free sales from taxable ones. For instance, if you run a small grocery store, sales of basic foods like bread and milk are GST-free, but soft drinks are taxable. Getting this wrong can lead to you overpaying or underpaying GST.
Gathering Your Expense and Purchase Documents
This is where you get your money back. It's your chance to claim back the GST you’ve paid on business purchases. Missing out on these GST credits literally means you're leaving money on the table for the ATO. Every legitimate dollar you claim reduces your final BAS bill.
To make sure you're claiming everything you're entitled to, you'll need:
- Supplier tax invoices: For any purchase over $82.50 (including GST), you must have a valid tax invoice to claim the GST credit. No invoice, no credit.
- Receipts for smaller purchases: Don't throw them out! Keep all receipts for smaller business-related expenses, as they add up.
- Bank and credit card statements: Go through these line by line to spot all business-related debits and match them to an invoice or receipt.
A big part of BAS prep involves pulling financial data from all over the place. To save yourself a massive headache and reduce errors, it's worth looking at ways to automate processes like how to extract invoice data efficiently.
Assembling Payroll Information
If you have a team, your BAS also involves reporting on Pay As You Go (PAYG) withholding. This is the tax you’ve held back from your staff's wages, which you then need to pass on to the tax office.
Key Takeaway: Your payroll records must perfectly match the figures you report on your BAS. The ATO’s data-matching systems are incredibly sophisticated these days and will flag discrepancies between your BAS and your Single Touch Payroll (STP) reports almost instantly.
Before you even start your BAS, have your payroll summary report for the period ready. This report needs to clearly show the total gross wages paid and the total tax withheld. Reconciling this figure against your bank records for wage payments is a final check you absolutely can't skip. For a deeper dive into organising your documents, check out our comprehensive BAS preparation checklist.
By methodically gathering and organising these three sets of documents—income, expenses, and payroll—you're creating a complete and defensible snapshot of your business finances. This doesn't just guarantee an accurate business activity statement lodgement; it turns a daunting chore into a routine business health check.
Choosing The Best BAS Lodgement Method For Your Business
Once your books are in order, the next big decision is how you're actually going to get your BAS to the ATO. This isn't just about clicking a button; your choice of lodgement method can make a real difference to your accuracy, how much time you spend on it, and even your due dates.
While there are a few ways to lodge your business activity statement, the overwhelming shift is towards digital. Modern online methods are simply faster, more secure, and far less likely to cause the kinds of human errors that were common with old-school paper forms.
H3: Lodging Directly With ATO Online Services
For business owners who like to keep things hands-on, lodging directly through the ATO’s own digital platforms is a solid option. It puts you in the driver's seat, giving you complete control over the entire submission process.
You have two main portals for this:
- Online services for business: This is the ATO's standard, secure platform built for businesses. It's the go-to for most companies, trusts, and partnerships managing their own tax affairs.
- myGov: If you're a sole trader, you can link your ABN to your personal myGov account and handle your BAS lodgement from there.
The online process is generally pretty user-friendly. The forms come pre-filled with your business details, and the system has built-in checks that often catch simple mistakes before you hit submit. If you're after a detailed walkthrough, our guide on how to lodge your BAS online breaks it down step-by-step.
H3: Partnering With A Registered BAS or Tax Agent
Let's be honest, for many business owners, handing off BAS lodgement to a professional is the smartest thing they can do. A registered BAS or tax agent does more than just fill out a form; they provide a full service that ensures accuracy, maximises your claims, and keeps you compliant with tax laws that seem to change every other week.
This path is perfect if you:
- Are simply too busy running your business to get bogged down in bookkeeping.
- Aren't 100% confident in calculating GST, PAYG, and other complex figures.
- Want the peace of mind that comes from having an expert double-check everything.
One of the biggest perks of using an agent is getting access to extended lodgement and payment deadlines. This isn't a myth—it's a real concession from the ATO that can give you critical breathing room during hectic times. A good agent will review your records, spot potential red flags, and make sure every last GST credit you're entitled to is claimed.
H3: The Traditional Paper Lodgement Option
While it still technically exists, lodging a paper BAS is quickly becoming a thing of the past. The ATO has been pushing businesses towards digital for years, and now, most are required to lodge electronically.
Paper lodgement is slow, you get no instant confirmation that it's been received, and it's wide open to manual errors—both on your end and when someone at the ATO has to process it. Unless you have a specific and rare exemption, you're far better off choosing one of the digital methods. It ensures your business activity statement lodgement is handled smoothly, efficiently, and without any unnecessary headaches.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
Comparison of BAS Lodgement Methods
Deciding how to lodge can feel like a big choice. To make it easier, we've broken down the key differences between the three main methods. This should help you see at a glance which approach best fits your business needs, your confidence level with tax matters, and how much time you have to spare.
| Feature | ATO Online Services | Registered BAS/Tax Agent | Paper Lodgement |
|---|---|---|---|
| Control | Full control over the entire process. | You provide records, the agent handles the rest. | Full manual control, but with significant risks. |
| Accuracy | Relies on your own knowledge. Built-in checks help. | High. Professional review minimises errors and ensures claims. | Low. Highly prone to manual calculation and data entry errors. |
| Time Commitment | Moderate. You need to do the calculations and lodgement. | Low. Outsource the entire process. | High. Requires manual form completion and postage. |
| Deadlines | Standard ATO deadlines apply. | Access to extended lodgement and payment due dates. | Standard, shorter deadlines apply. No extensions. |
| Support | General ATO support channels available. | Personalised, expert advice and support. | Limited to general ATO phone lines. |
| Cost | Free to use the ATO portals. | Professional fees apply. | Postage costs, but the main cost is your time and error risk. |
| Best For | DIY business owners confident with their bookkeeping. | Business owners who value time, accuracy, and peace of mind. | Businesses with a specific ATO exemption (very rare). |
Ultimately, while lodging yourself online is a viable option for those with the time and confidence, partnering with a registered agent almost always provides the best outcome. The expertise, extended deadlines, and sheer peace of mind are well worth the investment, letting you focus on what you do best: running your business.
Know Your BAS Lodgement Deadlines and Payment Options
Staying on top of your Business Activity Statement deadlines is non-negotiable for tax compliance. Let's be blunt: missing these dates isn’t a minor slip-up. The Australian Taxation Office (ATO) can hit you with penalties and interest charges, putting a completely unnecessary strain on your cash flow.
The first step to staying out of trouble is understanding the rhythm of your BAS cycle. Your due dates hinge entirely on your reporting frequency—whether you lodge monthly, quarterly, or annually.
Mapping Out Your Lodgement Calendar
For most small and medium-sized businesses, the quarterly cycle is the sweet spot. It strikes a good balance between staying on top of your tax obligations and not getting bogged down in administrative work every single month.
Quarterly lodgement is still the standard for a reason. Over 70% of small businesses in Australia stick to this frequency. This schedule lines up perfectly with the ATO's standard due dates of 28 October, 28 February, 28 April, and 28 July. You can find out more about the ATO's agent lodgement program on their official site.
Let's break down the key deadlines:
- Quarterly Lodgers: If you're lodging yourself, your deadline is the 28th day of the month after the quarter ends.
- Monthly Lodgers: For businesses with a higher turnover, the BAS is due on the 21st of the following month. For example, your July BAS is due by 21 August.
- Annual Lodgers: This is less common, but if you're eligible, your due date is typically 31 October.
One of the biggest perks of working with a registered BAS or tax agent is getting access to their extended lodgement program. This can give you an extra four weeks for most quarterly deadlines—a priceless buffer during hectic times.
Making Your BAS Payment
Once you've lodged your BAS and know what you owe, the ATO offers a few straightforward ways to settle up. The key is to pick a method that works for your business and guarantees the payment lands on time.
The most common payment methods we see are:
- BPAY: You can pay directly from your bank account using the unique Biller Code and reference number found on your BAS.
- Credit or Debit Card: The ATO's online payment portal lets you use a card, but keep in mind a processing fee might apply.
- Direct Debit: You can set up a one-off or recurring direct debit through ATO online services. This is a great set-and-forget option to avoid missed payments.
Always, always double-check the payment reference number. A simple typo can send your payment into limbo, causing delays and a massive administrative headache to sort out.
Pro Tip: Set up a separate business bank account just for GST and PAYG withholding. Every time you get paid or run payroll, transfer the tax portion into this account. When your BAS is due, the money is already sitting there, quarantined from your daily operational cash flow.
What to Do If You Can't Lodge or Pay on Time
Life happens. Sometimes unexpected issues make it impossible to meet your tax obligations on time.
If you find yourself in this situation, the absolute worst thing you can do is bury your head in the sand. The ATO is often willing to help, but only if you're proactive and communicate with them.
As soon as you know you're going to miss a deadline, contact the ATO or your tax agent. You might be able to arrange a lodgement deferral or a payment plan that fits your situation. This simple act of communication shows you're taking your obligations seriously and can help you avoid or reduce penalties.
Common BAS Mistakes and How to Avoid Them
Even with the best intentions, it’s frighteningly easy to make a slip-up during your business activity statement lodgement. These aren't just minor admin headaches; they can lead to ATO scrutiny, unexpected tax bills, and hours of wasted time trying to fix things.
Understanding where business owners commonly go wrong is the first step to getting your lodgement right, every single time.
From simple calculation errors to claiming credits you’re not entitled to, we’ve seen it all. Getting these details right not only keeps you compliant but also protects your cash flow from completely avoidable penalties.
Miscalculating GST and Claiming Invalid Credits
This is, without a doubt, the most frequent pitfall we see. A simple maths error or a misunderstanding of GST law can create significant problems down the track. One of the classic mistakes is claiming GST credits on purchases that don't actually include GST in the first place.
Here are a few real-world examples that trip people up constantly:
- Bank Fees: Most standard bank fees, like your monthly account-keeping charge, are input-taxed. This means they don't include GST, so you can't claim a credit on them.
- GST-Free Purchases: Did you buy milk and bread for the office kitchen? Most basic food items are GST-free, which means there’s no credit to claim back.
- Supplier ABN: If you get an invoice from a contractor or supplier who isn't registered for GST, there will be no GST component to claim, even if it's a legitimate business expense. Always check the invoice.
Another area of confusion is client entertainment. Taking a client out for a meal is generally not a deductible expense for income tax, and as a result, you can't claim the GST credits on it either. It’s a small detail, but it’s one the ATO’s systems are specifically designed to flag.
Missing Lodgement and Payment Deadlines
Failing to lodge your BAS on time is a mistake with immediate and painful financial consequences. The ATO's penalty system is automated and unforgiving, applying charges even if you don't actually owe any tax for that period.
Failure to lodge on time results in penalties that escalate quickly. For a small business, this starts at $313 per overdue statement and can climb to a maximum of $1,565 per statement. On top of that, any late payments attract the General Interest Charge (GIC), which compounds daily on the unpaid amount. You can see a full breakdown of these penalties and important BAS due dates on CleanSlate.net.au.
The lesson here is crystal clear: even if you can't pay the amount owed, you must still lodge the BAS by the deadline. It's a far better strategy to lodge on time and then arrange a payment plan with the ATO than to simply ignore the due date.
Keeping Disorganised or Incomplete Records
At the end of the day, your BAS is only as accurate as the records you keep. Messy bookkeeping is the root cause of most lodgement errors, turning what should be a straightforward process into a stressful, time-sucking nightmare.
Disorganised records almost always lead to:
- Missing GST Credits: Lost receipts and unrecorded expenses mean you're literally giving money back to the ATO by not claiming legitimate credits.
- Under-reporting Sales: Forgetting to record cash sales or other miscellaneous income can result in you underpaying GST—a major red flag for auditors.
- Incorrect PAYG Withholding: If your payroll records don't perfectly align with what you report on your BAS, the ATO’s sophisticated data-matching systems will spot the discrepancy very quickly.
Using good accounting software and sticking to a consistent weekly bookkeeping routine are your two best defences against this.
A Final Review Checklist Before You Lodge
Before you hit that submit button, take ten minutes to run through this quick checklist. It’s a simple habit that can save you from a world of trouble.
- Reconcile Your Accounts: Are all bank accounts, credit cards, and clearing accounts fully reconciled for the period? No exceptions.
- Review GST Coding: Run a detailed GST report from your accounting software. Scan it for any large or unusual items and double-check that expenses have been correctly coded as either containing GST or being GST-free.
- Check Payroll Figures: Does the total gross wages and tax withheld on your BAS match your payroll summary report for the exact same period? They need to be identical.
- Confirm Your Details: A simple one, but crucial. Are your business name, ABN, and the reporting period correct on the form?
Performing these final checks ensures your business activity statement lodgement is clean, accurate, and ready for scrutiny.
Your Top Business Activity Statement Lodgement Questions
Even after you've got the prep work down and the due dates circled on the calendar, a few nagging questions about business activity statement lodgement always seem to crop up. Getting straight answers is the key to lodging with confidence and keeping the ATO happy.
Think of this as the final checklist—clearing up those last-minute uncertainties and "what if" scenarios that can throw you off your game.
What Should I Do If I Find a Mistake on a Lodged BAS?
Realising you've made a mistake on a BAS you've already sent off can be a heart-stopping moment, but don't panic. It's a common and fixable issue. The ATO has clear processes for corrections, and jumping on it quickly is always the best approach.
For small errors under a certain financial threshold, the ATO usually lets you make an adjustment on your next BAS. This is the simplest fix for minor GST or fuel tax credit mistakes, saving you from having to formally amend old paperwork.
But for bigger mistakes, or anything that relates to a previous financial year, you’ll need to lodge a revision of the original statement. You can do this yourself through the ATO's online services, or you can have your registered agent handle it for you. The sooner you correct it, the better—it shows good faith and helps minimise any potential interest or penalties.
Do I Still Need to Lodge a BAS with No Business Activity?
Yes. Absolutely. This is a non-negotiable rule that catches so many new business owners out. Even if you had zero sales, made zero purchases, and paid no wages for the entire reporting period, you are still legally required to lodge your BAS.
This is what’s known as lodging a 'nil' BAS.
Filing a nil BAS is how you officially report to the ATO that you've met your obligation for that period and that no activity took place. If you don't, you can still be hit with a Failure to Lodge (FTL) penalty, even when you owe no tax. The good news? Lodging a nil BAS is incredibly fast and can be done online in just a couple of minutes.
Is It Possible to Get an Extension on My BAS Due Date?
While you can't just decide to lodge late on your own terms, getting an official extension on your BAS due date is definitely possible in certain situations. They aren't handed out automatically, though—it all depends on your circumstances.
The easiest way to get more time is to use a registered tax or BAS agent. Agents have access to a special lodgement schedule for their clients, which typically adds an extra four weeks to most quarterly deadlines. This is one of the biggest perks of having a professional in your corner.
If you lodge yourself and get hit by something unexpected—like a serious illness, a natural disaster, or another major personal event—you can contact the ATO directly before the deadline to request a lodgement deferral.
Key Takeaway: Communication is everything. The ATO is far more likely to be accommodating if you reach out proactively to explain your situation rather than waiting for them to chase you for an overdue lodgement.
How Is GST Turnover Different from My Total Sales?
This is a critical distinction that directly impacts your tax obligations, and getting it wrong can cause major headaches. Your 'total business sales' is exactly what it sounds like—all the revenue your business has brought in. Your 'GST turnover', however, is a specific calculation the ATO uses for tax purposes.
Your GST turnover is your gross business income, but with a few key items excluded:
- Any GST you included in the price of your sales.
- Sales that aren't part of your main business activities.
- Input-taxed sales, like residential rent or financial supplies.
This is the figure that determines whether you need to register for GST (the threshold is $75,000) and how often you need to report. Always use the ATO's precise definition of GST turnover when making these decisions to ensure you stay compliant.
Navigating the world of BAS lodgement can feel complex, but you don't have to do it alone. The expert team at Australia Wide Tax Solutions is here to take the guesswork out of your tax obligations, ensuring your BAS is prepared accurately and lodged on time, every time.
Let us handle your BAS and tax needs so you can focus on what you do best.
So, you're ready to register your business in Australia. It's a massive step, but the paperwork can feel like a maze of acronyms and forms. Essentially, it boils down to choosing a business structure, getting an Australian Business Number (ABN), registering a name with ASIC if you need to, and sorting out your tax registrations like GST. Getting this right turns your idea into a real, legally recognised business ready to start trading.Your Starting Point for Business Registration in Australia
Launching a business is a huge milestone, but the registration process can seem overwhelming. I'm here to give you a clear roadmap, starting with the big decisions that will shape your entire venture. We'll look at why choosing the right business structure is so much more than just ticking a box and how getting your ABN is the key that unlocks your ability to operate legally. Instead of drowning you in jargon, this is your high-level overview of the journey ahead. You'll go from picking a unique business name to getting your head around your initial tax obligations. Think of this as the strategic briefing before we dive into the nitty-gritty steps that turn your business plan into a fully compliant reality.The Path to a Registered Business
You're about to join a pretty vibrant community. The Australian business scene is thriving, with 2,729,648 actively trading businesses on the books as of mid-2025. That number includes a net increase of 66,650 businesses in just one year, driven by a healthy 16.4% entry rate. Interestingly, companies saw the most significant growth at 4.7%, which shows a real trend towards people setting up more formal business structures right from the get-go. If you're a data nerd, you can dig deeper into these numbers on business entries and exits from the ABS. This infographic breaks down the core phases of the journey to help you picture the path forward.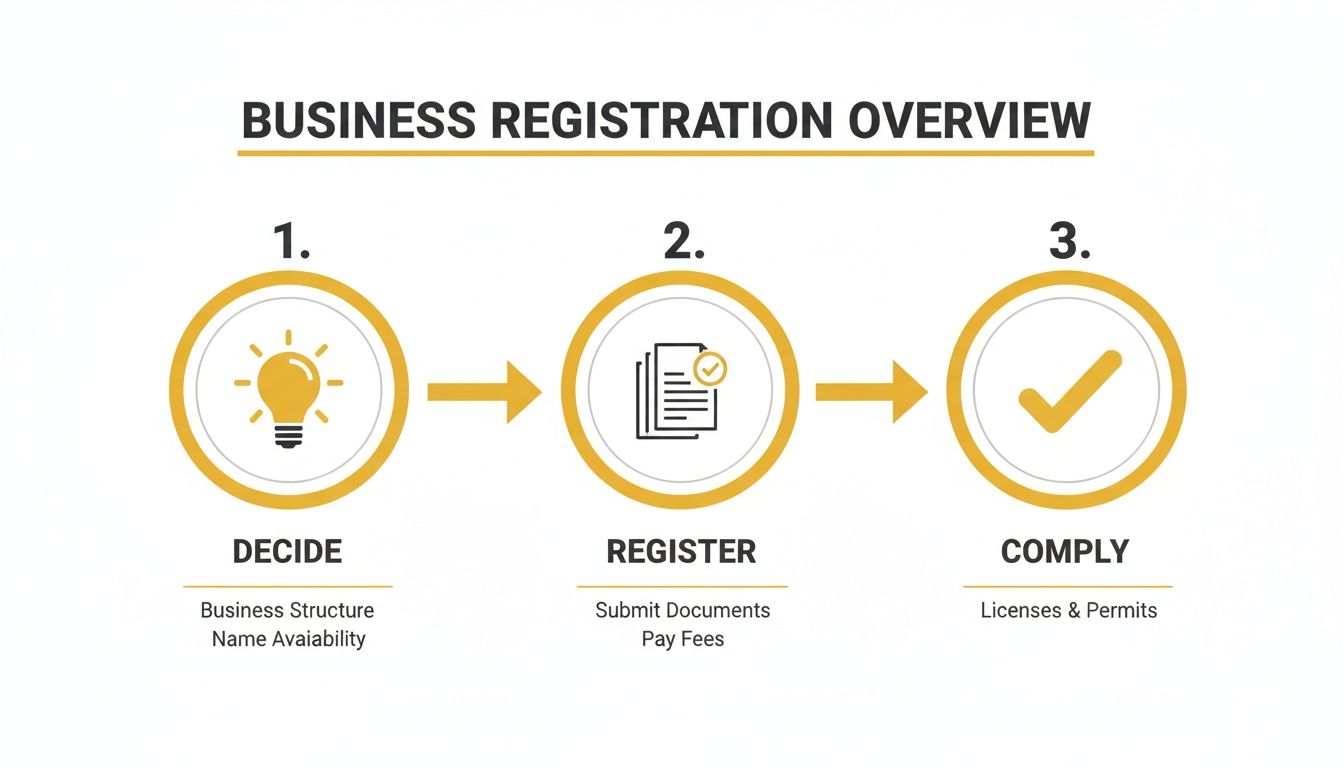
From my experience, the most successful business launches always start with a solid foundation. Getting these initial steps right—your structure, ABN, and name—prevents costly administrative headaches down the track and sets you up for sustainable growth.Let's start breaking these foundational pieces down into simple, manageable actions, beginning with the most critical decision you'll make.
Choosing the Right Business Structure
Deciding on your business structure is hands down one of the most critical calls you'll make when you first get your business off the ground in Australia. This isn't just about filling out forms; it fundamentally shapes your personal liability, how much tax you end up paying, and the sheer volume of admin work on your plate. Get this right from day one, and you’ll save yourself a world of headaches and costly restructuring dramas later on. Think of it this way: a freelance graphic designer just starting out will likely lean towards a sole trader structure. It’s simple, the setup costs are low, and it just makes sense when you're a one-person show. Legally, their personal and business finances are one and the same. While that's straightforward, it also means their personal assets—like their house or car—are on the line if the business gets into hot water with debt.Sole Trader Simplicity Versus Company Protection
As a sole trader, you are the business. You’ll use your personal Tax File Number (TFN) to lodge tax returns and you have total control. It's the most common structure for new ventures for a reason, with over 822,000 sole traders actively operating across Australia. But what if you're launching a tech startup and bringing in investors? Or a construction business where the risks are much higher? In those cases, a proprietary limited (Pty Ltd) company is a far better shield. This structure creates a completely separate legal entity, which protects your personal assets from business debts. This is the power of "limited liability." The company gets its own TFN, lodges its own tax returns, and any profits it makes belong to the company until they’re paid out to shareholders as dividends.The key takeaway is this: your choice of structure must align with both your current situation and your future growth plans. Don't just pick the easiest option without considering where you want to be in five years.
Understanding Partnerships and Trusts
Beyond those two common paths, you've got a couple of other options. A partnership is where two or more people (or entities) run a business together. They're fairly simple to set up, but the catch is that all partners are generally on the hook personally for business debts—including those racked up by another partner. Then there's the trust, which is a more complex setup. Here, a trustee (an individual or a company) holds assets for the benefit of others, known as beneficiaries. Trusts are fantastic for asset protection and offer great tax flexibility, which is why you often see them used for family businesses or investment portfolios. The trade-off? They come with higher setup and ongoing administration costs. The table below gives a quick snapshot of how these structures stack up against each other.Comparing Australian Business Structures at a Glance
| Feature | Sole Trader | Partnership | Company (Pty Ltd) | Trust |
|---|---|---|---|---|
| Legal Status | You and the business are one legal entity | Two or more partners; not a separate legal entity | A separate legal entity from its owners | Trustee holds assets for beneficiaries; not separate entity |
| Liability | Unlimited. Personal assets are at risk | Unlimited. Partners are jointly and severally liable | Limited. Personal assets are generally protected | Trustee liability may be limited; beneficiaries are protected |
| Tax | Taxed at individual marginal tax rates | Profits/losses distributed to partners and taxed individually | Taxed at the flat company tax rate (25% or 30%) | Income distributed to beneficiaries and taxed at their rates |
| Setup Cost | Very low (just ABN registration) | Low (partnership agreement is recommended) | Higher (ASIC registration fees apply) | Highest (requires a formal trust deed) |
Securing Your Australian Business Number (ABN)
Proving You're a Genuine Enterprise
One of the biggest hurdles that trips people up is proving they are actually 'carrying on an enterprise'. This is the Australian Taxation Office (ATO)'s way of separating a real business from a hobby or a passive investment. You have to show a clear plan and a genuine intention to make a profit. It’s the difference between selling a few old books from your shelf on eBay (a hobby) versus buying books specifically to resell online with a clear business plan and a separate bank account (an enterprise). To back up your application, you should be able to demonstrate that you’ve:- Made a conscious decision to start a business and have a plan for it.
- Taken real steps to get started, like buying assets, building a website, or printing business cards.
- Reasonably expect your activities to eventually turn a profit.
What to Prepare for Your Application
To make the application process as smooth as possible, it pays to have your documents ready to go. You won't get far without these key details. Make sure you have:- Your Tax File Number (TFN), plus the TFNs of any partners or directors.
- Proof of identity documents on hand.
- The details of your business structure (sole trader, company, etc.).
- A clear and specific description of your main business activities.
Pro Tip: When describing your business, be specific. Instead of putting "consulting," try something like "providing marketing strategy consulting for small retail businesses." This kind of clarity helps the ABR understand what you do and approve your application without a fuss.For a more detailed walkthrough, our guide to registering an Australian Business Number (ABN) in Australia has even more tips to help you secure your ABN without a hitch.
Registering Your Business Name and Company
The ASIC Registration Process
Getting a company registered is a bigger deal than just reserving a business name. You'll be dealing with the ASIC portal, formally appointing directors, and taking on specific legal responsibilities. It's a step more business owners are taking seriously. In July 2025, for example, while 118,162 new ABNs were registered, a whopping 35,844 of those were new companies. That's a 20.41% jump from the previous year, which tells us that founders are increasingly prioritising the protection and growth potential that a company structure provides. You can see more on this trend in the full New Business Index Report. Be prepared for a fee when you register with ASIC. Currently, setting up a standard proprietary limited company will set you back around $576. For a full walkthrough of what's involved, have a look at our detailed guide on how to set up a Pty Ltd company in Australia.It's vital to remember that a business name registration offers zero ownership or protection over the name itself. It's simply a registration that allows you to trade under that alias. True brand protection comes from trademarking.
Name Selection and Protection
Before you get too attached to a name, you absolutely must check if it's available. A quick search on ASIC’s online tool will show you if your dream business name or company name is already being used anywhere in Australia. A few practical tips from experience:- Be Unique: Don't pick a name that sounds like five other businesses in your industry. You want to stand out, not blend in.
- Check Everywhere: Search the business name register and the company register. Crucially, also check for existing trademarks on the IP Australia website.
- Secure Your Domain: As you're checking names, open another tab and see if the .com.au domain is available. Grab it immediately if it is.
Navigating Your Tax and GST Obligations
The GST Threshold Explained
The Australian Taxation Office (ATO) has a clear rule: GST registration becomes mandatory once your business has a current or projected annual turnover of $75,000 or more. For non-profits, that figure is $150,000. Remember, turnover is your gross business income—every dollar that comes in—not your profit. This is a classic tripwire for new business owners, especially in service-based fields where growth can be unpredictable. Imagine a freelance IT consultant starting out. They might only be making $5,000 a month. But if they suddenly land a big project and their projected income for the year shoots past that $75,000 mark, they have just 21 days to register for GST.Don’t just wait until you hit the $75,000 mark. Proactively monitor your cash flow and forecasts. Registering late can lead to penalties and a messy back-payment process that catches many new entrepreneurs off guard.
Should You Register for GST Voluntarily?
What if you're nowhere near the threshold? You can still choose to register for GST voluntarily. This isn't a simple yes-or-no answer; it’s a strategic decision with real financial consequences.- The Upside: You can claim GST credits on your business purchases. If you've had major setup costs—think computers, specialised equipment, or software—registering lets you claim back the 10% GST you paid on those items.
- The Downside: You must charge GST on all your sales. This effectively increases your prices by 10%. If your customers are the general public (who can't claim GST credits), this could make you less competitive.
- The Admin: It adds another layer of paperwork. Once registered, you are legally required to lodge a Business Activity Statement (BAS) with the ATO, which for most new businesses is a quarterly task.
Other Essential Tax Registrations
GST is just one piece of the puzzle. As your business evolves, other tax registrations will come into play, usually triggered by specific milestones. Two of the most common ones are:- Pay As You Go (PAYG) Withholding: This is non-negotiable the moment you hire your first employee. You're required to withhold tax from their salary and wages and send it to the ATO on their behalf.
- Fringe Benefits Tax (FBT): If you start providing certain benefits to employees—like a company car for private use or paying for their health insurance—you'll likely need to register for FBT.
Final Steps and Staying Compliant
You’ve done the heavy lifting and got the core registrations sorted. But don't pop the champagne just yet. Getting registered is a one-time sprint; staying compliant is a marathon that protects the business you’ve worked so hard to build. Your first practical move? Open a dedicated business bank account. Seriously, do this now. It’s not just a friendly suggestion; it’s absolutely essential for clean financial management. I’ve seen countless new business owners create a bookkeeping nightmare for themselves by mixing personal and business funds. It’s a fast track to chaos at tax time. A separate account gives you a crystal-clear record of income and expenses, which makes tracking your financial health and lodging your BAS a whole lot simpler.Keeping on Top of Your Ongoing Duties
With your banking sorted, your focus now shifts to the recurring tasks that keep your business in good standing. Think of these as your business's regular health check-ups. Ignoring them can lead to penalties and, worse, damage your professional reputation. Here’s what you’ll need to manage:- Business Name Renewal: That business name you registered isn't yours forever. You have to renew it with ASIC every one or three years. Miss the deadline, and you could lose the right to use it.
- ASIC Annual Review: If you're running a company, you'll get an annual statement from ASIC. You must check it, update any company details that have changed, and pay the annual review fee. It's a non-negotiable part of keeping your company registration active.
- Keeping Your ABN Details Fresh: Your details on the Australian Business Register (ABR) must always be current. If you move your business, change your contact info, or alter your structure, you have just 28 days to update it.
Staying compliant is about more than just dodging fines. It's about building a professional operation that earns trust with customers, suppliers, and the ATO. Cutting corners here undermines the very credibility you're trying to build.One last thing that often gets missed in the rush: industry-specific licences. A café needs a food licence from the local council. A builder needs a state-based contractor licence. These aren't optional extras; they're critical for operating legally. Ticking off this final checklist ensures your business starts on solid, lawful ground.
Got Questions? We've Got Answers
Stepping into the world of business registration always brings up a few curly questions. Let's tackle some of the most common ones we hear from entrepreneurs just starting out.How Long Does This Whole Registration Thing Take?
Honestly, it varies. Some parts are incredibly fast. For instance, applying for your ABN online through the Australian Business Register can often spit out your number almost instantly. Registering your business name is usually just as quick once the payment goes through. The real waiting game is typically with a company registration. Once you've lodged all your paperwork with ASIC, you should expect it to take about one to two business days. The longest part of the process is almost always the prep work on your end—finalising your structure and getting all your details in order before you even start the applications.Do I Have to Register for GST Straight Away?
Not necessarily. The key trigger for mandatory GST registration is your turnover. You only have to register once your annual business turnover is projected to hit $75,000 or more. For non-profits, that threshold is higher at $150,000. However, you can choose to register voluntarily before you reach that magic number. Why would you? Registering early means you can start claiming GST credits back on your business purchases. The trade-off is that you must also start charging GST on your sales and lodging regular Business Activity Statements (BAS) with the ATO. It's a strategic choice you'll need to make based on your business model and expected expenses.Quick Tip: ABN vs. ACN An ABN is your 11-digit Australian Business Number, used by all business types for tax purposes. An ACN, on the other hand, is a 9-digit Australian Company Number given only to registered companies. If you set up a company, you'll have both.
The four main structures are sole trader, partnership, company, and trust. A sole trader is simplest and cheapest but offers no liability protection. A company provides limited liability at a flat tax rate but costs more to run. A trust offers tax flexibility and asset protection but is complex to administer. The right choice depends on income, risk profile, and growth plans.
Base rate entities — companies with aggregated turnover under $50 million that derive no more than 80% of income from passive sources — pay 25%. All other companies pay 30%. Shareholders pay income tax on dividends, potentially offset by franking credits for tax already paid at the corporate level.
Consider a company when business net profit consistently exceeds $100,000–$120,000 and the rate differential generates meaningful savings, when you need liability protection from business creditors, when you plan to bring in investors, or when you want to retain earnings at the lower corporate rate rather than distributing everything as personal income.
A family trust (discretionary trust) holds assets for a class of beneficiaries. The trustee decides each year how much income to distribute to each beneficiary. By directing income to members in lower tax brackets, the trust reduces the overall family tax burden. Income retained in the trust is taxed at the highest marginal rate (47%).
Ongoing costs include the ASIC annual review fee (currently $310 for a proprietary company), company tax return lodgement fees, accounting fees for financial statements, and potentially payroll and BAS compliance. Total annual compliance costs typically range from $2,000 to $8,000 depending on activity levels and complexity.