
You sign the sale papers. Relief kicks in for about five minutes. Then your accountant sends the draft tax position, and the capital gain looks big enough to punch a hole in your retirement plan.
I've seen this too many times. Owners spend years building a business, negotiate hard on price, and then treat the tax side like an admin task. That's backwards. A sale isn't finished when the contract is signed. It's finished when the after-tax cash is in your hands.
The good news is Australia has small business CGT concessions built for genuine small business owners. The bad news is they're technical, easy to misuse, and expensive to get wrong. If you need a broader primer on the sale side first, BizBuySell has a practical guide to capital gains tax for sellers. If you're also trying to work out timing, this overview on when you pay capital gains tax helps frame the lodgement side.
- The Million-Dollar Question After Selling Your Business
- First Hurdle Passing the Basic Eligibility Tests
- The Four Concessions A Tool for Every Situation
- Strategy Over Checklist The Critical Order of Application
- A Worked Example From Cafe Sale to Tax Saved
Table of Contents
- The Million-Dollar Question After Selling Your Business
- First Hurdle Passing the Basic Eligibility Tests
- The Four Concessions A Tool for Every Situation
- Strategy Over Checklist The Critical Order of Application
- A Worked Example From Cafe Sale to Tax Saved
- Paper Trails and Pitfalls Your Compliance Checklist
- Final Verdict When to Stop DIY and Call a Specialist
The Million-Dollar Question After Selling Your Business
You sell the business. The money hits the account. Then your accountant tells you a big slice of that gain may be taxable because nobody planned the concession pathway before the contract was signed.
That is the moment small business owners realise the sale price was only half the job.
The question is simple. How much of the gain do you get to keep, and how much do you hand over because the concessions were treated like a year-end checklist instead of a sale strategy?
Small business CGT concessions can reduce, ignore, or defer part of the gain on the sale of an active business asset. There are four of them, and the order you apply them can change the outcome dramatically. Get the sequence right and you can strip out a large tax bill. Get it wrong and you can burn through money that should have stayed in your retirement fund or gone back into the next venture.
Small business CGT concessions are a planning regime, not a box-ticking exercise. Treat the order casually and you will pay for it.
The expensive mistake is waiting until tax return time to ask the CGT question. By then, the asset mix is set, the paperwork is done, and the wrong entity may already be locked into the gain. I see owners focus on the headline sale price and ignore how goodwill, business premises, shares, units, or trust interests are being sold. That is how avoidable tax bills happen.
If you need a plain-English refresher on when capital gains tax applies to a business sale, read that first. Then come back to the concession strategy, because the tax does not sort itself out after settlement.
A decent guide to capital gains tax for sellers can help you frame the issue, but significant savings come from applying the rules in the right order and backing every step with evidence.
This sale may fund retirement, clear debt, or bankroll the next chapter. A sloppy approach is expensive.
First Hurdle Passing the Basic Eligibility Tests
Settlement is done. The price looks good. Then your accountant asks a question that should have been dealt with months earlier. Did the seller qualify for the small business CGT concessions?
That is the first trap.
The concessions only help if you clear the basic eligibility tests first. If you miss them, the later strategy means nothing. Worse, many owners test the wrong entity, the wrong asset, or the wrong group, then build an entire tax position on bad assumptions. That mistake gets expensive fast.

Start with the seller, not the concession
Do not start by asking which concession sounds best. Start by asking who made the gain, what was sold, and whether that asset qualifies at all.
The basic tests boil down to three questions.
-
Does the seller satisfy an entry test?
Usually that means the small business entity route based on aggregated turnover, or the maximum net asset value route based on the group's net assets. -
Was the asset an active asset?
Owning an asset near the business is not enough. It must have been used in the business in the way the law requires. -
If shares or trust interests were sold, do the extra conditions stack up?
This is where many DIY claims fall apart. Shares and units bring extra rules, and sloppy assumptions here can wipe out the concession outcome.
The ATO's eligibility overview for small business CGT concessions is the right starting point for the legal framework. Then you need to apply it to your structure, your sale documents, and your evidence.
The costly mistake is testing the trading entity in isolation
Owners often look at the business they run day to day and stop there. That is not how these rules work.
Turnover and net asset tests can pull in connected entities and affiliates. A family trust holding the premises, a spouse's company, a second entity carrying staff or equipment, or a holding company sitting over the top can all change the result. If you ignore those links, your numbers are wrong before the calculation even starts.
Entity structure matters here more than people think. If you need a refresher, read this guide on business legal structures in Australia and how they affect tax treatment.
A common failure looks like this. The trading company appears small enough on its own. The owner assumes the turnover test is met. But once related entities are grouped in, the threshold is blown. Or the turnover test fails, yet nobody checks the net asset route, even though that second gate might still save the claim. Good advice is not about memorising the tests. It is about applying them in the right order and checking every available path before giving up.
Active asset is where loose language causes real damage
“Business asset” is not the same as “active asset.”
That distinction matters.
Goodwill usually gets the attention because it is obviously tied to the business. Other assets are less straightforward. Business premises, shares, units, loan accounts, and assets used partly for business and partly for investment need closer analysis. If the asset does not meet the active asset rules for the required period, the concession claim can collapse even if the business itself is well under the thresholds.
I see this mistake with properties all the time. Owners say, “It was part of the business.” That is not evidence. You need records that show how the asset was used, by which entity, and for how long.
Check the file before you check the tax saving
Before anyone models the tax outcome, get the file in order:
- Entity map: who owns each entity, who controls it, and which entity sold the asset
- Group analysis: connected entities, affiliates, and assets held outside the trading entity
- Asset analysis: what exactly was sold and why it qualifies as an active asset
- Financial records: accounts, valuations, and working papers that support the entry test used
- Sale documents: contracts that match the actual transaction, not a vague commercial summary
This is risk management, not paperwork for its own sake. If the eligibility position is weak, every later concession is exposed. And if you test eligibility early, you still have time to fix documents, challenge assumptions, and choose the right path instead of cleaning up a mess after settlement.
The Four Concessions A Tool for Every Situation
Once you're inside the rules, you've got four tools. Not four magic tricks. Four distinct tools with different jobs.
Bad advice on this subject proves expensive. Too many guides throw the concessions into one pile and make them sound interchangeable. They're not. One can wipe out the gain. One cuts it. One can shelter part of what remains. One pushes the problem down the road. If you don't know the purpose of each, you'll choose badly.
What each concession is really for
The 15-year exemption is the premium outcome. Lawpath's summary notes that it can disregard the entire capital gain if the asset was owned for at least 15 years and the owner is over 55 and retiring, with the retirement exemption carrying a lifetime limit of $500,000 per individual. It also notes that for companies, a CGT concession stakeholder must generally hold at least 20% to qualify (Lawpath guide).
That first concession is the one owners dream about, and for good reason. If you qualify, the gain can disappear for tax purposes. But this is also where people get sloppy. They hear “retiring”, hear “owned it for ages”, and assume they're home. They aren't home until every condition is checked.
The 50% active asset reduction is more mechanical. It's often the workhorse concession in ordinary business sales. It doesn't have the glamour of the 15-year exemption, but it can still be the move that changes a painful gain into a manageable one.
Then there's the retirement exemption. Despite the name, don't reduce it to a retirement story in your head. It's a tax concession with rules, choices, and consequences. It can be powerful because it lets you disregard part of the remaining gain, but it's not something to apply casually just because it sounds beneficial.
The rollover relief is different again. It's about deferral. Sometimes that's exactly what a business owner needs. Sometimes it just delays a problem while creating fresh compliance pressure.
The best concession is the one that fits your facts, not the one with the best headline.
Comparing the four small business CGT concessions
| Concession Name | Primary Benefit | Key Requirement |
|---|---|---|
| 15-year exemption | Can disregard the entire capital gain | Asset owned for at least 15 years, with qualifying retirement or incapacity conditions |
| 50% active asset reduction | Reduces the gain by half | Asset must qualify and the basic conditions must be satisfied |
| Retirement exemption | Can disregard part of the remaining gain | Lifetime limit of $500,000 per individual |
| Rollover relief | Defers the gain | Replacement planning and ongoing compliance need to be managed carefully |
A few blunt calls from practice:
- Best for clean exits: The 15-year exemption is the strongest outcome if you qualify.
- Best for ordinary sales: The active asset reduction often does the heavy lifting where the 15-year exemption isn't available.
- Best when flexibility matters: The retirement exemption can finish the job on a reduced gain.
- Best when you're still moving pieces around: Rollover relief suits owners changing assets, not owners chasing a simple final outcome.
If you want a broader view of where these rules sit within the tax system, this explainer on capital gains tax exemptions in Australia gives useful context.
Why this matters: picking the right concession, or combination, can radically change the after-tax result from the same sale.
Strategy Over Checklist The Critical Order of Application
A business owner sells, hears the words "small business CGT concessions," and assumes it is a menu. Pick one. Maybe stack another. Job done. That lazy approach is how people overpay tax and burn through concessions they did not need to use.
The core issue is order. These rules work in a set sequence, and the sequence changes the dollars. Treat it like a checklist and you miss the strategy. Treat it like a calculation with consequences and you keep more of the sale proceeds.

The sequence drives the outcome
As noted earlier, the order is fixed. You deal with capital losses first. Then you apply the general CGT discount if it is available. Then comes the 50% active asset reduction. After that, you decide whether the retirement exemption or rollover relief should deal with what is left.
That order is not a technical footnote. It decides how much gain survives to each later step. If you change the order on paper, you change the tax result, and usually not in your favour.
Read the process the way an accountant does:
- Start with the capital gain: Get the raw number right before touching any concession.
- Apply capital losses first: Old or current year capital losses reduce the gain before anything else.
- Apply the general CGT discount if eligible: If the asset and taxpayer qualify, reduce the gain here.
- Apply the 50% active asset reduction next: This often cuts the remaining gain harder than owners expect.
- Use the retirement exemption or rollover last: These are end-stage choices, not opening moves.
If you want a broader practical guide to reducing capital gains tax on a business sale, read that separately. Then come back to the sequencing issue, because the expensive mistakes happen there.
The costly mistake. Using the retirement exemption too early
Plenty of business owners fixate on the retirement exemption because it sounds like the biggest prize. Wrong instinct.
If the active asset reduction is available, you first reduce the gain through the required sequence, then decide how much of the retirement exemption you need. That matters because the retirement exemption has a lifetime cap. Waste it on a gain that could have been reduced earlier and you have permanently lost room that may matter later.
The right question is simple: what is the smallest taxable gain left after applying the rules in the correct order?
That is the strategy.
Risk management matters just as much as tax saved
Rollover relief is another trap. Owners often grab it because deferring tax feels attractive. Sometimes it is. Sometimes it just pushes a problem into the future and adds compliance risk if the replacement asset rules are not handled properly.
Use rollover relief when it supports a real commercial plan. Do not use it as a reflex. Deferring tax without a clear replacement strategy is how businesses create future mess, future amendments, and future adviser fees.
The bottom line is blunt. The concessions are not a shopping list. They are a sequence of tools, and the order decides whether you preserve flexibility, minimise tax, and avoid wasting limited relief. Getting that order wrong is expensive.
A Worked Example From Cafe Sale to Tax Saved
Let's make this concrete. Sarah owns a café she's run for years. She sells the business asset and ends up with a capital gain. No jargon. No hand waving. Just the mechanics.

Sarah's sale in plain English
Sarah sells for $1.2 million and her cost base is $400,000. That leaves a capital gain of $800,000.
Now the important part. We don't jump straight to an exemption and hope for the best. We test whether she's in the small business CGT concessions regime, then we follow the order of application. If you're unsure how sale price and asset value get assessed in the first place, this primer on the business valuation formula is worth a look.
For this example, assume Sarah passes the basic conditions and the asset qualifies. She has owned and operated the café for 12 years, so the 15-year exemption is not in play.
Sarah's outcome doesn't depend on finding a loophole. It depends on applying ordinary rules properly.
Applying the sequence step by step
Start with the gain of $800,000.
Then apply the general CGT discount. That takes the gain down to $400,000.
After that, apply the 50% active asset reduction. That takes the remaining gain down to $200,000.
At that point, Sarah can use the retirement exemption to disregard the final $200,000. Because the retirement exemption has a lifetime limit of $500,000 per individual, that amount sits within the limit described earlier.
#SmallBusinessTax #CGT #TaxConcessions #AustralianBusiness #TaxPlanning #BusinessExit
Here's the worked flow in table form:
| Step | Calculation | Remaining gain |
|---|---|---|
| Starting position | Capital gain | $800,000 |
| General CGT discount | Reduce by 50% | $400,000 |
| 50% active asset reduction | Reduce by 50% | $200,000 |
| Retirement exemption | Disregard remaining amount | $0 |
That's the difference between reading about concessions and using them properly. Same sale. Same facts. Very different after-tax result.
A short explainer can help if you want to hear another walkthrough before talking to your adviser:
One warning. This example is useful because it's simple. Real sales often aren't. The minute you add multiple entities, property held outside the trading business, trust distributions, or sale proceeds split across different asset classes, the “easy” calculation stops being easy.
Why this matters: once you see the sequence work on a real number, it becomes obvious why sloppy ordering is so expensive.
Paper Trails and Pitfalls Your Compliance Checklist
Claiming a concession is one thing. Defending it is another.
The ATO won't accept “my accountant said it should be fine” as evidence. If your file is thin, inconsistent, or built after the fact, you've handed them a problem to investigate. A good claim needs records that line up with the law, the contract, and the tax return.
What records actually matter
Keep the documents that prove the story from start to finish:
- Acquisition records: Contracts, settlement statements, and anything showing when and how the asset was acquired.
- Sale records: The sale agreement, adjustments, and supporting schedules that show what was sold.
- Business use evidence: Lease arrangements, operating records, financials, and other material supporting active use in the business.
- Entity documents: Company registers, trust deeds, unit holdings, and anything else proving who owned the asset and who controlled the entity.
- Valuation support: If a value question affects eligibility or allocation, get evidence that would survive scrutiny.
- Tax working papers: Keep the CGT calculation, assumptions, elections, and adviser notes together in one file.
Practical rule: If someone new picked up your file in two years' time, they should be able to reconstruct the claim without guessing.
Lodgement also matters. The concession doesn't live in your head or in your email chain. It has to be reflected correctly in the return and supporting schedules. If your records and your lodged position don't match, you've created your own audit trigger.
Common Pitfall last-minute changes create ugly problems
I see this often. Owners change structure, move assets, tidy up ownership, or alter business use near the sale date because someone told them it would “make things cleaner”. Sometimes it does the opposite.
A rushed restructure can muddy the ownership history. A late shift in asset use can weaken the active asset position. A vague allocation in the sale contract can create a valuation dispute you didn't need. These problems don't always show up on settlement day. They show up when the return is lodged and someone tries to justify the claim line by line.
Use this quick pre-lodgement checklist:
- Check ownership history: Make sure legal ownership and tax records align.
- Check active use evidence: Don't rely on memory. Pull documents.
- Check group relationships: Review related entities before signing off on eligibility assumptions.
- Check calculation order: The maths must follow the required sequence.
- Check elections and records: If a concession requires a formal choice or internal record, deal with it properly and on time.
Why this matters: a claim without documents is just a story, and stories don't survive review.
Final Verdict When to Stop DIY and Call a Specialist
Here's the blunt view. If your sale is simple, your structure is simple, and the asset history is clean, a competent adviser can usually map the path without drama. But many “small” businesses aren't simple at all. They're family groups, related entities, mixed-use assets, old trusts, stale company registers, and records spread across ten folders and three software systems.
That's when DIY stops being brave and starts being reckless.
Red flag checklist
Call a specialist if any of these apply:
- You operate through a company or trust: The rules become more technical, especially around ownership interests and stakeholder requirements.
- You have related entities or family group assets: Eligibility testing gets harder fast when control and ownership sit across multiple entities.
- The sale includes more than one asset: Allocation issues can distort the CGT result if handled badly.
- You're relying on the retirement exemption: This is not the place for rough calculations or assumptions.
- You want rollover relief: Deferral brings future compliance with it. If you don't manage that properly, today's tax problem becomes tomorrow's tax problem.
- Your records are incomplete: Missing evidence turns even a good technical position into a risky claim.
- You're deciding structure after signing heads of agreement: Late planning is better than none, but it's still late.
The blunt recommendation
If you tick even one of those boxes, stop trying to solve the whole issue from blog posts and scattered notes.
Get a proper review before the return is lodged. Better yet, get advice before the contract is locked in. The biggest tax savings usually come from decisions made while the transaction is still flexible. Once the deal is done, many options are gone and all that's left is damage control.
Why this matters: the cost of expert advice is usually tiny compared with the cost of getting a major CGT claim wrong.
CGT is not a separate tax — a capital gain is included in your assessable income for the year a CGT event occurs. It applies when you dispose of a CGT asset including shares, investment properties, business assets, and cryptocurrency. Your primary residence is generally exempt, though partial exemptions apply in specific circumstances.
The capital gain is capital proceeds (sale price) minus the cost base. The cost base includes purchase price, stamp duty, legal fees, and capital improvement costs. If the asset was held for more than 12 months, apply the 50% CGT discount to reduce the gain before adding it to taxable income. Keep all acquisition records from the purchase date.
Australian resident individuals and trusts that have held a CGT asset for more than 12 months can reduce their capital gain by 50% before inclusion in assessable income. Superannuation funds receive a one-third discount. Companies do not qualify. The holding period begins on the purchase date and ends on the disposal contract date.
Shares are CGT assets. When you sell shares, the gain or loss is proceeds less cost base (purchase price plus brokerage). Gains on shares held more than 12 months qualify for the 50% discount. Capital losses can only offset capital gains — they cannot reduce other income. Carry forward unused losses to offset future gains.
The main residence exemption can entirely or partially exempt the gain from selling your home. Full exemption applies if the property was your main residence throughout the ownership period, was never used to produce income, and sits on land of two hectares or less. Partial exemption applies where it was rented or used for business during part of the ownership period.
If you're selling a business asset, dealing with overdue returns, or trying to work out whether the small business CGT concessions apply to your situation, Australia Wide Tax Solutions can help you get the numbers right before an avoidable mistake becomes an expensive one. Their team works with individuals and business owners across Australia on capital gains tax, business accounting, BAS, late lodgements, and practical tax planning, with clear advice that focuses on the after-tax result.
From 2019 to 2023, short-term residential landlords in Australia dropped by 25%, while listings fell by only 11%. That gap matters. It shows the market is getting harder for casual hosts and more rewarding for operators who run the property like a business.
If you want to learn How to monetise on short term rental market in Australia, focus on net return, not gross booking revenue. High occupancy means very little if poor record-keeping, GST mistakes, private-use errors, or local rule breaches wipe out your profit later. I have seen plenty of owners post strong booking numbers and still end up with weak cash flow, messy BAS issues, or an ATO review they were not prepared for.
The hosts who keep more of what they earn are disciplined. They price properly, keep clean records, separate private and income-producing use, understand deduction limits, and treat council rules as a profit issue, not an admin nuisance.
The ones who struggle usually chase nightly rates, copy what other Airbnb hosts are doing, and assume tax will sort itself out at year-end. It does not. In short-term rental, revenue gets attention, but compliance decides whether the investment works.
- The STR Paradox Why More Listings Mean Fewer Landlords
- Australia's 2026 STR Market Landscape By The Numbers
- The Great Debate STR vs Long-Term Rental
- Navigating the Minefield of State and Council Rules
- Your Tax Obligations You Can't Hide from the ATO
Table of Contents
- The STR Paradox Why More Listings Mean Fewer Landlords
- Australia's 2026 STR Market Landscape By The Numbers
- The Great Debate STR vs Long-Term Rental
- Navigating the Minefield of State and Council Rules
- Your Tax Obligations You Can't Hide from the ATO
- Boosting Your Bottom Line Advanced Monetisation Tactics
- Tax-Smart Strategies to Maximise Your Net Return
- Your Next Steps to STR Success with AWTS
The STR Paradox Why More Listings Mean Fewer Landlords

Short-term rental attracts plenty of first-time hosts because the income looks straightforward. It rarely stays straightforward for long.
As noted earlier, the market has seen fewer landlords without an equivalent drop in listings. That points to consolidation. Casual owners are leaving, while better-run operators keep expanding, refining systems, and protecting margin. If you are entering this market now, you are not competing against someone renting out a spare apartment on weekends. You are competing against operators who treat STR as a real business.
Why consolidation matters
The pressure shows up in three places fast:
- Pricing gets tighter: Professional hosts adjust rates constantly, protect occupancy, and avoid leaving money on the table.
- Operations get sharper: Slow replies, average cleaning, and poor presentation now cost bookings.
- Compliance gets more expensive to ignore: The bigger and more visible the sector becomes, the easier it is for poor record-keeping, weak tax treatment, and council breaches to turn into real financial damage.
Practical rule: Run the property with separate accounts, documented processes, and audit-ready records from day one.
That is the part many investors get wrong. They focus on nightly rate and ignore the admin burden until the ATO, their accountant, or their local council forces the issue. By then, the fix is usually expensive.
What separates profitable hosts from ATO problems
The operators who last usually get three decisions right early:
- They buy or hold in the right location, not just the property they already happen to own.
- They calculate net return after cleaning, platform fees, vacancy, insurance, and tax, instead of fixating on gross booking revenue.
- They set up tax and compliance properly before launch, including records for deductions, occupancy, private use, and future CGT treatment.
The third point is where real money is kept or lost. A property can book well and still produce a poor after-tax result if the owner mixes private and rental use, overclaims expenses, ignores GST risk, or creates a capital gains problem they never priced in.
The key takeaway is simple. Monetising a short-term rental in Australia is not about chasing bookings alone. The market now rewards disciplined operators who can price well, run clean systems, and defend every tax position if the ATO asks questions.
Australia's 2026 STR Market Landscape By The Numbers

$71,770 average annual revenue, $317 ADR, and 62.20% occupancy. Those 2025 national figures, reported by Airbtics’ Australia short-term rental market report, explain why investors keep piling into short-term rental.
They also mislead people.
National averages are useful for spotting demand. They are poor tools for choosing a property. I have seen owners buy off a citywide revenue number, then discover their suburb has weak midweek demand, heavy cleaning costs, stricter local rules, and an after-tax result that looks nothing like the headline.
What the headline figures actually mean
Value lies in the spread between markets. Brisbane recorded stronger occupancy than Melbourne in the same dataset, while Melbourne still showed solid revenue. That should reset how you assess an STR opportunity. Size of city does not protect margin. Demand quality does.
A prestige postcode with too much competing stock can underperform a less fashionable area with steadier booking patterns. That matters even more once you price in platform fees, furnishing, consumables, insurance, and the tax treatment of mixed private use.
Use a market screen that reflects profit, not vanity.
| Market signal | What it means for you |
|---|---|
| High occupancy | Demand is recurring across the year, not just driven by one holiday spike |
| Strong ADR | Guests will pay for the property type, fit-out, and location |
| Healthy annual revenue | The property can carry off-peak periods without relying on one short season |
| Fast supply growth | New competition will pressure weaker listings and thinner margins |
Where investors get the numbers wrong
A lot of buyers still choose with their emotions first. They buy the beach unit they like personally, the city apartment near a favourite restaurant strip, or the property they plan to use for themselves during school holidays. That is a lifestyle purchase. It is not disciplined STR investing.
Benchmark the property against its likely guest and booking pattern, not against a city average.
As noted earlier, demand has stayed firmer in prime pockets than broad national summaries suggest. The best operators target a clear guest type, longer stays where the market supports them, and booking channels that reduce empty nights. They do not assume the city average will save a mediocre asset.
There is also a tax angle investors ignore. If your numbers only work before tax, they do not work. Private use days, poor apportionment, and sloppy expense claims can wipe out the upside quickly. Before you chase higher gross income, understand how rental deductions and ownership strategy interact with broader property tax settings such as negative gearing for property investment.
A blunt filter before you buy or furnish
Ask four questions early.
- What drives demand here? Business travel, events, holiday traffic, hospital visits, relocation stays, or contractor demand all produce different booking patterns.
- What supports a premium rate? Parking, family layout, pet-friendliness, views, walkability, design, and low-friction check-in all affect pricing power.
- What does turnover do to margin? High occupancy with constant changeovers can still produce weak net return.
- Can the property operate within local rules without losing too many available nights? A strong suburb means little if regulation cuts your usable inventory.
City averages are a starting point. The takeaway is that data stops you from paying premium money for average performance.
The Great Debate STR vs Long-Term Rental
Short-term rental can produce more gross income than a standard lease. It can also produce more admin, more record-keeping, and more tax mistakes. Investors who focus only on the top-line nightly rate usually find that out too late.
The actual comparison is not STR versus LTR on revenue. It is STR versus LTR on net return after cleaning, platform fees, utilities, vacancy gaps, depreciation treatment, private use, and ATO scrutiny. A property that looks brilliant on Airbnb can still underperform a plain long-term rental once those items are counted properly.
The clean comparison
Here’s the side-by-side view investors should use before choosing a model.
| Metric | Short-Term Rental (STR) | Long-Term Rental (LTR) |
|---|---|---|
| Revenue potential | Higher upside if pricing, occupancy, and presentation are strong | Lower upside, but steadier |
| Cash flow pattern | Uneven, seasonal, and booking-dependent | Predictable rent cycle |
| Management effort | High. Guest messages, cleaning, calendar control, reviews | Lower. Tenant management is slower-paced |
| Vacancy risk | Frequent gaps between bookings | Lower day-to-day churn |
| Operating costs | More cleaning, supplies, platform fees, restocking, utilities | Usually simpler cost base |
| Regulatory burden | Heavier. Registration, caps, local rules, guest compliance | Usually simpler |
| Tax complexity | Higher. Mixed-use issues, detailed records, apportionment, CGT planning, possible GST questions in some structures | Still important, but more straightforward |
| Lifestyle flexibility | Greater owner use if structured carefully | Less owner access during tenancy |
| Scalability | Works with strong systems and process | Easier administratively, but less opportunity to increase revenue |
A lot of investors choose STR for flexibility and higher income potential. Fair enough. But flexibility has a tax cost if you or your family use the property privately. Once private days enter the picture, deductions often need to be apportioned. Get that wrong and your return is overstated before you even lodge.
Who should choose which model
STR suits investors who are prepared to operate a small accommodation business, not just hold an investment property. That means active pricing, fast guest communication, reliable cleaning, clear evidence for every expense, and discipline around private use. If you dislike admin or want passive income, STR is usually the wrong fit.
LTR suits investors who want consistency, lower turnover, and a cleaner compliance position. It is less exciting. It is often more durable. Plenty of experienced property owners make better money long term by avoiding operational chaos and keeping deductions straightforward.
Use this filter.
- Choose STR if the property has genuine nightly-rate power and you will run it like a business.
- Choose LTR if stable occupancy, simpler management, and fewer tax adjustments matter more to you.
- Choose based on net profit after tax, not the gross booking screenshots that get posted online.
If gearing is part of your strategy, read our guide to negative gearing for property investment before you commit to a structure that only works on paper.
The wrong rental model does not just trim profit. It creates avoidable admin, weak records, and tax positions that are hard to defend later.
Choose the model you can operate properly. Higher potential yield means very little if poor systems, private use, and weak records hand part of that income back to the ATO.
Navigating the Minefield of State and Council Rules

Council rules can destroy a good-looking STR deal faster than a bad guest ever will.
A lot of hosts still act as if the only real challenge is getting bookings. That’s naive. Night caps, registration systems, local zoning pressure, safety requirements, and state-based levies all change what a property can earn. If your legal operating window is restricted, your monetisation strategy has to change with it.
Rules shape profit more than most hosts admit
One of the clearest examples comes from New South Wales. Under regulatory pressure such as the 180-night cap for unhosted rentals, 43% of hosts said they would rather leave the property empty for the rest of the year than convert to long-term rental, according to EurekAlert’s coverage of the host response to caps. That tells you two things. First, caps materially affect business decisions. Second, many hosts haven’t built a plan B.
Byron Bay’s 60-day cap is even tighter, based on the same verified material. If you own in a restricted market, you need to think less like a landlord and more like a yield manager. Every available night has to count.
Common Pitfall
Assuming the rules are the same everywhere is one of the most expensive mistakes in this space.
A compliant setup in one Local Government Area may fail in another because councils can apply different requirements around registration, zoning, safety, or allowable nights. Investors often discover this after purchase, which is far too late.
Use this pre-listing checklist:
- Check your LGA first: Don’t rely on agent chatter or forum comments.
- Confirm hosting category: Hosted and unhosted arrangements can be treated differently.
- Review operational caps: Your annual revenue model is meaningless if legal nights are capped.
- Budget for compliance costs: Levies, registration, and admin time reduce margin.
If your rental turnover is pushing you toward business-style obligations, review when to register for GST before the issue becomes urgent.
A restricted property can still be profitable. An illegally operated property is just a future liability.
Some hosts respond to regulation by doing less. Smart operators do the opposite. They refine pricing, target longer stays, and make sure each permitted booking window earns properly.
Why this matters: Compliance isn’t paperwork sitting on the edge of the business. It shapes the business model itself.
Your Tax Obligations You Can't Hide from the ATO
The ATO doesn’t need to guess whether you earned short-term rental income. Platform data, bank records, and digital payment trails make that fantasy obsolete.
The tax side of STR gets messy because the sector is shifting from casual hosting to professional operation. Verified reporting notes that the sector is professionalising, and that professional operators face different rules for deductions and GST registration than casual hosts, while Victoria’s 7.5% short-stay levy adds another layer of complexity, according to Mortgage Professional Australia’s report on the shift toward professional operators. That’s where owners get caught. They still think like occasional hosts while operating like a business.
Income tax is the easy part
Every dollar of rental income belongs in your tax return. That includes platform payouts, cleaning fees charged to guests, and other booking-related amounts that form part of your assessable income position.
That part isn’t controversial. The problems start when hosts mix private use and income-producing use, fail to apportion correctly, or claim expenses they can’t substantiate. If you use the property yourself, your records need to show exactly when it was available for rent and when it wasn’t.
A good starting point is understanding rental income tax rules before your first year-end scramble.
GST BAS and CGT are where mistakes get expensive
The biggest blind spots usually sit in three areas.
-
GST registration
The verified material states that GST registration becomes mandatory once turnover hits the $75,000 threshold in the context of professional STR activity. Plenty of owners drift into that threshold without noticing because they track booking income loosely across platforms and bank accounts.
-
BAS obligations
Once you’re registered, BAS isn’t optional admin. It becomes part of your operating rhythm. Late or inaccurate lodgements create compounding problems fast.
-
Capital gains tax
If a property has been used to produce income, especially if it was once your home, you need to think beyond annual tax returns. STR use can affect the main residence exemption when you sell. Owners who ignore that issue often get an unpleasant surprise years later.
Here’s the line I use with clients: if the property is run for profit with repeat commercial activity, don’t assume the ATO will see you as a casual host just because you started that way.
| Tax area | What hosts often get wrong |
|---|---|
| Income tax | Under-reporting platform income or poor apportionment |
| GST | Missing the turnover threshold and registering late |
| BAS | Treating lodgements as occasional admin instead of core compliance |
| CGT | Ignoring future sale consequences while focusing only on current cash flow |
Why this matters: Revenue problems hurt. Tax problems compound, attract penalties, and often surface long after the income has been spent.
Boosting Your Bottom Line Advanced Monetisation Tactics

Basic listings don’t win anymore. They just exist.
If you want to know How to monetise on short term rental market in Australia, stop obsessing over whether your property is “on Airbnb” and start asking whether it’s priced, positioned, and presented better than competing stock. That’s what moves revenue.
Average hosts get average results
Verified market analysis from Beyond Pricing’s Australia STR earnings article says hosts using dynamic pricing algorithms can increase revenue by 20% to 30%, and notes that for a typical Sydney listing this could lift annual revenue from $45,750 to over $60,000 through better rate optimisation. That’s not magic. It’s disciplined pricing.
Dynamic pricing tools don’t just raise prices. Good ones also protect occupancy by responding to local demand, lead time, event calendars, day-of-week patterns, and competitor positioning. Tools like Beyond Pricing are useful because they force hosts to stop guessing.
The hosts I trust operationally tend to focus on four levers:
- Pricing discipline: No flat nightly rate year-round.
- Stay-length strategy: Longer stays can reduce turnover cost and cleaning friction.
- Guest segment targeting: Families, business travellers, relocation guests, and premium leisure travellers book differently.
- Listing quality: Professional photos, clear house rules, and strong amenity positioning still matter.
Pro-Tip
Multi-channel distribution works, but only if your systems can handle it.
Listing across Airbnb, Stayz, and Booking.com can widen occupancy opportunities, but you need synced calendars and a proper workflow. Otherwise you’re inviting double bookings and refund headaches. If you want practical ideas to boost rental property bookings, that resource gives useful marketing angles beyond just lowering price.
Better monetisation usually comes from better positioning, not from panicking and discounting.
A smarter property also targets booking types that fit local constraints. In cap-heavy or high-turnover markets, longer stays often stabilise operations. In event-heavy markets, short premium windows can outperform broad discounting.
For a city-specific operational playbook, this guide on how to run a successful short-term rental in Sydney is a strong reference point.
Why this matters: The biggest gap in STR isn’t between bad hosts and good hosts. It’s between hosts who react and hosts who run revenue systems.
Tax-Smart Strategies to Maximise Your Net Return
Gross income flatters owners. Net return tells the truth.
A property can look brilliant on booking platforms and still underperform after interest, cleaning, platform fees, repairs, insurance, utilities, levy impacts, and tax. Investors who last in STR learn to think like operators. That means every expense needs a commercial purpose, every deduction needs support, and every record needs to survive scrutiny.
Claim what you’re entitled to and prove it
The deduction side of STR usually falls into two buckets.
First, there are immediate deductions for recurring operating costs. These commonly include agent or platform commissions, cleaning, insurance, council rates, loan interest related to the investment, consumables, and repairs where eligible.
Second, there are longer-term claims tied to the property itself, including capital works deductions and depreciation on eligible assets. Consequently, DIY tax returns often leave money behind because owners don’t have the right reports, don’t understand apportionment, or don’t separate capital and revenue items properly.
A disciplined expense system should include:
- Dedicated bank account: Keep rental cash flow separate from private spending.
- Digital storage: Save invoices, platform statements, levy records, and receipts as you go.
- Private-use diary: If you use the property yourself, document it properly.
- Asset tracking: Furniture, appliances, and improvements need clean records.
If you haven’t reviewed building and asset claims properly, start with an investment property depreciation schedule. Many hosts miss deductions because they never get the schedule prepared.
Structure beats improvisation
I’m sceptical of blanket advice in this area because entity choice depends on facts. Still, one principle is constant. Randomly mixing private ownership, family use, and business-style activity creates tax mess.
Net return improves when records are clean, ownership is intentional, and claims are prepared before lodgement pressure hits.
Keep these judgment calls front of mind:
| Decision area | Tax-smart approach |
|---|---|
| Expense claims | Claim eligible costs with invoices and clear business purpose |
| Private use | Apportion honestly and keep a usage record |
| Improvements | Separate repairs from capital works |
| Entity choice | Get advice before scaling, not after |
| Year-end prep | Reconcile platform income to bank deposits and records |
The hosts who keep more money aren’t always the ones with the highest gross revenue. Usually they’re the ones who document better, classify better, and plan before year-end instead of hoping their accountant can fix everything in a week.
Why this matters: Tax efficiency isn’t aggressive claiming. It’s organised, defensible claiming that protects profit and reduces audit risk.
Your Next Steps to STR Success with AWTS
Reading about short-term rental won’t make it profitable. Systems will.
Most failures happen before the first booking. Investors buy in the wrong area, ignore local restrictions, underestimate setup and compliance costs, and keep poor records from day one. Cleaning, guest communication, and pricing all matter, but they only work when the structure underneath is solid.
Use this checklist before you list
-
Research your LGA
Go straight to the council source. Don’t trust forums, property chat groups, or what a selling agent “reckons”.
-
Run the numbers properly
Model income conservatively. Include downtime, cleaning, consumables, utilities, maintenance, platform fees, compliance costs, and tax effects. If the deal only works in a perfect month, it doesn’t work.
-
Open a separate bank account
This sounds basic because it is. It also saves an enormous amount of pain at tax time.
-
Choose your systems early
Use a spreadsheet if you must, but make sure every booking, expense, and payout is tracked from the start.
What disciplined operators do differently
They don’t wait until June to organise receipts. They don’t guess about GST. They don’t leave cleaning standards to chance.
For operators refining turnover standards between guests, this article on short-term rental cleanliness secrets is practical and worth saving. Cleanliness isn’t just hospitality. It affects reviews, repeat bookings, damage detection, and dispute handling.
A final operating checklist:
- Know your legal limits: Allowed nights, registration, and local conditions.
- Know your numbers: Gross revenue, net margin, and tax exposure.
- Know your evidence: Invoices, statements, usage records, and improvement costs.
- Know your exit impact: Today’s rental decisions can affect future CGT outcomes.
If you’re serious about learning How to monetise on short term rental market in Australia, think like an owner-operator, not a casual host. The market still rewards well-run properties. It punishes sloppy ones.
Why this matters: A profitable STR doesn’t come from one clever trick. It comes from dozens of disciplined decisions made early and repeated consistently.
Declare all rental income received: regular rent, advance rent, rent in kind, insurance payouts for lost rent, and bond money kept for unpaid rent. Gross rent before expenses is included in assessable income. The rental property schedule of the tax return captures income and expenses separately from other income.
Deductible expenses include council rates, water charges, land tax, insurance, property agent fees, repairs and maintenance, loan interest on funds borrowed for the property, advertising for tenants, and depreciation on eligible assets. Capital improvements are depreciated over time; borrowing costs are spread over five years or the loan term, whichever is shorter.
Negative gearing occurs when rental expenses exceed rental income. The net rental loss is deducted from your other assessable income (such as wages), reducing total taxable income and therefore tax payable. It is most beneficial for taxpayers in higher marginal brackets and must be reported accurately on the rental property schedule.
Yes. The sale triggers a CGT event. The gain is proceeds less cost base (purchase price, stamp duty, legal fees, and improvement costs). If owned for more than 12 months, apply the 50% CGT discount before adding the gain to assessable income. Previously claimed capital works deductions reduce the cost base and increase the eventual gain.
Yes, if the property is genuinely available for rent at a market rate. Expenses during a vacancy are deductible while the property is advertised. If the property is not genuinely available — reserved for personal use or listed above market rent — deductions may be denied or apportioned for the vacant period.
If you want expert help getting the structure right from day one, speak with Australia Wide Tax Solutions. Their team helps property investors and business owners handle rental schedules, BAS lodgements, GST questions, capital gains tax issues, and overdue returns so your short-term rental runs on compliance as well as revenue.
The main residence exemption 6-year rule is a powerful provision from the Australian Taxation Office (ATO) that can save property owners a fortune in Capital Gains Tax (CGT). In short, it allows you to treat your home as your main residence for tax purposes for up to six years after you stop living in it.
- What Is the 6-Year Absence Rule and When Can You Use It?
- How the 6 Year Rule Works in Practice
- Calculating Capital Gains With The 6-Year Rule
- Navigating Common Pitfalls and Special Cases
- Essential Record Keeping for ATO Compliance
This means you can move out, rent the property, and still potentially sell it completely tax-free, as long as you meet a few key conditions.
What Is the 6-Year Absence Rule and When Can You Use It?
Think of the 6-year rule as a 'pause button' on your CGT obligations. Normally, as soon as you start renting out a property, it becomes an investment, and selling it triggers capital gains tax. This rule, however, lets your former home keep its tax-free status even while it's earning you rental income, offering incredible financial flexibility.
This isn’t some obscure loophole. It’s a deliberate part of Australia's tax law, designed to accommodate common life events. The ATO recognises that people often need to move temporarily for work or family reasons without being forced into a fire sale of their home.
Who Benefits From the 6-Year Rule?
Many Australians find themselves in situations where this rule is an absolute lifesaver. It’s specifically for property owners who have genuinely lived in a property, established it as their home, and then need to move away for a while.
Common scenarios we see all the time include:
- Work Relocations: You get a fantastic job offer interstate or an overseas secondment. You can take the opportunity without having to sell your property, perhaps in a down market.
- Lifestyle Changes: Life happens. You might move in with a new partner, need to care for a sick relative, or just want to 'try out' living in a new area before making a permanent decision.
- Upsizing or Downsizing: You've bought a new home that's a better fit for your family, but you decide to keep the old one as an investment property, at least for a few years.
For example, say you're a professional in Sydney who has lived in your Chippendale apartment for years. A new role takes you to Brisbane. Under the 6-year rule, you could rent out your Sydney apartment from the day it first generates income—let's say 1 July 2026—and still be eligible for the full CGT exemption for up to six years, as long as you don’t buy and nominate another property as your main residence in that time.
Crucial Condition: This is the most important part: to use the 6-year rule, you cannot treat any other property you own as your main residence during your absence. You only get one main residence exemption at a time.
The 6-Year Rule at a Glance
Before you count on this exemption, it's essential to understand how it works. While every situation has its nuances, the core principles are straightforward.
Here's a quick summary of the key conditions you'll need to satisfy.
| Condition | What It Means for You |
|---|---|
| Initial Residence | The property must have been your genuine main residence before you moved out. You can't buy an investment and claim it. |
| No Other Main Residence | You can't nominate another property as your main residence while claiming the exemption on the first one. |
| Income-Producing | The six-year clock starts on the first day the property is genuinely available to produce income (i.e., rented out). |
| Six-Year Limit | You can claim the full exemption if you sell the property within six years of moving out. |
| Resetting the Clock | If you move back in and re-establish it as your home, the six-year clock resets for any future absence. |
Mastering these conditions is the first step toward using this significant tax advantage. For a deeper dive into the primary exemption itself, you can learn more about the capital gains tax main residence exemption in our detailed guide.
How the 6 Year Rule Works in Practice
Knowing the theory behind the main residence exemption 6 year rule is one thing, but putting it into practice correctly is where the real money is saved. The practical details are what stand between you and a massive Capital Gains Tax (CGT) bill. It all comes down to knowing exactly when the clock starts ticking, what actions can reset it, and how to safeguard the value your home built up before it ever became a rental.
The most critical moment is when the six-year countdown begins. This clock doesn’t start the day you pack up your boxes and move out. Instead, the Australian Taxation Office (ATO) starts the timer on the very first day your former home is genuinely available to produce income. For most people, this is simply the date it’s first listed for rent.
This distinction is huge. If you move out on 1 March but the property isn’t ready for tenants and only gets listed for rent on 1 May, your six-year period kicks off on 1 May. From that date, you have up to six years to sell the property without triggering CGT, as long as you don’t nominate another property as your main residence in the meantime.
This decision tree gives you a great visual of how the 6-year rule flows, from the moment you establish your home as your main residence right through to selling it within that precious exempt window.

As you can see, the key to a full exemption is finalising the sale before that six-year, income-producing period runs out.
The Power to Reset the Clock
One of the best parts of the 6 year rule is its flexibility. You’re not just stuck with a single six-year window. If life changes direction, you can always move back into the property and re-establish it as your genuine main residence.
By doing this, you effectively reset the clock. If you need to move out and rent the property again down the track, a brand-new six-year exemption period starts from the date it next begins to produce income. This is a powerful feature that allows homeowners to adapt to life’s curveballs—like a second job placement or changing family needs—without forfeiting this fantastic tax break.
For instance, say you rent out your home for four years. If you move back in and live there for a good while, that original four-year absence is done and dusted. If you later move out and put it up for rent again, a fresh six-year countdown begins.
Protecting Pre-Rental Growth with a Valuation
For anyone who first rented out their main residence after 20 August 1996, the ‘market value substitution rule’ is a non-negotiable strategy. This rule is specifically designed to protect all the capital growth your home enjoyed while you were living in it, shielding it completely from CGT.
To lock in this protection, you must get a formal market valuation of your property at the time it is first used to produce income. This valuation sets a new ‘cost base’ for CGT purposes.
What this means is the ATO will only look at the change in value from that specific point forward when calculating any potential capital gain. All the value your property gained before it became a rental is completely ignored, locking in those tax-free gains for good.
Let's walk through a real-world example:
- You bought your home back in 2015 for $600,000.
- You lived there until 2024, by which time its market value had shot up to $1,000,000.
- In 2024, you get a formal valuation done for $1,000,000 and immediately start renting it out.
By getting that valuation, you’ve essentially "banked" $400,000 of tax-free capital growth. Even if you end up renting the property for more than six years and become liable for some CGT, the tax will only apply to the growth that happens after that $1,000,000 valuation date. Skipping this step is a costly mistake that could expose years of tax-free growth to an unnecessary tax bill.
Calculating Capital Gains With The 6-Year Rule
Understanding the theory is one thing, but running the numbers is where the main residence exemption 6-year rule really proves its worth. Knowing how to correctly calculate your Capital Gains Tax (CGT) liability—or better yet, confirm you have none—is how this powerful rule translates into real, tangible savings.
Let's walk through some practical, number-driven examples to demystify the process and show you exactly how the calculations work in different situations. We’ll look at both a full exemption and a partial one.
Scenario 1: A Full Exemption
The simplest and most rewarding outcome is getting a complete CGT exemption. This is what happens when you sell your property while the six-year, income-producing clock is still ticking.
Imagine you bought your home in 2017 for $700,000. You lived in it as your main residence until 2022, when you had to move interstate for a new job. You immediately rented it out and ended up selling it in 2026 for $1,100,000, netting a capital gain of $400,000.
Because you sold the property only four years after it first started producing income—well inside the six-year limit—and you didn’t nominate another property as your main residence, the outcome is refreshingly simple.
Result: You pay $0 in Capital Gains Tax. The entire $400,000 gain is sheltered by the main residence exemption.
This is the ideal use of the 6-year rule, showcasing its power to protect your profits during a temporary absence. But of course, not every situation fits so neatly into this perfect box.
Scenario 2: A Partial Exemption Calculation
Life is unpredictable, and sometimes you might end up renting out your former home for longer than the six-year period. When this happens, you don't lose the entire exemption. Instead, you get what’s called a partial exemption.
This means CGT is only calculated on the portion of time the property was rented after the six-year grace period ended. The Australian Taxation Office (ATO) uses a specific formula to figure this out:
Capital Gain x (Non-Main Residence Days / Total Ownership Days) = Taxable Portion
Let's break this down with a more detailed example.
- Total Ownership Period: You own a property for 10 years (3,650 days).
- Main Residence Period: You lived in it as your main residence for the first 2 years (730 days).
- Income-Producing Period: You then rented it out for the remaining 8 years (2,920 days).
Of those 8 years it was rented, the first 6 years are covered by the 6-year rule. This means only 2 years (730 days) are counted as "non-main residence days" for tax purposes.
Now, let's crunch the numbers.
1. Calculate Your Total Capital Gain:
- Sale Price: $1,500,000
- Purchase Price & Costs (Cost Base): $600,000
- Total Capital Gain: $900,000
2. Apply the Apportionment Formula:
- $900,000 (Capital Gain) x (730 Non-Main Residence Days / 3,650 Total Ownership Days)
- $900,000 x 0.20 = $180,000 (This is your taxable portion before any discounts)
3. Apply the 50% CGT Discount:
- Because you owned the property for more than 12 months, you're eligible for the 50% CGT discount.
- $180,000 x 50% = $90,000
In this scenario, only $90,000 is added to your assessable income for the financial year you sold the property. The other $810,000 of your gain is completely tax-free. Our in-depth guide to capital gains tax on selling a home explores these calculations in more detail.
The financial benefit here is massive. If you were taxed at a marginal rate of 37%, your tax liability would be around $33,300. Without the partial exemption, your taxable gain could have been far higher, leading to a tax bill of over $150,000.
Remember, beyond capital gains, you need to manage all tax implications of a rental. A rental income tax calculator can help you stay on top of your ongoing obligations while the property is generating income under the 6-year rule. As you can see, getting this apportionment formula right is crucial to minimising your final tax bill.
Navigating Common Pitfalls and Special Cases
While the main residence exemption 6-year rule offers fantastic flexibility, real-world property ownership often comes with complexities. Certain situations can create costly tax traps if you’re not paying close attention.
Understanding these common pitfalls and special cases is essential for protecting your exemption and avoiding an unexpected Capital Gains Tax (CGT) bill down the track.
The Critical 'No Other Main Residence' Choice
One of the most frequent traps we see involves the 'no other main residence' condition. This rule is absolute: you and your spouse can only claim one property as your tax-free main residence at any given time for your combined family unit.
If you move out of your old home and buy a new one that you start living in, you face a choice. You can't just apply the 6-year rule to the old place while simultaneously treating the new property as your main residence.
You must decide which property gets the main residence exemption for that overlapping period. Claiming the exemption on your new home immediately stops the 6-year rule clock on your old property from that point forward.
Even simple administrative actions can have huge tax consequences. For example, updating your address on the electoral roll to your new property is a strong signal to the Australian Taxation Office (ATO) that you've established a new main residence. This one action can inadvertently kill the 6-year rule on your former home, exposing it to CGT from the date you made the change.
A Gotsis Accounting case study illustrates this perfectly. An owner named Sam rented out his Melbourne home on 1 September 2013 after moving to Sydney. He could have claimed a full tax exemption until 2019, but he jointly bought a new Sydney property in 2015 and claimed it as his main residence. This decision cut his 6-year exemption period short for the Melbourne home. As you can see, choosing your main residence has direct financial impacts.
Joint Ownership and Deceased Estates
The rules for joint ownership and deceased estates also demand careful attention. When you own a property with a spouse or partner, the ATO treats you as a single unit for main residence purposes. You can't each nominate a different property to double your tax-free gains.
Things get even more nuanced when dealing with a deceased estate. If you inherit a property that was the deceased's main residence, you might be able to continue the exemption, but specific conditions and time limits apply.
Generally, selling an inherited property within two years of the person's death often allows for a full CGT exemption. However, if the deceased was using the 6-year rule when they passed away, the rules for the beneficiary become much more complex. This is a situation where professional tax advice is almost always required to navigate correctly.
Key Takeaway: The ATO views a couple as a single entity for the main residence exemption. You cannot claim two main residences simultaneously, even if you each own a property in your own name.
Holiday Homes Versus Temporary Absences
Another common mistake is trying to apply the main residence exemption 6-year rule to a holiday home. This rule was never intended for investment properties or weekenders that weren't your genuine home in the first place.
To be eligible, you must have first established the property as your actual main residence. The ATO looks for clear evidence of this, such as:
- Your personal belongings being kept there.
- Receiving your mail at that address.
- Having utilities connected in your name.
- Being registered on the electoral roll at that address.
A holiday home that you occasionally rent out just won't meet this initial test. Without first establishing the property as your genuine home, any absence—whether for six years or six months—doesn't qualify for the exemption. Misunderstanding this distinction is a frequent and expensive error that can lead to a significant tax bill when you sell.
Essential Record Keeping for ATO Compliance
When it comes to the main residence exemption 6 year rule, keeping meticulous records isn’t just good practice—it's your most critical line of defence. The Australian Taxation Office (ATO) puts the burden of proof squarely on you, the taxpayer. Without the right documents, you risk having your claim denied and being hit with a substantial Capital Gains Tax (CGT) bill.
Think of your records as the evidence that tells the story of your property's life. They need to prove it was your genuine home before you moved out and then justify the period of your absence. This paperwork is the foundation of any successful claim.
Proving It Was Your Main Residence
Before you can even think about claiming an exemption for an absence, you first have to prove the property was your legitimate main residence. The ATO isn't interested in your word for it; they look for objective, third-party evidence showing you actually lived there and treated it as your home.
Key documents to lock this down include:
- Electoral Roll Registration: Having your name on the electoral roll at that address is a powerful indicator.
- Utility Bills: Gas, electricity, and internet bills in your name, delivered to the property.
- Personal Mail: Bank statements, government correspondence, and other personal mail showing the property as your address.
- Insurance Policies: Home and contents insurance policies that list the property as your primary residence.
Documenting Your Absence and Rental Period
Once you've established the property as your home, the next step is to document the period you were away. This is especially important if you rented it out, as these records prove when the six-year clock started and are vital for any partial exemption calculations.
Crucial Document Alert: If you first used your home to generate income (i.e., rented it out) after 20 August 1996, getting a formal market valuation at that time is absolutely non-negotiable. This valuation sets a new "cost base," effectively protecting all the capital growth your home earned while you lived there from any future CGT.
Your checklist for this period should include:
- Market Valuation Report: A formal valuation from a qualified professional, dated to when the property was first available for rent.
- Rental Agreements: Copies of all lease agreements with tenants, showing dates, names, and rental income.
- Property Manager Statements: The end-of-year financial statements from your real estate agent are perfect for this.
- Expense Records: Keep all invoices and receipts for income-producing expenses like repairs, agent fees, and council rates during the rental period.
Keeping these files organised isn't just a compliance headache; it's a practical necessity for getting your tax calculations right. For a broader overview, our guide on ATO record keeping requirements is a great resource. Strong records give you peace of mind and ensure you can confidently justify your tax position if the ATO ever comes knocking.
Maximizing Your Outcome with Professional Tax Advice
Getting your head around the main residence exemption 6 year rule can be tricky, but the rewards are huge. When applied correctly, it gives you incredible flexibility to adapt to life's changes—like taking a job interstate or overseas—without being forced into a premature sale of your home. The biggest win, of course, is the potential for massive Capital Gains Tax (CGT) savings, and the power to reset the six-year clock just by moving back in is a massive long-term advantage.
But knowing the rules is one thing; applying them to your real-life situation is another. Going it alone can be a risky move when there are significant financial consequences on the line.
When to Call in an Expert
While some straightforward cases might be manageable, certain scenarios should be a clear signal to pick up the phone and get professional advice. Seeking expert help is a must if you're dealing with:
- Complex partial exemption calculations, especially where your property was rented for more than six years.
- The property is part of a deceased estate, which brings its own tangled web of tax rules.
- You own multiple properties and need to make the right call on which one to nominate as your main residence.
- You’re living overseas but are still an Australian resident for tax purposes.
In these situations, one small misstep can easily lead to a large—and completely avoidable—tax bill.
An experienced tax specialist at AWTS provides personalised advice tailored to your specific circumstances. We make sure you stay fully compliant with ATO requirements while strategically using every part of the 6-year rule to your benefit.
Beyond just the 6-year rule, understanding other ways to maximize your rental property tax benefits is key to keeping the ATO happy and ensuring a healthy return on your investment.
Don’t leave your tax outcome to chance. With an expert in your corner, you can confidently apply the main residence exemption and lock in the best possible financial result.
Common Questions About The 6-Year Rule
When it comes to the main residence exemption 6-year rule, the devil is in the detail. Getting these details right is the difference between legally minimising your Capital Gains Tax (CGT) and facing an unexpected bill from the ATO. Here are some clear answers to the questions property owners ask us most often.
Can I Use the 6-Year Rule for a Holiday Home I Rent Out?
No, the 6-year rule won't apply to a property that has only ever been a holiday home. This exemption is strictly for a property that you first established as your genuine main residence.
The Australian Taxation Office (ATO) needs to see clear proof that the property was your primary home before you started your absence. This means things like having your mail delivered there, being registered on the electoral roll at that address, and keeping your personal belongings on-site. A property you use for occasional getaways, even if you rent it out, simply doesn't meet this fundamental test.
What if I Move Back in for Only a Few Months?
Moving back into the property and re-establishing it as your main residence can reset the six-year clock. This is one of the most powerful features of the rule, but be warned: your intention is everything.
A brief stay of just a few weeks or months could easily be scrutinised by the ATO. To successfully reset the clock, you have to genuinely make the property your home again. This is more than just a token visit; it involves concrete actions like changing your address on the electoral roll, redirecting mail, and making it your primary place of dwelling.
I Moved Overseas—Will I Lose the Exemption?
Moving overseas doesn't automatically mean you lose access to the main residence exemption 6-year rule. As long as you remain an Australian resident for tax purposes, you can still apply the rule for up to six years, provided you don't buy and nominate another property as your main residence.
However, the game changes completely if you become a non-resident for tax purposes. Recent legislative changes mean that if you are a non-resident when you sign the contract of sale, you generally lose access to the main residence exemption entirely, unless specific life events apply. This makes seeking advice before you sell from overseas absolutely critical.
My Spouse and I Own Two Properties. Can We Claim Separate Main Residences?
No, you can't. For any given period, a couple (including spouses and de facto partners) can only have one main residence for the entire family. You can't each nominate a different home to try and get two tax-free properties.
ATO Rule of Thumb: If you and your spouse own two homes, you must choose which one will be treated as the main residence for both of you during any overlapping period. Making this choice has direct financial consequences for CGT when you eventually sell either property.
CGT is not a separate tax — a capital gain is included in your assessable income for the year a CGT event occurs. It applies when you dispose of a CGT asset including shares, investment properties, business assets, and cryptocurrency. Your primary residence is generally exempt, though partial exemptions apply in specific circumstances.
The capital gain is capital proceeds (sale price) minus the cost base. The cost base includes purchase price, stamp duty, legal fees, and capital improvement costs. If the asset was held for more than 12 months, apply the 50% CGT discount to reduce the gain before adding it to taxable income. Keep all acquisition records from the purchase date.
Australian resident individuals and trusts that have held a CGT asset for more than 12 months can reduce their capital gain by 50% before inclusion in assessable income. Superannuation funds receive a one-third discount. Companies do not qualify. The holding period begins on the purchase date and ends on the disposal contract date.
Shares are CGT assets. When you sell shares, the gain or loss is proceeds less cost base (purchase price plus brokerage). Gains on shares held more than 12 months qualify for the 50% discount. Capital losses can only offset capital gains — they cannot reduce other income. Carry forward unused losses to offset future gains.
The main residence exemption can entirely or partially exempt the gain from selling your home. Full exemption applies if the property was your main residence throughout the ownership period, was never used to produce income, and sits on land of two hectares or less. Partial exemption applies where it was rented or used for business during part of the ownership period.
Navigating the complexities of the main residence exemption 6-year rule, especially with ever-changing laws and your own personal circumstances, can be a minefield. The team at Australia Wide Tax Solutions are specialists in property tax. We provide the clear, tailored advice you need to make confident decisions and secure the best possible tax outcome.
Find out how we can help by visiting us at https://www.awts.net.au.
When you inherit a property, one of the first questions that often comes to mind is, "what about taxes?" While Australia doesn't have a direct inheritance tax, the concept of Capital Gains Tax (CGT) becomes crucial the moment you decide to sell the asset. In short, you’re taxed on the profit—the 'capital gain'—made from the property's increase in value.
- Your Guide to Inherited Property and Capital Gains Tax
- How to Determine Your Property's Cost Base
- Using the Main Residence Exemption
- Calculating CGT on an Inherited Property Sale
- Navigating Special Circumstances and Common Pitfalls
Your Guide to Inherited Property and Capital Gains Tax
Inheriting property is a major life event, but it comes with a complex financial reality. The key thing to grasp is that the tax isn’t on the act of inheriting; it applies to the gain you make when you eventually sell. Think of it less as a tax on receiving a gift and more as a tax on the profit from a future sale.
This guide is designed to untangle these often-confusing rules. We'll walk you through the key concepts, exemptions, and calculations step-by-step, using real-world examples to make everything clear. Getting your head around these principles is the first step toward making smart financial decisions and confidently managing your tax obligations.
Key Concepts You Need to Know
To really get to grips with capital gains tax on inherited property in Australia, you need to be familiar with a few foundational ideas:
- No Inheritance Tax: First things first, Australia did away with estate and inheritance taxes decades ago. You do not pay tax simply for receiving a property from a deceased estate.
- CGT is the Main Concern: The primary tax you'll face is Capital Gains Tax. It's only triggered when a "CGT event" happens—which, for most people, means selling the property.
- Profit, Not Value: CGT is calculated on the capital gain (the sale price minus the property's cost base and other associated costs), not the total value of the home itself.
A common misconception is that inherited property is entirely tax-free. While you aren't taxed on the inheritance itself, the Australian Taxation Office (ATO) considers any subsequent capital gain from its sale as assessable income.
Why This Matters for You
Navigating these rules correctly can make a huge difference to your financial outcome. For instance, understanding how to use exemptions like the main residence exemption could potentially save you tens of thousands of dollars. On the flip side, failing to keep proper records or miscalculating the property’s cost base can lead to overpaying tax or even facing penalties from the ATO.
For a comprehensive breakdown of the specific tax obligations that come with inherited assets, you can refer to an expert guide on deceased estate tax returns and capital gains tax in Australia. This guide will arm you with the knowledge to handle your inherited property with financial confidence.
How to Determine Your Property's Cost Base
When it comes to Capital Gains Tax on an inherited property, the single most important number you need to get right is the cost base. Think of it as the starting line for your ownership. The Australian Taxation Office (ATO) measures the property's growth in value from this specific point, and any profit you make above it is what becomes your capital gain.
But here’s the tricky part: that starting line isn't always in the same place. For inherited properties, its location hinges entirely on one critical date in Australian tax history: 20 September 1985. This date splits properties into two completely different categories, and each comes with its own set of rules for working out the cost base.
Nailing this calculation is crucial because it directly shapes how much tax you might have to pay. Get it wrong, and you could end up either overpaying the ATO or, much worse, underpaying and finding yourself with penalties down the track.
The flowchart below gives you a quick visual rundown of the initial steps you’ll need to navigate.

As you can see, the journey starts when you inherit the asset, but CGT only comes into play if and when you decide to sell it.
Property Acquired Before 20 September 1985
If the person who left you the property originally bought it before this key date, it’s considered a "pre-CGT asset." For beneficiaries, the rules for these older properties are generally much kinder.
In this case, your cost base isn't what they originally paid for it. Instead, it’s the market value of the property at the date of the deceased's death.
This is a massive advantage. It effectively wipes the slate clean, meaning all the capital growth that occurred during the deceased's ownership is completely ignored for tax purposes. You're only assessed on the change in value from the day they passed away until the day you sell. To get this right, you'll need a solid grasp of understanding fair market value at that specific time.
Property Acquired On or After 20 September 1985
Things are quite different for properties the deceased bought on or after this date. These are known as "post-CGT assets," and the rules are far less generous.
For these properties, you inherit the deceased's original cost base. This means your starting line is their initial purchase price plus any other costs they racked up, like stamp duty, legal fees, and the cost of any major renovations.
Key Takeaway: You essentially step directly into the deceased's tax shoes. The property’s value when they passed away is completely irrelevant for setting your cost base, and the entire capital gain from their original purchase could be taxable.
To help you see how these rules play out, the table below breaks down the two scenarios.
Cost Base Rules for Inherited Property
| Scenario | Deceased Acquired Property BEFORE 20 Sept 1985 | Deceased Acquired Property ON or AFTER 20 Sept 1985 |
|---|---|---|
| Asset Type | Pre-CGT Asset | Post-CGT Asset |
| Your Cost Base Is... | The market value at the date of death. | The deceased's original cost base (purchase price + costs). |
| Impact on CGT | Only the growth in value after death is taxed. | The entire growth in value since the original purchase is potentially taxed. |
This clear distinction is why the first question any tax professional will ask is about the original purchase date. It’s also why good record-keeping is so vital. For post-CGT assets, you'll absolutely need the deceased’s original purchase records to calculate your future tax bill correctly. Without them, you risk the ATO determining a cost base for you, which may not work in your favour.
Using the Main Residence Exemption
For many Aussies inheriting a property, the main residence exemption is the single most important rule to understand. It can be the difference between paying zero tax and facing a hefty Capital Gains Tax bill. Think of it as the tax system’s way of acknowledging that a family home is more than just a financial asset.
But getting access to this powerful exemption isn’t a given. It comes with some very specific strings attached, particularly around timing. The most critical of these is the famous “two-year rule,” a window of opportunity that allows many beneficiaries to sell the property completely CGT-free. Getting your head around how this works is absolutely essential.
The Critical Two-Year Rule
This rule is the cornerstone of the main residence exemption for inherited homes. It’s pretty straightforward: if you sell the property within two years of the person’s date of death, you can often get a full CGT exemption.
But to qualify, two crucial conditions must be met:
- The property had to be the deceased's main residence right before they passed away.
- It must not have been used to generate any income (like being rented out) at that time.
If you tick both of those boxes, you can sell the property within that two-year period, and any capital gain is completely ignored. This is a massive relief, giving you breathing room to sort out the estate without the pressure of a looming tax bill.
What Happens If You Miss the Two-Year Window?
Now, this is where things get tricky and where many people get caught out. Missing the two-year deadline doesn't automatically mean you’ll pay a fortune in tax, but the rules change dramatically.
If you sell after the two-year mark, you’ll likely be up for CGT. The tax is calculated on the growth in the property's value from the date of death up until the date you sign the contract of sale. The market value at the date of death effectively becomes your new cost base.
Let's break it down with an example.
Example Scenario:
Sarah inherits her mum's house. Her mother passed away on 1 May 2023, and the house was valued at $800,000 on that day.
Scenario A (Within 2 Years): Sarah sells the house for $850,000, with the contract signed on 1 March 2025. Because she sold it within the two-year window, the $50,000 capital gain is fully exempt. She pays $0 in CGT. Easy.
Scenario B (Outside 2 Years): Sarah holds onto the property for a bit longer and sells it for $920,000, signing the contract on 1 July 2026. Because she missed the two-year window, her cost base is the $800,000 value at death. Her taxable capital gain is now $120,000 ($920,000 - $800,000).
Partial Exemptions for Mixed-Use Properties
Of course, life isn't always so clear-cut. What if the deceased ran a small business from a home office, or rented out a room for extra cash? In these cases, you might be looking at a partial CGT exemption.
The tax office expects you to work out what percentage of the property was used for private living versus producing income. For instance, if 20% of the home's floor space was used exclusively as a business office, then 20% of the capital gain would generally be taxable.
The same logic applies if the property was only the deceased’s main residence for part of the time they owned it. You can dive deeper into this topic in our guide on the capital gains tax main residence exemption. The key is that the gain has to be apportioned based on the number of days it was a home versus the days it was earning income. This is where good record-keeping becomes absolutely vital.
Calculating CGT on an Inherited Property Sale
Right, now that we’ve covered the ground rules, let's get into the numbers. At first glance, calculating the Capital Gains Tax (CGT) on an inherited property might feel a bit intimidating, but it’s really just a logical, step-by-step process. Think of it as a simple subtraction sum that we’ll fine-tune as we go.
The whole calculation boils down to figuring out your sale price, subtracting the correct cost base (plus any other costs you're allowed to claim), and arriving at your capital gain. From there, a very handy discount can often chop that taxable figure in half.
Step 1: Identify Your Capital Proceeds
First things first, you need your starting figure: the capital proceeds. This is just the sale price of the property—the amount you received from the buyer. You’ll find this clearly stated on the contract of sale.
It's important to note this is the gross figure, before you've paid out expenses like the real estate agent’s commission or your solicitor’s fees. Don’t worry, we’ll account for those in the next step.
Step 2: Determine and Adjust the Cost Base
Next up is the cost base. As we talked about earlier, this crucial number depends entirely on when the person you inherited from originally bought the property. Once you have that starting value, you can start adding other eligible costs to it.
The ATO calls these the "elements of the cost base," and they are your best friend when it comes to reducing your final tax bill. These include:
- Incidental Costs: These are the direct costs of buying or selling the asset. Think stamp duty, legal fees, and those real estate agent commissions.
- Ownership Costs: This covers things like council rates, land tax, and insurance you paid while you owned the property.
- Capital Improvement Costs: Did you make any significant improvements? The cost of adding a deck, renovating a bathroom, or putting in a new kitchen can be added here. Just remember, general repairs and maintenance don’t make the cut.
Tallying up these costs beefs up the property’s total cost base, which directly shrinks your taxable capital gain. This is where good record-keeping really pays off.
Step 3: Calculate the Gross Capital Gain
Now for the easy bit. To get your gross capital gain, you simply subtract your fully adjusted cost base from your capital proceeds.
Formula: Capital Proceeds – Adjusted Cost Base = Gross Capital Gain
This number is the total profit you’ve made on paper. But hold on, this isn't the final amount that gets taxed. There’s one more huge step that can provide some serious relief. For a deeper dive into this, you might find our guide on selling an investment property and CGT helpful.
Step 4: Apply the 50 Percent CGT Discount
Here’s the big one. If you and the deceased (combined) have owned the property for more than 12 months, you're almost certainly eligible for the 50% CGT discount. Honestly, it's one of the most valuable concessions in the entire Aussie tax system.
This discount lets you slash your gross capital gain in half. The leftover 50% becomes your net capital gain—and that is the final figure you have to report on your tax return.
Critically, the 12-month clock starts ticking from when the deceased first bought the property, not from when you inherited it. This means for the vast majority of inherited properties, hitting that 12-month requirement is a given.
Step 5: Determine Your Final Tax Payable
The last step is to take your net capital gain and add it to your other assessable income for the financial year (like your salary). This new, higher total income determines which marginal tax bracket you fall into.
It’s a common misconception that the gain is taxed separately. It's not. The gain is simply added to your income for the year, and that total amount is taxed at your personal marginal rate. This can push you into a higher tax bracket, so it's something you need to plan for.
Navigating Special Circumstances and Common Pitfalls
Inheritance is rarely a clean-cut affair, and the standard Capital Gains Tax (CGT) rules don't always neatly fit the messy reality families often face. A few specific factors can throw a spanner in the works, turning a seemingly simple process into a tax minefield. Getting your head around these special situations is crucial to avoiding a nasty surprise from the ATO down the track.
Things like the deceased's residency status, how they used the property before they passed, or inheriting only a piece of the pie can all dramatically shift the tax outcome. Being prepared for these complexities is the best way to manage your capital gains tax on inherited property in Australia and keep things above board.
When the Deceased Was a Foreign Resident
The tax landscape shifts dramatically if the person who passed away was a foreign resident for Australian tax purposes at their time of death. This one detail can lock you out of some of the most powerful tax concessions, most notably the main residence exemption.
If the property was the deceased's main home, their foreign residency status generally triggers a reset. The cost base becomes the property's market value on the date they died. As the beneficiary, you lose the ability to claim the full main residence exemption that might have otherwise wiped out the tax bill. This means you’ll be on the hook for CGT on any growth in value from the date of death until the day you sell.
When the Beneficiary Is a Foreign Resident
Your own residency status is just as critical. If you are considered a foreign resident for tax purposes when you sell the inherited property, the ATO applies a much tougher set of rules.
The biggest sting is that foreign residents are generally not eligible for the main residence exemption. This applies even if the property was the deceased’s home and you manage to sell it within that two-year grace period. On top of that, foreign residents typically lose access to the 50% CGT discount, which can massively inflate the final tax you pay. This is a huge trap for Australian expats inheriting property back home.
Inheriting Only a Share of a Property
It’s incredibly common for a property to be left to multiple people, like a group of siblings. When you inherit just a fraction of a property—say, a 50% interest—you’re responsible for the CGT on your slice of any capital gain.
Each of you treats your share as a completely separate asset. Here’s what that means in practice:
- You calculate your capital gain based only on your percentage of the sale price and cost base.
- Your eligibility for exemptions or discounts is assessed on your own circumstances. For example, if one sibling moves into the house and makes it their main residence, their share of future gains might become exempt, but the other sibling’s share will still be subject to CGT.
- Timing is everything; if you want to dig deeper into how the clock is ticking on these matters, you can explore the details of the deceased estate 3-year rule for more context.
Common Mistakes to Avoid
Even with a solid understanding of the rules, simple mistakes can cause a lot of financial pain. Knowing what to watch out for is your best line of defence.
Key Pitfall: The most common and costly error we see is sloppy record-keeping. If you don't get a formal market valuation done at the date of death, the ATO can challenge your cost base calculations, almost always resulting in a higher taxable gain for you.
Here are a few other traps people frequently fall into:
- Messing Up a Partial Exemption: If the property was ever used to earn income (like a rental or for a home business), you have to correctly apportion the capital gain between private and income-producing use. Just guessing the percentage is a huge red flag for the ATO.
- Forgetting Your Own Ownership Costs: Beneficiaries often forget to add all their holding costs to the cost base. Every legitimate dollar you spend on things like rates, insurance, and maintenance helps reduce your final taxable gain.
- Ignoring CGT When Gifting: If you decide to gift your share of the property to another family member, that’s still a CGT event. The tax office treats it as if you sold your share at its current market value, and you’ll be assessed accordingly.
Your Tax Compliance and Reporting Checklist
Getting your head around the capital gains tax rules for an inherited property is one thing. Actually reporting it correctly to the Australian Taxation Office (ATO) is a whole other challenge. This is where things can go wrong. A simple mistake or missed document can lead to audits and penalties, making an already tough time even more stressful and expensive.
Think of this as your roadmap to getting it right. It’s a practical checklist to make sure you tick all the boxes and finalise the process without any nasty surprises from the ATO.
Gather Your Essential Documents
Before you even log in to myTax, you need to get your paperwork in order. This isn't just about being organised; it's about building your defence. If the ATO ever asks questions, your documents are the only proof you have.
Start pulling together these essentials:
- The Original Purchase Contract: This is the document showing when the person who passed away bought the property and what they paid. It’s absolutely critical for any property bought after 1985.
- Proof of Death: You'll need a copy of the death certificate. This document locks in the date of death, which is a key date for valuations and working out your exemption periods.
- Formal Market Valuation: Get a professional to value the property as at the date of death. This is non-negotiable for pre-1985 properties and is your safety net if you don't sell within the two-year window.
- Records of Your Own Costs: Every single receipt matters. This includes legal fees, real estate agent commissions, council rates you paid, and any money spent on capital improvements. Each one of these costs adds to your cost base and directly reduces the tax you’ll pay.
Let's be clear: proper record-keeping isn't just a good idea, it's a legal requirement. The ATO puts the burden of proof squarely on you, the taxpayer, to justify every figure in your cost base calculation. Without the receipts, you risk having your claims thrown out.
Reporting the Gain to the ATO
Once your documents are sorted and you’ve calculated your net capital gain, the final step is reporting it correctly on your tax return. A common point of confusion is that the gain isn't taxed as a separate lump sum. Instead, it gets added to your other income for that financial year, like your salary.
You'll report the sale in the capital gains or losses section of your individual tax return, whether you use myTax or lodge through a tax agent like us.
Pay close attention to the timing. For CGT, the critical date is the day you sign the contract of sale, not the day the money lands in your account at settlement. This detail can have a massive impact, as a large capital gain could easily push you into a higher marginal tax bracket for that year. It’s something you absolutely need to plan for.
Your Top Questions About Inherited Property and CGT Answered
Stepping into the financial side of an inheritance can be a minefield of questions and uncertainty. When it comes to capital gains tax on inherited property in Australia, we find most beneficiaries run into the same handful of concerns. Let’s cut through the noise and get you some clear, straightforward answers.
We'll tackle the most common questions we hear every day, breaking them down without the confusing tax jargon so you know exactly where you stand.
Do I Have to Pay Tax the Moment I Inherit a Property?
Absolutely not. There's no immediate tax bill when a property is transferred to your name as part of an estate. In Australia, we don't have an 'inheritance tax'.
Capital Gains Tax (CGT) only comes into play when you actually sell or dispose of the property down the track. The tax is worked out based on the capital gain you make when you sell, not on what the property was worth when you inherited it.
What if I Decide to Live in the Inherited House?
This is a great question and a common scenario. If you move into the inherited property and make it your main residence, you can often use the main residence exemption to wipe out any capital gain that builds up after you inherit it.
Even better, if the property was also the deceased's main home, you might be able to claim a full or partial exemption on the gain that accrued during their ownership period as well, depending on how it was used.
The catch? You have to prove it's genuinely your home. We're talking about changing your address on the electoral roll, getting your mail sent there, and connecting the utilities in your name. Just using it as a weekend place won't cut it with the ATO.
Am I Eligible for the 50% CGT Discount?
Yes, in most situations, you certainly are. The 50% CGT discount is a huge help, effectively halving the capital gain you have to pay tax on. To get it, the asset needs to have been owned for at least 12 months.
Here's the crucial part: that 12-month clock includes the time the deceased owned the property. So, as long as the person you inherited from held the asset for more than a year, you'll almost certainly qualify for this discount, assuming you're an Australian resident for tax purposes when you sell.
What Records Do I Absolutely Need to Keep for an Inherited Property?
Good record-keeping is your single best defence against paying too much tax. It's not optional. To calculate your CGT position correctly, you’ll need a solid paper trail.
Here are the non-negotiables:
- The original purchase contract showing when the deceased bought the property.
- A formal market valuation of the property as at the date of death. This is critical.
- Any receipts or proof of capital improvements the deceased made (e.g., renovations, extensions).
- All records of costs you pay from the date you inherit it, like legal fees, stamp duty (if applicable), council rates, and major maintenance.
CGT is not a separate tax — a capital gain is included in your assessable income for the year a CGT event occurs. It applies when you dispose of a CGT asset including shares, investment properties, business assets, and cryptocurrency. Your primary residence is generally exempt, though partial exemptions apply in specific circumstances.
The capital gain is capital proceeds (sale price) minus the cost base. The cost base includes purchase price, stamp duty, legal fees, and capital improvement costs. If the asset was held for more than 12 months, apply the 50% CGT discount to reduce the gain before adding it to taxable income. Keep all acquisition records from the purchase date.
Australian resident individuals and trusts that have held a CGT asset for more than 12 months can reduce their capital gain by 50% before inclusion in assessable income. Superannuation funds receive a one-third discount. Companies do not qualify. The holding period begins on the purchase date and ends on the disposal contract date.
Shares are CGT assets. When you sell shares, the gain or loss is proceeds less cost base (purchase price plus brokerage). Gains on shares held more than 12 months qualify for the 50% discount. Capital losses can only offset capital gains — they cannot reduce other income. Carry forward unused losses to offset future gains.
The main residence exemption can entirely or partially exempt the gain from selling your home. Full exemption applies if the property was your main residence throughout the ownership period, was never used to produce income, and sits on land of two hectares or less. Partial exemption applies where it was rented or used for business during part of the ownership period.
Navigating the maze of deceased estates and CGT requires careful planning and deep expertise. At Australia Wide Tax Solutions, our specialists live and breathe this stuff. We can guide you through every step, ensuring you meet your obligations while achieving the best possible financial outcome. Let us help you manage your tax affairs with confidence. Visit https://www.awts.net.au to book your consultation today.
When you sell an investment property in Australia, getting your head around the selling investment property capital gains tax (CGT) implications is non-negotiable if you want to avoid a nasty surprise from the tax man. It’s important to know that CGT isn't a separate tax. It’s actually a part of your income tax.
- Understanding Capital Gains Tax on Your Investment Property
- How to Accurately Calculate Your Capital Gain or Loss
- Maximising the 50 Percent CGT Discount
- Finding Key CGT Exemptions and Concessions
- Strategic Timing and Smart Record Keeping
Put simply, any profit you make from selling the property gets added to your taxable income for that financial year, which can push you into a higher tax bracket and increase the tax you pay.
Understanding Capital Gains Tax on Your Investment Property
Think of Capital Gains Tax as the Australian Taxation Office's (ATO) share of the profit you've made from an asset's increase in value. For property investors, a capital gain happens when you sell your rental for more than what it cost you to buy and hold onto it. That profit is then tacked onto your income and taxed at your marginal rate.
But here’s the good news: the calculation isn't as blunt as 'sale price minus purchase price'. The ATO allows you to factor in a whole range of expenses to figure out your real profit. This is where a couple of key concepts come into play.
Key Terms You Need to Know
To really get how CGT works, you need to be comfortable with these core ideas:
- Capital Proceeds: This is the money you walk away with from the sale. It’s usually the contract sale price, but crucially, you get to subtract selling costs like real estate agent commissions and legal fees.
- Cost Base: This is probably the most powerful tool you have for minimising your tax bill. It’s not just the original purchase price. It also includes all the associated capital costs like stamp duty, conveyancing fees for the purchase, and the cost of any major improvements or renovations you’ve made over the years.
- Capital Gain or Loss: Your net capital gain is what’s left after you subtract the cost base from your capital proceeds. If you end up with a negative number, you’ve made a capital loss, which can be used to offset capital gains in the future.
The core principle is simple: the higher you can legitimately build your cost base, the lower your taxable capital gain will be. This is exactly why keeping meticulous records of every single expense related to buying and improving your property is so essential.
For a deeper dive, this essential guide to Capital Gains Tax on property is a great resource.
Getting on top of CGT early allows you to make strategic decisions long before you even think about putting the property on the market. One of the biggest strategies involves a powerful concession from the ATO. As you'll see, just holding your property for more than 12 months can slash your final tax bill thanks to the 50% CGT discount. We explore the timing of your sale and other strategic moves in our article on when you pay capital gains tax. A bit of forward planning can make a massive difference to your financial outcome.
How to Accurately Calculate Your Capital Gain or Loss
Working out the capital gains tax on your investment property isn't about getting tangled in complex algebra. At its heart, it's a simple process of addition and subtraction. Getting it right, however, is absolutely critical—both to stay on the right side of the ATO and to make sure you don't hand over a dollar more than you legally have to.
The whole calculation really boils down to three key numbers: your cost base, your capital proceeds, and the final gain or loss.
Think of it like working out the real profit you made from a side hustle. You wouldn't just look at the total sales; you’d carefully subtract all your setup costs and ongoing expenses first. Calculating your capital gain is exactly the same principle.
This diagram shows the straightforward, three-step flow of the calculation.
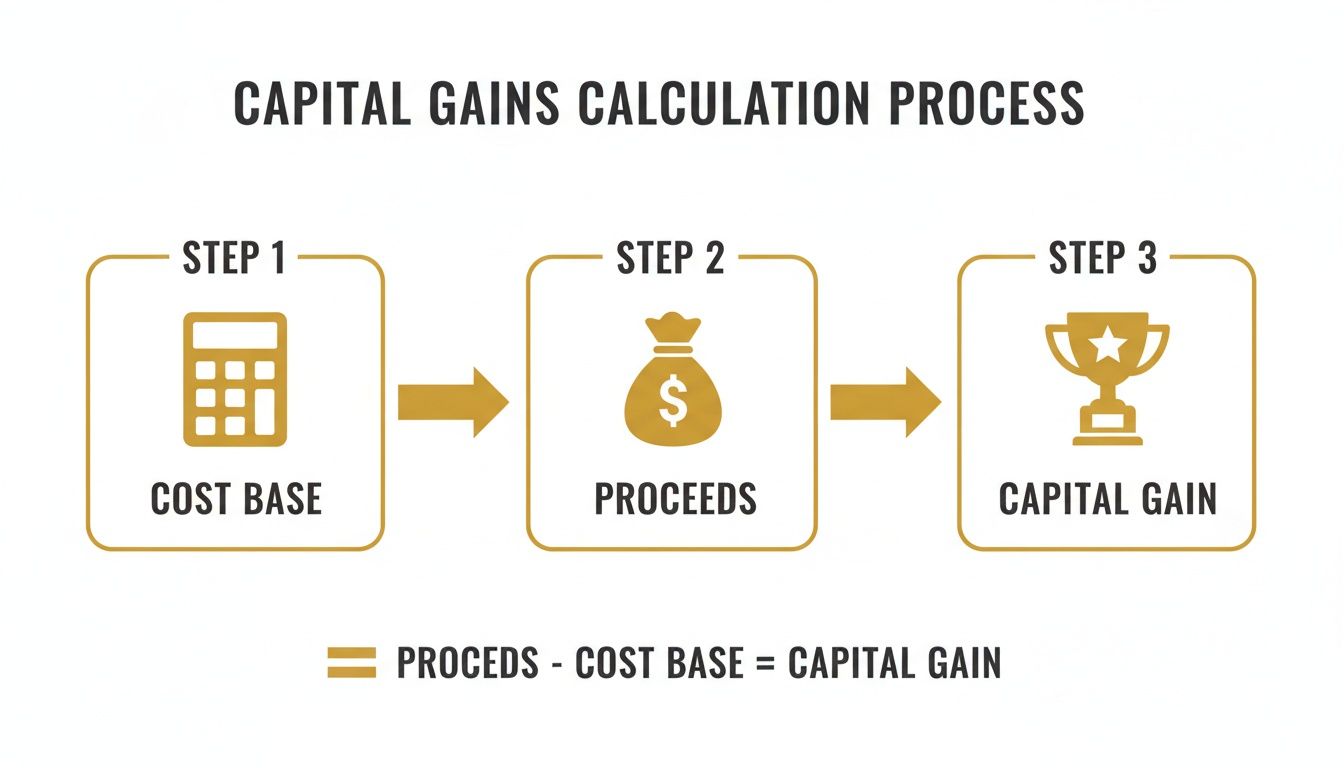
As you can see, the journey starts with locking down your costs, then defining what you walked away with from the sale, before finally arriving at the taxable figure.
Step 1: Build Your Property Cost Base
The cost base is the absolute foundation of your CGT calculation. More than that, it's your single most powerful tool for legally minimising your tax bill. It’s not just the purchase price; it's the grand total of every capital expense you've sunk into buying, holding, and improving the property over the years.
A truly comprehensive cost base is essential. Getting this right means you can significantly reduce your final capital gain, so it pays to be meticulous. Let's break down what goes into it.
The table below outlines the key elements that make up your property's cost base. Tracking these expenses diligently from day one can save you a small fortune when it's time to sell.
Key Components of Your Property's Cost Base
| Cost Element Category | Examples of Includable Expenses | Why It Matters |
|---|---|---|
| Initial Purchase Price | The final contract price you paid for the property. | This is the starting point for your calculation. |
| Acquisition Costs | Stamp duty, legal fees, conveyancing costs, buyer's agent fees, pest and building inspection reports. | These are significant upfront costs that directly increase your cost base. |
| Capital Improvement Costs | Major renovations (new kitchen/bathroom), adding a deck or extension, structural improvements, initial repairs to fix pre-existing defects. | These costs add to the property's value and your cost base, but routine maintenance doesn't count. |
| Title Costs | Legal fees related to preserving or defending your ownership or title of the property. | Any money spent legally protecting your asset can be included. |
| Disposal Costs | Real estate agent commissions, auction costs, advertising fees, legal fees for the sale. | These are the costs of selling, which are subtracted from your proceeds to reduce your final gain. |
By building a detailed and accurate cost base, you ensure that every legitimate expense works to reduce your final tax bill. It's the difference between paying tax on your true profit versus paying tax on an inflated figure.
Crucial point: You can't include any cost you've already claimed as a tax deduction during your ownership. Think things like interest on the investment loan, council rates, or repairs. This rule prevents "double-dipping" on tax benefits. For a deeper dive on what you can claim while you own the property, check out our guide on https://awts.net.au/blog/how-to-calculate-depreciation-on-rental-property/.
Step 2: Determine Your Capital Proceeds
Next up, you need to work out your capital proceeds. This is the total value you receive from selling your property.
For most people, this is simply the contract sale price. However, you don't stop there. You get to subtract the costs you paid to make the sale happen. This includes the real estate agent's commission, advertising fees, and any legal costs associated with the disposal. The figure you're left with is your net capital proceeds—the amount you truly pocketed.
Step 3: Calculate the Final Gain or Loss
Now it’s time to put it all together. The final step is beautifully simple:
Capital Proceeds - Cost Base = Total Capital Gain or Loss
If the result is a positive number, you’ve made a capital gain. If it's negative, you have a capital loss. You can’t claim a capital loss against your regular income, but you can use it to cancel out capital gains from other assets in the same year. If you have no other gains, you can carry it forward to offset future capital gains. To get this right, it's essential to understand how CGT on investment property is calculated in Australia.
For example, let’s say you sell a property for $1.2 million. Your cost base, after adding up the purchase price and all those eligible costs, is $500,000.
Your gross capital gain is $700,000. If you've held the property for more than 12 months, the 50% CGT discount kicks in, effectively halving your taxable gain. This means only $350,000 is added to your taxable income for the year. Assuming a marginal tax rate of 37%, your CGT bill would be around $129,500. Without that discount, you’d be looking at a staggering $259,000. It shows just how powerful the CGT discount can be.
Maximising the 50 Percent CGT Discount
When you wade into the world of selling investment property capital gains tax, the 50% CGT discount is easily the most powerful tool in the average Aussie investor's kit. It’s a major concession from the tax office that directly rewards a long-term, buy-and-hold investment strategy.
Simply put, this discount lets you chop your taxable capital gain clean in half. If you've made a decent profit on your property, applying this discount means only 50% of that gain gets added to your assessable income for the year. The difference this makes to your final tax bill can be monumental.
How to Qualify for the CGT Discount
The rules to get your hands on this discount are straightforward, but they are also incredibly strict. To unlock this massive tax saving, you have to meet two main conditions set by the Australian Taxation Office (ATO).
First up, the property must have been held for at least 12 months before you sign the contract of sale. This clock starts ticking from the date you acquired the asset and stops the moment you dispose of it. Timing is absolutely everything here—selling even one day short of that 12-month mark means you get nothing.
Secondly, the asset has to be owned by the right kind of entity. This includes:
- Individuals
- Trusts (including self-managed super funds)
- Partnerships
A Crucial Distinction: Companies are completely locked out of the 50% CGT discount. This is a vital point for investors who hold property inside a company structure. Understanding the tax implications of your ownership entity from day one is essential for any sensible tax planning.
This discount is a cornerstone of Australia's tax policy on investment. Analysis has shown that since it was introduced, the 50% CGT discount has resulted in forgone tax revenue of $247 billion over 25 years, a figure that highlights its immense value to investors. You can discover more insights into the financial impact of this tax concession on Accounting Times.
The Discount in Action: A Real-World Scenario
To really see the power of the 50% CGT discount, let’s walk through a clear before-and-after example. Imagine an investor named Chloe is getting ready to sell her investment property.
- Gross Capital Gain: Chloe works out her total capital gain is $200,000.
- Holding Period: She’s owned the property for five years.
- Her Marginal Tax Rate: Chloe's income puts her in the 37% tax bracket (plus the Medicare levy).
Now, let's see how the discount completely changes her tax outcome.
Scenario 1: Without the 50% CGT Discount
If Chloe wasn't eligible (let's say she sold after only 11 months), the full $200,000 capital gain would be tacked onto her taxable income. Her tax on this gain would be a painful $74,000 ($200,000 x 37%).
Scenario 2: With the 50% CGT Discount
Because Chloe was patient and held the property for over 12 months, she gets to apply the discount.
- Discount Applied: The $200,000 gain is slashed by 50%, leaving a taxable amount of $100,000.
- Tax Calculation: This $100,000 is added to her income. The tax on this much smaller gain is now only $37,000 ($100,000 x 37%).
Just by meeting that simple holding period rule, Chloe has pocketed an extra $37,000 in tax savings. This example shows exactly why strategic planning around that 12-month mark is so critical. It's a simple rule with a massive financial impact.
Finding Key CGT Exemptions and Concessions
While the 50% discount is a huge help, the Australian tax system has even more powerful tools to slash or completely wipe out your tax bill when you sell a property. Understanding the selling investment property capital gains tax rules becomes far more rewarding once you get your head around these key exemptions.
The biggest one by far is the main residence exemption. Put simply, your family home—the place you actually live—is generally exempt from Capital Gains Tax when you sell it. This rule makes sense; it acknowledges that your home is more than just a financial asset.
For property investors, though, things are rarely that straightforward. What happens if a property has served as both your home and an investment? This is exactly where a strategic understanding of the rules can save you tens of thousands of dollars.
The Main Residence Exemption Explained
At its core, the main residence exemption means you don't pay CGT on the sale of your primary home. To get the full exemption, the property must have been your main residence for the entire time you've owned it.
A couple of other conditions apply: the land around the home must be two hectares or less, and you can't have used the property to generate income. Tick all those boxes, and any capital gain you make is entirely tax-free.
But what if you've run a home business or, more commonly for investors, moved out and rented the place? This is where you might only qualify for a partial exemption. The ATO will need you to calculate the capital gain specifically for the period the property was used to earn an income. To dive deeper, you can learn more about how Australian capital gains tax exemptions work in practice.
The main residence exemption isn't an all-or-nothing rule. It's a flexible provision that can be applied partially, making it crucial for investors who have lived in their rental properties at some stage.
Getting the apportionment right between the exempt and non-exempt periods is absolutely vital for lodging an accurate tax return.
Unpacking the Powerful Six-Year Rule
This leads us to one of the most generous and frequently misunderstood provisions in Australian property tax: the six-year rule. This rule is a complete game-changer for anyone who has needed to move out of their home but wants to hold onto it as an investment.
In short, it allows you to move out of your main residence and rent it out for up to six years without losing the full main residence exemption. During that period, you can still treat the property as your home for tax purposes, meaning any capital gain that builds up during those rental years remains tax-free.
Of course, there are a few critical conditions:
- No Other Main Residence: You can't turn around and nominate another property as your main residence during that same period (with some minor exceptions for when you're moving between homes).
- Income-Producing Period: The six-year clock starts ticking the moment the property is first rented out.
- Multiple Absences: The best part? You can move back in, which resets the clock, and then use the six-year rule all over again for another absence down the track.
This provision offers incredible flexibility for modern life. It lets people take on work placements interstate or overseas, travel, or just try living somewhere new without being forced to sell their home to avoid a massive CGT bill later on.
Applying the Rules in a Real-World Scenario
Let's walk through how this works. Imagine you bought a home in 2018 for $600,000.
- Lived in it: You lived there as your main residence for four years, from 2018 to 2022.
- Rented it out: In 2022, you moved interstate for a new job and started renting the property out. You did this for three years.
- Sold it: In 2025, you decide to sell for $900,000, which gives you a total capital gain of $300,000.
Because your rental period of three years was well under the six-year limit, and you didn't purchase and nominate another main residence, you can apply the full main residence exemption. The entire $300,000 capital gain is completely tax-free.
Just by understanding this one rule, you've saved yourself a potential tax bill that could have easily topped $50,000.
Strategic Timing and Smart Record Keeping
When it comes to the selling investment property capital gains tax, a lot of the heavy lifting happens long before the "For Sale" sign goes up. It really boils down to two things you can actually control: when you sell and how well you’ve kept your records. This is where you move from just calculating tax to actively shaping your financial outcome.
Smart timing can literally shave thousands off your final tax bill. One of the most critical details people miss is that the CGT event is triggered on the date you sign the contract of sale, not the date of settlement. This small distinction opens up a huge window for strategic planning.
For example, if you know your income will be lower this financial year, you might hustle to exchange contracts before June 30. Conversely, if you expect a pay cut next year, delaying the contract signing until July 1 could be a game-changer. The goal is simple: have the capital gain added to your income in a year when your marginal tax rate is as low as possible.
The Power of the Calendar
Timing your sale isn't just about picking the right financial year; it's also about hitting key deadlines. The most famous one, of course, is holding the property for more than 12 months to qualify for that sweet 50% CGT discount. Selling just one day too early could literally double your tax liability. It’s a costly mistake to make.
Broader economic changes, like shifts in income tax brackets, also play a massive role. The Stage 3 tax reforms kicking in from July 2024 are a perfect example. Someone earning $120,000 who sells in the 2025 financial year will have their gain taxed at the new 30% rate, instead of the old 37%. That’s a huge difference, potentially saving thousands, purely by aligning the sale with more favourable tax laws. You can see a great breakdown of how the 2025 tax changes impact property sales with Amplify 11.
Your Non-Negotiable Record-Keeping Checklist
While timing is about strategy, meticulous record-keeping is the foundation everything is built on. Without proof, you can't add an expense to your cost base, and an incomplete cost base means you pay more tax than you need to. The Australian Taxation Office (ATO) can ask for evidence for every single dollar you claim, so keeping organised digital and physical records is simply non-negotiable.
Think of your records as a complete financial diary of the property. Start a folder the moment you even think about buying, and be religious about adding to it.
Your records are your ultimate defence against overpaying tax. Every receipt, invoice, and contract you keep is a tool that directly reduces your taxable capital gain, putting more of your hard-earned profit back in your pocket where it belongs.
Here is the definitive checklist of documents you absolutely must keep for at least five years after you lodge the tax return that includes the sale:
-
Acquisition Records:
- The original purchase contract.
- Conveyancing documents and all related legal fee invoices.
- Proof of stamp duty paid.
- Receipts for building and pest inspections.
-
Improvement Costs:
- Invoices and receipts for all capital works—think renovations, extensions, or any major structural improvements.
- Costs for initial repairs to fix defects that were there when you bought the place.
-
Holding Costs:
- Documents for legal fees if you ever had to defend your title to the property.
- Any loan application and mortgage discharge fees.
-
Disposal Records:
- The final contract of sale.
- Invoices for the real estate agent’s commission and advertising costs.
- Receipts for all legal fees tied to the sale.
This diligent approach ensures your cost base is as high and accurate as legally possible, which directly minimises the profit you’ll ultimately be taxed on.
When Your Former Home Becomes an Investment Property
Many investment properties started life as the owner's home. When you rent out a former main residence, special rules determine how much of any future capital gain is taxable.
Partial Exemption and the Market Value Rule
If a property was your home before becoming a rental, you are generally entitled to a partial main residence exemption for the period you lived there. Under the "home first used to produce income" rule, the property is typically deemed to have been acquired at its market value on the date you first rented it out — so a valuation at that point is essential. The six-year rule may also apply, potentially keeping the gain exempt for up to six years of rental. Getting the dates and valuations right here is where professional advice pays for itself.
Frequently Asked Questions About Selling and CGT
Once you get your head around the formulas for CGT, the real-world questions start popping up. It's one thing to know the principles of calculating tax, but how do they actually play out when you're in the thick of a property sale?
This is where the theory meets reality. Let's tackle some of the most common "what if" scenarios that investors face, so you can plan your sale with a clear head.
When Exactly Do I Pay the Capital Gains Tax?
This is easily one of the biggest points of confusion, especially for first-time sellers. Many people expect a separate tax bill to land in their letterbox shortly after the property settles.
But that’s not how it works. Your net capital gain is simply added to your assessable income for that financial year. You then pay tax on this new, higher total income when you lodge your annual tax return with the Australian Taxation Office (ATO). It’s all rolled into one.
The most important date to remember here is the contract of sale date, not the settlement date. The financial year you sign that contract is the financial year the gain is taxed in.
Can I Claim the Main Residence Exemption if I Rented My Home Out?
Yes, you often can, and this is where you can see the flexibility built into Australia’s tax laws. If the property was your primary home before you started renting it out, you can usually claim a partial exemption from CGT.
The ‘six-year rule’ is your best friend here. It’s a powerful provision that lets you treat the property as your main residence for up to six years after you’ve moved out, provided you’re using it to generate income (like renting it out).
Important Condition: The catch is that you cannot claim another property as your main residence during that same period. Get this right, and you can pocket some significant tax savings, even after the property has been an investment for years.
If you rented it out for more than six years, the exemption gets pro-rated. You’d calculate a partial gain based on the proportion of time it was an investment property versus your home.
What Happens if I Sell My Property at a Loss?
Selling for less than you paid results in a capital loss. While it’s disappointing, this loss is still a valuable asset for tax purposes. You just can’t use it to reduce your regular taxable income, like your salary.
Here’s the process:
- Offset Current Gains: First, you must use the capital loss to cancel out any other capital gains you’ve made in the same financial year. For instance, a loss on your property can wipe out a gain from selling some shares.
- Carry it Forward: If you don't have any other capital gains to offset, or your loss is bigger than your gains, the remaining loss can be carried forward indefinitely. You can then use it against capital gains in future years.
This means a loss today could still help reduce your tax bill on a different, successful investment years from now.
Are Ownership Costs Included in the Cost Base?
This is a crucial point to get right to avoid "double-dipping" on tax deductions. The general rule is you cannot include ongoing ownership costs in your cost base if you have already claimed them as tax deductions against your rental income.
These are your typical running expenses:
- Interest on the investment loan
- Council and water rates
- Land tax
- Insurance premiums
- Property management fees
- Repairs and maintenance
Your cost base is reserved for capital costs—the big-ticket items related to buying, significantly improving, and selling the property. Trying to include expenses you've already claimed is a surefire way to attract unwanted attention from the ATO.
How Does CGT Work for Inherited Properties?
Inheriting a property throws another layer of complexity into the mix. The tax rules depend heavily on when the deceased bought the property and what it was used for.
- Pre-CGT Asset (Acquired before 20 September 1985): If you inherit a property the deceased purchased before this date, you might be completely exempt from CGT when you sell it, as long as it wasn't used to produce income.
- Post-CGT Asset (Acquired on or after 20 September 1985): If the property was the deceased's main home, you’re generally exempt from CGT if you sell it within two years of their passing.
- Investment Property: If you inherit a rental property, you also inherit its cost base. When you sell, your capital gain or loss is calculated from what the deceased originally paid, not its value when you received it.
Given how tricky this can get, getting professional advice for an inherited property is always a smart move to ensure everything is handled correctly.
Depreciation reduces an asset's cost base. When you sell, previously claimed Division 40 depreciation triggers a balancing adjustment. For Division 43 capital works deductions claimed from 1 July 2017, the amount reduces the building's cost base, increasing the eventual capital gain. The interaction between depreciation and CGT requires careful calculation at time of sale.
A quantity surveyor prepares a tax depreciation schedule by physically inspecting the property and identifying all depreciable assets and their values. The ATO accepts these estimates for depreciation claims where original receipts are unavailable. The fee is tax deductible. A schedule maximises your annual depreciation claims based on a comprehensive site assessment.
Division 43 covers the capital works deduction on structural components (walls, floors, roof) at 2.5% per year for buildings constructed after 15 September 1987. Division 40 covers plant and equipment (appliances, carpet, blinds) depreciated over their ATO-determined effective life. Post-May 2017 legislation restricts Division 40 claims on second-hand residential assets for new buyers.
Yes. The May 2017 restrictions on second-hand plant and equipment only apply to residential properties. Commercial property investors can still claim Division 40 depreciation on second-hand assets. Division 43 capital works deductions apply to both property types based on construction date, not acquisition date.
Keep the purchase contract, settlement statement, receipts for capital improvements, and a quantity surveyor's depreciation schedule. The ATO can request these records for five years after the relevant income year. Without records, depreciation claims can be reduced or disallowed on audit, and you may lose the ability to substantiate cost base adjustments at sale.
Navigating the specifics of selling investment property capital gains tax requires careful planning and a clear understanding of the rules. To ensure you maximise your return and meet all your ATO obligations, professional guidance is invaluable. The experts at Australia Wide Tax Solutions specialise in property tax and can help you develop a strategy that minimises your tax liability.
Don't leave your hard-earned profits on the table. Contact us today for personalised advice at https://www.awts.net.au.
A franked dividend is a payment you receive as a shareholder from an Australian company that has already paid tax on its profits. The real magic, though, is the franking credit that comes attached—think of it as a pre-paid tax voucher just for you.
- Why Franked Dividends Exist: Solving the Double Taxation Problem
- Putting Franking Credits To Work: A Practical Example
- How to Claim Franking Credits on Your Tax Return
- Navigating the Modern Landscape of Franked Dividends
- Answering Your Top Questions About Franked Dividends
Essentially, the company has already settled a portion of your tax bill on that dividend income before it even hits your bank account.
What Are Franked Dividends in Simple Terms?
Let's break it down. Imagine a company you've invested in makes a profit. Before it can share that profit with its shareholders, it first has to pay company tax to the Australian Taxation Office (ATO). A franked dividend is simply your slice of the pie after the company has paid its tax.
The entire system was created to fix one huge problem for investors: double taxation. Without it, a company's profit would be taxed once at the corporate level, and then you'd get taxed on it again when you receive your dividend. Franking credits put a stop to that.
The core idea is simple yet powerful: company profits should only be taxed once, at the shareholder's marginal tax rate. Franking credits are the mechanism that makes this possible, ensuring a fairer and more efficient tax system for investors.
This process is a game-changer. It turns what could be a tax headache into a tax-effective way to earn investment income. For many Aussies trying to build passive income with dividend stocks, understanding franked dividends is the key to a successful strategy.
Fully Franked vs Unfranked Dividends
Now, not all dividends are the same. The amount of tax a company has paid on its profits determines whether your dividend is fully franked, partially franked, or unfranked. Each one affects your tax situation differently.
A fully franked dividend means the company paid tax at the full corporate rate (currently 30% for large companies) on the profit it's sharing with you. A partially franked dividend means only some tax was paid. And an unfranked dividend means no Australian tax was paid on those profits at all, which often happens when the profits were earned overseas.
You can dive deeper into how different dividends pay tax in Australia in our detailed guide.
Franked vs Unfranked Dividends at a Glance
To make it even clearer, this table breaks down the key differences between the types of dividends you might receive. It’s a quick way to see how each one impacts your bottom line.
| Dividend Type | Company Tax Paid? | Franking Credit Attached? | Impact on Shareholder's Tax |
|---|---|---|---|
| Fully Franked | Yes, at the full corporate rate. | Yes, a full credit is attached. | Significantly reduces your personal tax payable, may result in a refund. |
| Partially Franked | Yes, but at less than the full rate. | Yes, a partial credit is attached. | Reduces your personal tax payable, but less than a fully franked dividend. |
| Unfranked | No Australian tax paid. | No, there is no credit attached. | The full dividend amount is added to your taxable income and taxed at your marginal rate. |
This distinction is absolutely crucial because it directly shapes your after-tax return. As we'll get into, your personal tax rate is what ultimately determines whether these credits mean you pay less tax or even get a cash refund from the ATO.
Why Franked Dividends Exist: Solving the Double Taxation Problem
To really get your head around franked dividends, you first need to understand why they even exist. They’re not just some quirky feature of the Aussie market; they were a purpose-built solution to a major headache that used to plague shareholders: double taxation.
Picture this: before 1987, the system was seriously flawed. A company would make a profit and, quite rightly, pay company tax on it. But when it shared what was left with its owners (the shareholders) as a dividend, those investors had to pay income tax on that exact same money all over again.
That meant a single dollar of profit was getting taxed twice—once in the company's hands, and a second time in the shareholder's. This created a huge drag on investment returns and gave companies very little incentive to pay dividends. It just wasn't fair.
The Fix: Australia’s Dividend Imputation System
Recognising how inefficient this was, the Australian government rolled out the dividend imputation system in 1987. The goal was simple but powerful: make sure that company profits paid out to Australian shareholders are only taxed once, at that shareholder's personal tax rate.
This completely changed the game for local investors. It effectively got rid of the double taxation penalty and created one of the most shareholder-friendly dividend systems in the world. The magic ingredient? Franking credits. When a company pays tax on its profits, it generates these credits, which it can then "impute" or attach to the dividends it pays out.
At its heart, the dividend imputation system is about fairness. It treats the tax paid by the company as a pre-payment of tax on behalf of its shareholders. It’s like the company has already taken care of a chunk of your tax bill for you.
This clever setup directly connects the tax paid by a company to the tax its owners owe. For Australian resident investors, it makes the whole process far more transparent and equitable.
How It Stops Double Taxation in its Tracks
The process itself is quite straightforward, but the impact is massive. Let’s follow a dollar of profit from the company’s bank account to yours.
- A Company Earns a Profit: An Australian company makes $100 in pre-tax profit.
- The Company Pays Tax: Assuming a 30% corporate tax rate, the company pays $30 in tax to the ATO. This leaves it with $70 of after-tax profit.
- A Dividend is Paid: The company decides to pay out this entire $70 to you as a fully franked dividend.
- A Franking Credit is Attached: Here’s the key part. Along with the $70 in cash, the company attaches a $30 franking credit—the exact amount of tax it already paid on that original profit.
When it comes to your tax return, you have to declare the full pre-tax amount of $100 as income (your $70 cash dividend + the $30 franking credit). But the good news is, you also get a $30 tax credit to lower your final tax bill. That’s the mechanism that prevents the tax from being paid twice.
Australia's dividend imputation system, introduced in 1987, fundamentally changed how dividends are taxed. It was specifically designed to solve the problem where companies paid tax on earnings at the corporate rate of 30%, and then shareholders paid tax again on the dividends they received. By attaching franking credits, the system allows you to offset your personal income tax liabilities, which can even result in refunds from the ATO. You can explore more about how analysts view these high-dividend strategies on S&P Global.
Putting Franking Credits To Work: A Practical Example
Understanding the theory behind franked dividends is one thing, but seeing how they actually hit your tax return is where it all clicks. Let’s walk through a real-world, step-by-step calculation to see just how much these tax credits can affect your bottom line.
First, we have to tackle a concept called 'grossing up' the dividend. It sounds complicated, but it’s not. Before you work out the tax, you simply add the value of the franking credit back to the cash dividend you received. This total amount represents the company's full, pre-tax profit that your dividend was paid from, and it’s this 'grossed-up' figure you declare as income.
The Core Calculation
Imagine you own shares in an Australian company and receive a fully franked dividend payment of $700 in cash. Nice.
Let's say the company pays tax at the corporate rate of 30%. To figure out the franking credit attached to your dividend, we use a straightforward formula:
Franking Credit = (Cash Dividend Amount / (1 - Company Tax Rate)) - Cash Dividend Amount
Plugging our numbers in:
($700 / (1 - 0.30)) - $700 = ($700 / 0.70) - $700 = $1,000 - $700 = $300
So, your $700 cash dividend comes with a $300 franking credit. Your total 'grossed-up' dividend income for tax purposes is now $1,000. This is the amount you'll add to your assessable income on your tax return.
This flowchart shows how that profit flows from the company, through the tax system, and finally to you as a dividend with the tax credit already attached.
As you can see, the tax the company paid on its profits is passed directly to you, the shareholder, as a franking credit.
How Your Tax Rate Changes Everything
Now for the magic. The final result—whether you pay more tax, break even, or get a refund—boils down to how your personal marginal tax rate stacks up against the 30% corporate tax rate the company already paid.
Let's run the numbers for three different investors, all receiving the same $1,000 grossed-up dividend.
To make this crystal clear, here’s a quick summary of how the same franked dividend impacts investors on different tax rates.
Franking Credit Impact by Marginal Tax Rate
| Investor's Marginal Tax Rate | Tax on Grossed-Up Dividend ($1,000) | Franking Credit Offset | Final Outcome (Tax Payable / Refund) |
|---|---|---|---|
| 47% (High-Income Earner) | $470 | -$300 | $170 Tax Payable |
| 32.5% (Middle-Income Earner) | $325 | -$300 | $25 Tax Payable |
| 19% (Low-Income Earner/Retiree) | $190 | -$300 | $110 Tax Refund |
Let's break down each of those scenarios.
Scenario 1: The High-Income Earner (47% Marginal Tax Rate)
An investor in the top tax bracket still gets a huge benefit, but the credit doesn't cover their entire tax bill on the dividend.
- Total Taxable Income: $1,000
- Tax Payable Before Credit (at 47%): $1,000 x 0.47 = $470
- Less Franking Credit: -$300
- Final Outcome: $170 Tax Payable
Without the franking credit, this investor would have owed $470. Instead, they only need to pay the $170 difference—a massive saving. If you want a deeper dive into how do franking credits work, our detailed guide has you covered.
Scenario 2: The Middle-Income Earner (32.5% Marginal Tax Rate)
For someone whose tax rate is just a touch above the corporate rate, the system works to almost completely wipe out their tax bill.
- Total Taxable Income: $1,000
- Tax Payable Before Credit (at 32.5%): $1,000 x 0.325 = $325
- Less Franking Credit: -$300
- Final Outcome: $25 Tax Payable
In this case, the investor only pays a tiny "top-up" tax of $25. The company has already covered the vast majority of their tax liability for them.
Scenario 3: The Low-Income Earner or Retiree (19% Marginal Tax Rate)
This is where the dividend imputation system really flexes its muscles. For investors with a marginal tax rate lower than the company’s, the outcome isn’t just zero tax—it’s a cash refund from the ATO.
- Total Taxable Income: $1,000
- Tax Payable Before Credit (at 19%): $1,000 x 0.19 = $190
- Less Franking Credit: -$300
- Final Outcome: $110 Tax Refund from the ATO
Because the investor's tax liability ($190) is less than the tax credit ($300), the ATO refunds the $110 difference directly to them. This makes fully franked dividends an incredibly powerful source of income for retirees and people on lower incomes.
How to Claim Franking Credits on Your Tax Return
Receiving a franked dividend is a fantastic perk for any investor, but the real magic only happens when you correctly claim the credits on your annual tax return. This isn't just about ticking a box; it's about understanding your dividend statements and navigating a few key eligibility rules set by the Australian Taxation Office (ATO).
Think of it like this: the company has handed you a tax voucher. It's now your job to cash it in with the ATO. Getting this right is what turns a good investment return into a great one, either by slashing your tax bill or landing a welcome refund.
Decoding Your Dividend Statement
First things first, you need to know where to find the right information. Whenever a company pays you a dividend, you'll get a dividend statement, either in the mail or electronically. This little document is your treasure map for tax time.
It contains all the crucial figures, but you have to know what you’re looking for. Keep an eye out for these specific items:
- Cash Dividend Paid: This is the actual amount of money that hit your bank account.
- Franking Credit (or Imputation Credit): This is the value of the tax credit the company has passed on to you.
- Franked Amount: The portion of your cash dividend that has a franking credit attached.
- Unfranked Amount: Any portion of the dividend that came without a credit.
Here's the most important step: you must add the cash dividend and the franking credit together. This "grossed-up" figure is what you declare as assessable income. It might seem strange to declare more income than you received, but it’s the only way to claim the credit. For a deeper dive, check out our guide on dividend tax in Australia.
Meeting the Key Eligibility Rules
Before you can claim those valuable credits, the ATO has a few conditions you need to meet. The biggest one is the holding period rule, which you’ll often hear called the "45-day rule." This rule is there for one reason: to stop people from buying shares just before a dividend is paid and selling them straight after simply to pocket the credit—a tactic known as "dividend stripping."
To satisfy the rule, you have to hold the shares "at risk" for a continuous period of at least 45 days. This period doesn't include the day you buy or the day you sell. For some preference shares, this extends to 90 days.
The "at risk" part is absolutely critical. It means you must be genuinely exposed to the financial ups and downs of owning the shares. If you use certain financial products to protect yourself from any loss in the share's value during that time, the ATO might decide you weren't truly "at risk" and deny your claim to the credits.
This rule makes sure that the benefits of the dividend imputation system go to genuine, long-term investors, not short-term opportunists.
Exceptions to the Holding Period Rule
Thankfully, the ATO applies some common sense for smaller investors, making the process much simpler.
You are generally exempt from the 45-day rule if you're an individual investor and your total franking credit entitlement for the entire financial year is less than $5,000. This is known as the "small shareholder exemption," and it covers the vast majority of everyday retail investors.
There are a couple of other specific situations where the rule doesn't apply:
- The shares were acquired through an employee share scheme.
- The shares were inherited as part of a deceased estate.
These exceptions cut out a layer of complexity for most people. But it's vital to stay aware of the rules. If your portfolio grows and your total franking credits climb over that $5,000 threshold, you'll need to make sure you meet the holding period for all your dividend-paying shares.
Navigating the Modern Landscape of Franked Dividends
While the tax benefits of franked dividends are compelling, finding them isn't as simple as just picking any stock on the ASX. The reality is, not every company offers these tax-effective payments, and the landscape has become more concentrated than many investors first assume.
Knowing where to look is the first step in building a portfolio that generates that reliable, tax-advantaged income stream investors are chasing.
Historically, you could find fully franked dividends across a pretty broad range of industries. These days, however, they are heavily concentrated among the big, established "blue-chip" companies. We're talking about businesses that make most of their profits right here in Australia—think major banks, leading retailers, and telecommunication giants.
These are the companies paying significant Australian corporate tax, which is the very thing that fuels the franking credit system. Their stable, profitable operations give them the capacity to consistently share these tax credits with their shareholders.
Why Some Companies Offer Limited Franking
On the flip side, you'll often come across companies paying partially franked or completely unfranked dividends. This isn't necessarily a red flag or a sign of a struggling business. More often than not, it's just a reflection of where their profits are being made.
A classic example is a company with significant overseas earnings. Many of Australia’s biggest names in resources and healthcare, for instance, generate a huge chunk of their revenue abroad. Because they pay corporate tax in those foreign countries, not to the ATO, they simply don't build up a large balance of franking credits to pass on to their Australian shareholders.
Key Takeaway: The level of franking on a dividend is a direct signal of how much Australian tax a company has paid. High domestic profits typically mean high franking levels, while large international operations often lead to unfranked dividends.
Understanding this distinction is crucial. It helps you set realistic expectations and avoids the disappointment of investing in a globally successful Australian company, only to find it doesn't offer the same tax perks as a domestic-focused bank.
A Concentrated Market for Franked Dividends
The pool of companies consistently paying fully franked dividends has become increasingly focused. As you get to grips with the opportunities franked dividends present, it's smart to explore broader dividend investing strategies to ensure your approach is well-diversified.
As of December 2024, the landscape has become even more concentrated. While 111 members of the S&P/ASX 300 index pay fully franked dividends, the distribution of this income is incredibly top-heavy. By July 2025, it's projected that just ten companies will account for a massive 55% of all dividends paid by the S&P/ASX 200 index.
This isn't a random trend. It reflects broader economic shifts, with declining earnings in parts of the Australian corporate sector and company boards growing more cautious in an uncertain climate. For many, maintaining those high levels of fully franked dividends investors have come to expect is getting tougher.
This data really drives home an important lesson for investors: relying on just a handful of big names for your franked income creates a serious concentration risk in your portfolio. While these blue-chip stocks are popular for good reason, a truly robust strategy involves looking beyond the obvious choices to build a more resilient and diversified income stream.
Answering Your Top Questions About Franked Dividends
As you get more familiar with how franked dividends work, a few specific questions tend to bubble up. The concepts can feel a bit complex at first, but once you grasp the underlying logic, the answers are surprisingly straightforward. Let's tackle some of the most common queries we hear from investors.
A big one we get asked about is what happens when you choose to reinvest dividends instead of taking the cash. It’s a common worry – do you miss out on the franking credits?
Do I Get Franking Credits with a Dividend Reinvestment Plan?
Yes, you absolutely do. When you're enrolled in a Dividend Reinvestment Plan (DRP), the Australian Taxation Office (ATO) treats the transaction as if you received the cash dividend and its franking credits first.
You’re still required to declare the full, grossed-up dividend as income on your tax return, exactly the same as any other dividend. That cash portion is then simply used to buy more shares on your behalf. It’s a common point of confusion, but remember: forgoing the cash payout doesn't mean you forgo the tax credit.
Why Would a Company Pay an Unfranked Dividend?
Seeing an unfranked or partially franked dividend from a company you own usually boils down to one simple reason: the company hasn't paid enough Australian corporate tax to attach credits to the full dividend. This is very common for businesses that earn a large chunk of their profits overseas.
Because they pay taxes in other countries, they don't build up a big enough franking credit balance here in Australia to pass on. Another possibility is that the company has carried-forward tax losses, which have wiped out its local taxable income for the period.
A dividend's franking level is a direct signal of how much Australian tax the company has recently paid. Think of it as a transparent clue about where its profits are being taxed.
This is a really important distinction to understand when you're managing your expectations about how tax-effective your different investments will be.
What Is the Small Shareholder Exemption?
The ATO has a handy rule in place designed to make life a little easier for investors with smaller portfolios. If your total franking credit entitlement for the entire financial year is less than $5,000, you are generally exempt from the 45-day holding period rule.
This rule normally requires you to hold shares "at risk" for a minimum period to be eligible for the credits. The exemption means you can claim your credits without having to worry about that specific condition. It’s a practical measure that simplifies tax time for most everyday Aussie investors. Just be aware, this exemption won't apply if you've set up a special arrangement to pass the dividend benefits on to someone else.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
Getting your head around the details of franked dividends is the key to maximising your investment returns. At Australia Wide Tax Solutions, our experts help investors navigate their tax obligations with confidence, ensuring you claim every single credit you're entitled to. Contact us for personalised tax advice today.
When you sell your home for a profit, the fantastic news is that most Australians don't pay a cent of capital gains tax. This is all thanks to the Main Residence Exemption, a powerful rule designed to protect your family home from the taxman. But, as with most things tax-related, the situation gets a bit more complicated if the property was an investment or used to earn an income.
- Your Guide to Capital Gains Tax on Selling a Home
- The Main Residence Exemption Explained
- How to Calculate Capital Gains Tax on Your Property
- Navigating Partial Exemptions and Special Cases
- Strategies to Legally Minimise Your CGT Bill
Your Guide to Capital Gains Tax on Selling a Home
Let's cut through the jargon. Think of Capital Gains Tax (CGT) as simply a tax on the profit you make when you sell a valuable asset for more than you paid for it. When it comes to property, that "cost" isn't just the purchase price; it also includes a whole range of other expenses we'll get into.
For the vast majority of Aussie homeowners, selling the family home is a completely tax-free event. This exemption is the cornerstone of our property tax system, making sure the wealth you build in your primary home stays yours.
However, CGT becomes a very real consideration in a few common scenarios. You'll almost certainly need to get your head around the rules if you're:
- Selling an investment property you've been renting out.
- Selling a holiday home that was never your main residence.
- Selling a home where you also ran a business.
- Selling a property you inherited, depending on the circumstances.
When CGT Applies to Your Home Sale at a Glance
To make it even clearer, here's a quick summary of when you're likely to encounter CGT.
| Property Scenario | Is CGT Likely to Apply? | Key Consideration |
|---|---|---|
| Selling your family home (main residence) | No | You've lived in it continuously since purchase. |
| Selling a rental property | Yes | The property was used to generate income. |
| Selling a home you lived in, then rented out | Partial | You'll likely pay CGT for the period it was rented. |
| Selling a property you inherited | It depends | Was it the deceased's main residence? When did you sell? |
| Selling a "fix and flip" property | Yes | This is often treated as business income, not a capital gain. |
This table is just a starting point, of course. The specifics of your situation will always determine the final outcome.
The Basic Idea of Capital Gains
At its heart, the concept is pretty straightforward. The Australian Taxation Office (ATO) is interested in the difference between what you sold your property for and what it cost you to buy, hold, and sell it. This profit is your "capital gain," which then gets added to your taxable income for that financial year.
It's crucial to understand that CGT isn't a separate tax. Instead, the net capital gain from your property sale is included in your income tax return and taxed at your personal marginal rate. This distinction can make a huge difference to the final tax bill.
To get a complete picture, it’s useful to know how the ATO views profits from different property activities. For example, there's a big tax difference between a long-term investment and a quick 'flip'. For anyone interested in that side of things, understanding taxes for flipping houses provides some great context on when profits are seen as capital gains versus regular business income.
Core Concepts to Get Started
Before we get into the nitty-gritty, let's lock down two key terms you'll see again and again. Getting these right is the first step to an accurate calculation.
- Capital Proceeds: This is the money you walk away with from the sale. It's usually just the selling price, but you get to subtract certain direct costs, like the real estate agent's commission and the legal fees for the sale.
- Cost Base: This is where things get a bit more detailed. It starts with the original purchase price, but you also add a range of other expenses. Think stamp duty, legal fees from when you bought it, and the cost of major capital improvements like a new kitchen or an extension.
The simplest way to think about it is as a basic subtraction sum: Capital Proceeds – Cost Base = Capital Gain (or Loss). Our goal in this guide is to break down each part of that equation so you can navigate the rules with confidence.
The Main Residence Exemption Explained
For most Aussie homeowners, the phrase "capital gains tax" is something that happens to other people. That's because of a cornerstone in our tax system called the main residence exemption. It's the single most important rule that lets you sell your family home and walk away with the profit, completely tax-free.
But what actually makes a house your "main residence"? It's not just about the address on your driver's licence. The Australian Taxation Office (ATO) wants to see that it's genuinely your home base.
They’ll look at a few practical things to connect the dots:
- Do you and your family actually live there?
- Is that where you keep your personal belongings?
- Is it the address your mail gets sent to?
- Are you on the electoral roll at that address?
- Are the utility bills, like electricity and gas, in your name?
Here’s a crucial point: you can only have one main residence at any given time. If you own a few properties and split your time between them, you have to nominate just one as your main residence for tax purposes. You can't claim the exemption on two places at once.
Understanding the Temporary Absence Rule
Life happens. Maybe you get a great job offer interstate, decide to travel the world for a year, or just want to try living somewhere else for a bit. This is where the temporary absence rule, often called the "six-year rule," is an absolute game-changer.
This rule lets you move out of your home, rent it out, and generate income for up to six years without losing the full main residence exemption. The catch is you can't buy and treat another property as your main residence during that period. Even better, if you move back in before the six years is up, the clock resets, and you can rent it out again later for another six-year stretch.
This is a powerful strategy for homeowners needing to relocate temporarily. It means you can have a tenant paying your mortgage while your property's tax-free status is preserved, giving you incredible financial flexibility.
The Six-Year Rule in Action
Let’s run through a quick example to see how it works on the ground.
Sarah and Tom bought their home in Melbourne in 2018 and lived in it as their main residence. In 2022, Tom landed a four-year work contract in Brisbane. Instead of selling, they decided to rent out their Melbourne place and rent a home for themselves in Brisbane.
- 2022: They pack up and their Melbourne home gets its first tenants.
- 2026: Tom's contract finishes, and they move back into their Melbourne house.
- 2028: They decide it's time to sell.
Because they moved back within the six-year window and didn't buy another home to live in, they can treat their Melbourne house as their main residence for the entire time they owned it. The result? The whole capital gain from the sale is completely exempt from CGT. For a more detailed breakdown, our guide on the capital gains tax main residence exemption has you covered.
But what if they'd stayed in Brisbane for seven years before selling? The exemption would no longer fully apply. In that scenario, they'd be up for a partial CGT bill, calculated on the period the property was income-producing after that initial six-year grace period. It just goes to show how critical timing and knowing these rules are.
How to Calculate Capital Gains Tax on Your Property
Figuring out the capital gains tax on your property sale might feel a bit daunting, but it’s really just a logical, step-by-step process. If you break it down, you can get a really clear picture of what your tax bill might look like. The whole calculation hinges on three key stages: nailing down your cost base, working out your capital proceeds, and then calculating the final gain.
This isn’t as simple as subtracting what you paid from what you sold it for. It’s about being meticulous and accounting for every legitimate cost along the way to make sure you’re only paying tax on your actual profit.
Stage One: Understanding Your Cost Base
The first—and most important—step is to calculate your property's cost base. This number represents the total amount the property has cost you from the day you bought it to the day you sold it. A common mistake is thinking the cost base is just the purchase price, which can lead to a nasty surprise in the form of a much bigger tax bill.
Your cost base is actually the sum of a few different parts:
- The purchase price: This is the straightforward one—the original amount you paid for the property.
- Incidental costs of buying: Think back to when you first bought the home. This includes things like stamp duty, legal fees, and conveyancing costs.
- Capital improvements: This is where you account for major upgrades that added lasting value. We're talking about a new kitchen, adding a deck, or building a room extension—not minor repairs.
- Ownership costs: In some situations, you can include costs like council rates, insurance, and interest on your home loan. This generally only applies if the property was bought after 20 August 1991 and you haven’t already claimed these costs as a tax deduction (for instance, against rental income).
- Costs of selling: This covers the final expenses, like real estate agent commissions, legal fees, and any advertising costs you paid to sell the property.
It’s absolutely vital to keep detailed records of every single one of these expenses. Why? Because a higher cost base directly reduces your capital gain, which means less tax to pay.
Stage Two: Determining Your Capital Proceeds
Once your cost base is locked in, the next piece of the puzzle is determining your capital proceeds. In plain English, this is the money you receive from selling your property.
For most sales, the capital proceeds will simply be the sale price listed on the contract. But you are allowed to subtract the direct costs of the sale itself. This typically includes the real estate agent's commission and the legal fees for handling the sale. What’s left is your net proceeds.
The Calculation in a Nutshell:
Capital Proceeds (Sale Price - Selling Costs)
MINUS
Cost Base (Purchase Price + Buying Costs + Improvements)
EQUALS
Your Gross Capital Gain
This simple bit of maths gives you your total, or gross, capital gain. But hold on—this isn't the final number the ATO taxes you on. The next step is where a massive tax-saving opportunity comes into play for anyone who has held their property for a decent amount of time.
Stage Three: Applying the 50% CGT Discount
Here’s where a bit of patience really pays off. The Australian tax system rewards long-term property investors with a very powerful tax break: the 50% CGT discount.
If you're an Australian resident individual and have owned the property for more than 12 months, you can slash your calculated capital gain in half. This is, without a doubt, the most effective way to minimise the capital gains tax you’ll pay.
Let's say you owned an investment property for a few years and sold it, making a capital gain of $100,000 after all your costs are accounted for. Because you held it for more than 12 months, you qualify for that all-important 50% discount. This instantly cuts your taxable gain down to just $50,000. That's the figure that gets added to your other income for the year and taxed at your marginal rate. You can dive deeper into how CGT applies to investment properties on liviti.com.au.
This flowchart gives you a simple visual of how to think about the main residence exemption, which is always the first thing to consider before you even start calculating.
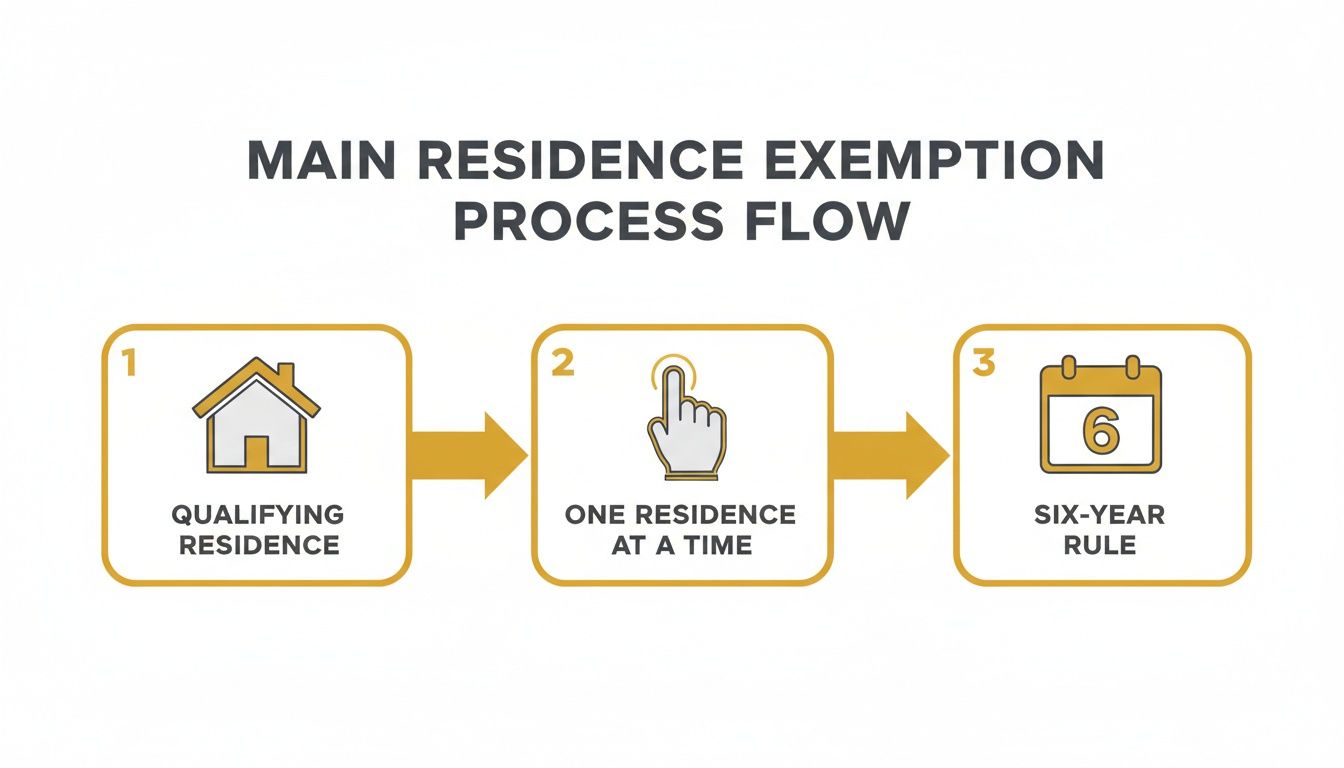
As you can see, checking if your property qualifies, making sure you only have one main residence at a time, and knowing about things like the six-year rule are the foundational concepts you need to get right.
Of course, here is the rewritten section, crafted to sound completely human-written and natural, following the style of the provided examples.
CGT is not a separate tax — a capital gain is included in your assessable income for the year a CGT event occurs. It applies when you dispose of a CGT asset including shares, investment properties, business assets, and cryptocurrency. Your primary residence is generally exempt, though partial exemptions apply in specific circumstances.
The capital gain is capital proceeds (sale price) minus the cost base. The cost base includes purchase price, stamp duty, legal fees, and capital improvement costs. If the asset was held for more than 12 months, apply the 50% CGT discount to reduce the gain before adding it to taxable income. Keep all acquisition records from the purchase date.
Australian resident individuals and trusts that have held a CGT asset for more than 12 months can reduce their capital gain by 50% before inclusion in assessable income. Superannuation funds receive a one-third discount. Companies do not qualify. The holding period begins on the purchase date and ends on the disposal contract date.
Shares are CGT assets. When you sell shares, the gain or loss is proceeds less cost base (purchase price plus brokerage). Gains on shares held more than 12 months qualify for the 50% discount. Capital losses can only offset capital gains — they cannot reduce other income. Carry forward unused losses to offset future gains.
The main residence exemption can entirely or partially exempt the gain from selling your home. Full exemption applies if the property was your main residence throughout the ownership period, was never used to produce income, and sits on land of two hectares or less. Partial exemption applies where it was rented or used for business during part of the ownership period.
Navigating Partial Exemptions and Special Cases
The main residence exemption is wonderfully straightforward when a property has only ever been your family home. But life is rarely that simple.
What happens when your home doubles as your workplace, or you start renting out a spare room to help with the mortgage? In these situations, the tax-free status of your home sale can become partial, meaning a portion of your capital gain suddenly becomes taxable.
Think of your home's tax-free status like a whole pie. If you use a part of it to earn an income, the Australian Taxation Office (ATO) considers that you've cut out a slice for business purposes. When you sell, the "family home" part of the pie is still exempt from tax, but the "business slice" is now on the table for capital gains tax.
This is a really common scenario for many Australians, especially with the rise of remote work and the gig economy. The key is understanding how to correctly portion out the gain so you only pay tax on what you absolutely have to.
When Your Home Is Also Your Workplace
Using part of your home to run a business or renting out a room directly affects your main residence exemption. If you've ever claimed tax deductions for "interest on your home loan" or other running costs against your business income, you will almost certainly face a partial CGT bill when you sell.
The ATO needs you to figure out the taxable portion based on two key factors:
- Floor Area: You have to work out the percentage of your home's total floor area that was used for income-producing activities. For example, if your dedicated home office takes up 10% of your home's floor space, that’s your starting point.
- Time Period: You also need to calculate the exact period you used the space to earn an income. If you ran the business from home for five of the ten years you owned the property, you’ll need to account for that timeframe.
The taxable part of your capital gain is then calculated based on a blend of both the space and the time it was used for business.
Calculating the Taxable Portion
Let's run through a quick example. Imagine you sell your home and make a capital gain of $200,000. You used a home office, which makes up 15% of the house's floor area, to run a business for the entire 8 years you owned the property.
In this simplified case, 15% of your capital gain would be subject to CGT.
- Taxable Portion: $200,000 (Total Gain) x 15% (Business Use Area) = $30,000
This $30,000 is your gross capital gain. And because you've owned the home for more than 12 months, you can then apply the 50% CGT discount, reducing your taxable gain to just $15,000.
This apportionment principle is crucial. It ensures you’re not unfairly taxed on the part of your home you genuinely lived in, while still accounting for the slice that helped you earn an income and claim deductions.
Other Complex Scenarios to Consider
Partial exemptions aren't just for home businesses. Other special cases can complicate your capital gains tax on selling a home, often needing careful calculations and professional advice.
For instance, inheriting a property comes with its own set of rules. The CGT implications depend on when the deceased bought it, whether it was their main residence, and how long you hold onto it before selling. Similarly, if you move into a home you previously rented out, you can't just wipe the slate clean. You’ll need to get a market valuation of the property at the time it first became your main residence, as this value is used to calculate the cost base for your tax-exempt period.
The property market's performance makes these calculations even more significant. For example, CoreLogic data shows Sydney dwelling values recently climbed 1.1% in a single quarter. With forecasts suggesting further rises, a partial CGT liability on a property could represent a substantial sum, making accurate calculations absolutely essential. You can explore more about these trends and their impact in this Australian housing market update from parisfinancial.com.au.
Given the complexities, getting it right is paramount.
Strategies to Legally Minimise Your CGT Bill
Getting the best sale price for your property is only half the battle. The other half is making sure you keep as much of that profit as you legally can.
While paying tax on a capital gain is non-negotiable, there are several legitimate, ATO-approved strategies you can use to reduce your final bill. These aren’t sneaky loopholes; they’re simply the result of smart, forward-thinking financial decisions. By understanding the rules and planning ahead, you can make sure you don't pay a dollar more in tax than necessary.
Hold Your Property for Over 12 Months
Without a doubt, the single most powerful strategy for cutting down your CGT bill is patience. If you're an Australian resident and you hold an investment property for at least 12 months before selling, you unlock the 50% CGT discount.
This is a game-changer. It allows you to slash your taxable capital gain in half, straight off the top. So, if you've calculated a capital gain of $80,000, holding the property for that extra day over the 12-month mark instantly reduces your taxable gain to just $40,000. It’s the cornerstone of managing capital gains tax on selling a home that isn’t your main residence.
The CGT discount is a major wealth-building tool, though it's worth noting its impact. Data from the Parliamentary Budget Office shows the discount heavily favours high-income earners. In 2022–23, a staggering 24,000 millionaires received nearly half of the entire discount's benefit, which gives you an idea of its power.
Time the Sale Strategically
Here’s a crucial detail many people miss: your capital gain is taxed in the financial year you sign the sale contract, not when you settle. This small detail opens up a massive strategic opportunity to time your sale to fall in a year when your other income is lower.
Think about these scenarios:
- Nearing Retirement: Selling after you've officially stopped working could mean your gain is taxed at a much lower marginal rate.
- Taking a Career Break: If you're planning to take a sabbatical or switch to part-time work, that financial year might be the perfect window to sell.
- Launching a Business: In the early years of a start-up, personal income is often much lower, creating an ideal tax environment for a property sale.
By aligning the sale with a lower-income year, you ensure the gain doesn't push you into a higher tax bracket, potentially saving you thousands.
Another smart move is to maximise your deductions in the year of sale. Making a strategic contribution to your superannuation, for example, can be a highly effective way to lower your total taxable income, which in turn reduces the tax hit from your capital gain.
Maximise Your Cost Base
A higher cost base means a lower capital gain. It’s that simple. But so many property owners make the mistake of thinking the cost base is just the purchase price, leaving thousands of dollars in legitimate expenses on the table.
You need to be meticulous. Track and include every single allowable expense to build up your cost base. This includes more than you might think:
- Initial buying costs like stamp duty, legal fees, and buyer's agent fees.
- Major capital improvements, such as renovations, adding an extension, or significant landscaping projects.
- Selling costs, including real estate agent commissions, styling, and advertising fees.
Every receipt you keep for a capital improvement could save you real money when it comes time to sell. For a deeper dive into managing your tax obligations, it's worth exploring general tax planning strategies.
When it comes to tax, planning is everything. Our team can help you navigate all the available options. Check out our detailed article for more on how to reduce capital gains tax.
Essential Record Keeping For A Smooth Tax Return
When it comes to capital gains tax, meticulous records are your best friend. Seriously. They're your best defence against overpaying the Australian Taxation Office (ATO) and your greatest tool for saving money.
Think of your records as the building blocks for your property’s cost base. Every receipt and invoice you save can potentially increase this base, which in turn directly reduces your taxable capital gain. A shoebox of faded receipts is better than nothing, but a well-organised file—digital or physical—is the key to a stress-free tax season.
Your Essential Document Checklist
From the day you even start thinking about buying a property to the day you sell it, you should be collecting documents. These records are absolutely crucial for accurately calculating the capital gains tax on selling a home.
Make sure you keep a clear trail of the following:
- Purchase Documents: This includes the original contract of sale, settlement statements, and receipts for things like stamp duty and your solicitor's fees.
- Improvement Costs: Got invoices for capital improvements? Keep them. This means significant upgrades like a kitchen renovation, adding a deck, or building an extension—not minor repairs like fixing a leaky tap.
- Ownership Costs: Where applicable, you'll need records of council rates, land tax, and the interest you've paid on your home loan.
- Selling Documents: Gather the final contract of sale, settlement statements, and receipts for the real estate agent's commission, legal fees, and any advertising costs.
The ATO requires you to keep these documents for the entire time you own the property, plus another five years after you lodge the relevant tax return. For a more detailed breakdown, our guide on which tax records to keep has you covered.
Good records do more than just satisfy the ATO. They empower you to make informed financial decisions and ensure you claim every legitimate cost you are entitled to, maximising your final profit from the sale.
How To Report Your Capital Gain
Once you have all your records in order and have crunched the numbers to find your net capital gain, the final step is reporting it on your annual tax return. A key point here: you report it in the financial year that you sign the contract of sale, not the year the sale finally settles. This catches a lot of people out.
In the myTax portal, you'll head to the "Capital gains or losses" section. This is where you'll input the key details from your calculations, including your total capital proceeds and the property's all-important cost base.
The system will then prompt you to apply any relevant discounts, like the 50% CGT discount if you've owned the property for more than 12 months. The final number is your net capital gain, which gets added to your assessable income for the year and is then taxed at your marginal rate.
Got More Questions About CGT on Property?
Working through the capital gains tax rules often brings up a few tricky "what if" scenarios. When your situation isn't a simple buy-and-sell, things can get complicated. Let's tackle some of the most common questions property owners ask.
What Happens If I Make a Capital Loss on My Property?
It's a tough pill to swallow, but sometimes you have to sell a property for less than what you paid for it. When this happens, you’ve made a capital loss. While it’s certainly not the outcome you hoped for, this loss has a very specific purpose in the eyes of the tax man.
You can't use a capital loss to reduce your regular taxable income, like your salary from work. Instead, you have to use it to offset any capital gains you’ve made from other assets in the same year. If you don't have any gains to offset, the loss isn't gone for good. You can carry it forward indefinitely to wipe out capital gains in future years, which is why it's so important to report every loss to the ATO.
Do I Pay CGT on an Inherited Property?
The tax rules for inherited properties can be a real maze, and the answer depends entirely on the history of the property. For example, if the person who left you the property bought it before CGT even existed (pre-20 September 1985), you might be completely exempt if you sell it within two years.
A similar two-year grace period often applies if the property was the deceased's main residence right up until they passed away. But if it was their investment property, you effectively step into their shoes and inherit their original cost base. CGT is then calculated on the growth from that point when you eventually decide to sell. Given how many variables are at play, this is one area where getting professional tax advice is a very smart move.
Inheriting a property doesn’t mean an automatic tax bill. The critical factors are how the deceased used the property and how quickly you act on selling it. Getting your head around these conditions is the key to managing any potential CGT you might face.
Can I Avoid CGT by Moving Into My Rental Property Before Selling?
It’s a common idea: move into your rental property for a while, call it your home, and then sell it tax-free. While this strategy can definitely reduce your CGT, it's not a magic loophole that will wipe the slate clean.
The ATO looks at the entire time you owned the property and requires a proportional calculation. You'll need to figure out the total capital gain over your ownership period and then split it. The gain is apportioned based on the number of days it was rented out versus the days it was your genuine main residence. You'll still pay CGT for the period it was an investment, but the gain attributed to the time you lived there will be exempt.
For Australian homeowners, the capital gains tax main residence exemption is easily the most valuable tax break available. It’s the rule that allows you to sell your family home and walk away with every dollar of profit, completely free from capital gains tax (CGT). The catch? It had to be your genuine home for the entire time you owned it and wasn't used to generate income.
The Foundations of the Tax-Free Family Home
At its core, this exemption is a powerful ‘tax-free shield’ protecting the everyday Aussie homeowner. The principle is pretty straightforward: the government gets that your home is a necessity, not just another investment on a spreadsheet. Because of this, any growth in its value shouldn't be taxed when you decide to sell.
This is a cornerstone of Australian property and tax law, offering a huge amount of financial security. It means that when the time comes to sell your home—whether you’re downsizing, moving for work, or freeing up equity—the profit you’ve patiently built over the years is yours to keep.
Why This Exemption Matters So Much
The financial impact of getting this right is massive. For most people, their home is their biggest asset, and the capital growth it racks up over a decade or two can be genuinely life-changing. Without this exemption, a huge chunk of that profit could disappear in tax, derailing retirement plans and putting a serious dent in your financial future.
Let’s look at a real-world example. Say you bought your family home in Sydney back in 2013 for $700,000. You lived in it as your main residence for a full decade before selling it in 2023 for a cool $1.2 million. That’s a $500,000 capital gain, and thanks to this rule, every cent of it is tax-free. This powerful protection is laid out in section 118-110 of the Income Tax Assessment Act 1997.
This is exactly why understanding the rules is so critical. The value at stake is enormous, and a simple mistake can lead to an unexpected and very painful tax bill.
Key Takeaway: The main residence exemption isn't just a minor perk; it's a fundamental principle designed to protect the wealth you build in your home. For many, it literally saves hundreds of thousands of dollars in tax.
To help you get a clear picture of the core requirements, here’s a quick summary of what it takes to qualify for the full exemption.
Main Residence Exemption At a Glance
| Eligibility Requirement | What It Means | Example |
|---|---|---|
| It must be your main residence | The property must be the genuine centre of your domestic life. You live there with your family and keep your personal belongings there. | Your family home where you live day-to-day, receive mail, and are on the electoral roll. |
| You can only have one main residence at a time | You (and your spouse) can't claim the exemption on two properties for the same period. | If you own a city apartment and a beach house, you must choose one as your main residence for any given period. |
| The dwelling must be on land of two hectares or less | The exemption generally only covers your home and adjacent land up to 2 hectares (about 5 acres). | A standard suburban block is well within this limit. A large rural property might need a partial exemption calculation. |
| The property must not have been used to produce income | If you used part of your home to earn income (e.g., renting out a room or running a business), you may only get a partial exemption. | If you never ran a business from home or had a tenant, you meet this condition. |
While this table covers the basics, life is rarely that simple.
Setting the Stage for Success
To lock in this tax-free benefit, you have to tick all the boxes set by the Australian Taxation Office (ATO). While the core idea is simple enough, real-life scenarios often throw a spanner in the works.
For example:
- What if you own a holiday house and a city apartment?
- What happens if you rent out a room on Airbnb or run your consultancy from the study?
- How does moving overseas for a few years affect the exemption?
These are all common situations that can complicate things, potentially reducing your full exemption to a partial one. Throughout this guide, we’ll break down these essential criteria, navigate the special rules, and highlight the traps to avoid. For a broader look at the tax relief available to property owners, you can explore our detailed article about other capital gains tax exemptions in Australia. Getting it right means you can take full advantage of this generous rule and make smarter financial decisions.
Qualifying for the Full Tax Exemption
Securing the full, tax-free main residence exemption all comes down to one simple question: was the property genuinely your home? The Australian Taxation Office (ATO) looks for more than just your name on the title deed; they want to see that the dwelling was the true centre of your domestic life. Think of it less like ticking a box and more like building a case.
To convince the ATO that a property was your main residence, you need to show it’s where you and your family actually lived day-to-day. They’ll look at a handful of practical, real-world factors to paint a clear picture.
Passing the Main Residence Test
There’s no single, magic-bullet factor that proves a property is your main residence. Instead, the ATO considers the whole story based on your personal circumstances. The key indicators are all about where your life is anchored:
- Where Your Family Lives: Does your spouse and do your children live at the property with you?
- Where Your Mail is Delivered: Is this the address you use for your bank statements, bills, and other important mail?
- Your Presence on the Electoral Roll: Is this the address where you are registered to vote?
- Connection to Services: Are the utilities—electricity, gas, internet—connected in your name at this address?
- Where Your Belongings Are Kept: Are your personal effects and valuable possessions stored at the property?
Basically, you need to show that this address is your home base. If you're spending most of your time somewhere else, it becomes a much tougher argument to win.
The Two-Hectare Land Limit
The main residence exemption doesn't just cover the house itself. It also extends to the land it sits on, but there’s a firm boundary. The exemption covers your dwelling and any adjacent land up to a maximum of two hectares (that's about five acres).
For most people living in a typical suburban block, this rule won't even be on their radar. But if you own a larger rural or semi-rural property, this limit is absolutely critical to understand.
If your land is larger than two hectares, you can still get the full exemption on your home and the surrounding two hectares that you use for private or domestic life. The rest of the land, however, will be hit with CGT when you sell. You'll have to calculate the capital gain on that excess portion separately.
Core Conditions for a Full Exemption
Beyond passing the 'main residence' test and staying within the land limit, two fundamental conditions must be met for the entire time you owned the property. Getting either of these wrong can slash your full exemption down to a partial one, leaving you with an unexpected tax bill.
1. You Lived in It for the Entire Ownership Period
To get the full exemption, the property had to be your main residence from the day you settled the purchase right through to the day you signed the contract to sell it. If there was any period you lived somewhere else—for example, you bought it and rented it out for a year before moving in—that period won't qualify for the exemption.
2. You Did Not Use It to Produce Income
This is the big one—the tripwire for so many homeowners. If you've used any part of your home to earn an income, you risk losing some of your exemption. This is a big deal if you've been:
- Renting out a spare room or the whole house (including short-term rentals on platforms like Airbnb).
- Running a business from home and claiming tax deductions for a specific, dedicated office space.
Important Note: Just working from home at the kitchen table generally won't cause any problems. The issue kicks in when you formally claim home office expenses as a tax deduction, because that’s you telling the ATO that a portion of your home was used for income-producing purposes.
Nailing all these conditions means you can sell your home and walk away with the profits, completely tax-free. But if your situation has a few more moving parts, you’ll likely be looking at a partial exemption instead.
Calculating a Partial Main residence Exemption
Real life rarely fits neatly into clean tax rules. While a full exemption from Capital Gains Tax is what everyone hopes for, it’s common for a property to serve different purposes over the years you own it.
Maybe you rented it out for a few years before moving in yourself. Or perhaps you used a room exclusively as a home office to get your business off the ground.
In these common scenarios, the Australian Taxation Office (ATO) doesn't just disqualify you from the exemption entirely. Instead, you can often claim a partial main residence exemption. This means you only pay Capital Gains Tax (CGT) on the slice of the capital gain that relates to the time the property wasn't your main home.
How Does a Partial Exemption Work?
Think of your ownership period as a timeline. The ATO essentially draws a line on that timeline, separating the days the property was your genuine home from the days it was used to earn income. The tax-free shield only covers the days it was your main residence.
This is where the apportionment calculation comes in. It’s a formula the ATO uses to fairly split the total capital gain between its exempt and non-exempt periods. Getting your head around this calculation is the key to figuring out your potential tax bill. For a deeper look at how CGT works on property, check out our detailed guide on capital gains tax on property.
This flowchart breaks down the basic tests your property needs to pass to be considered your main residence for any given period.
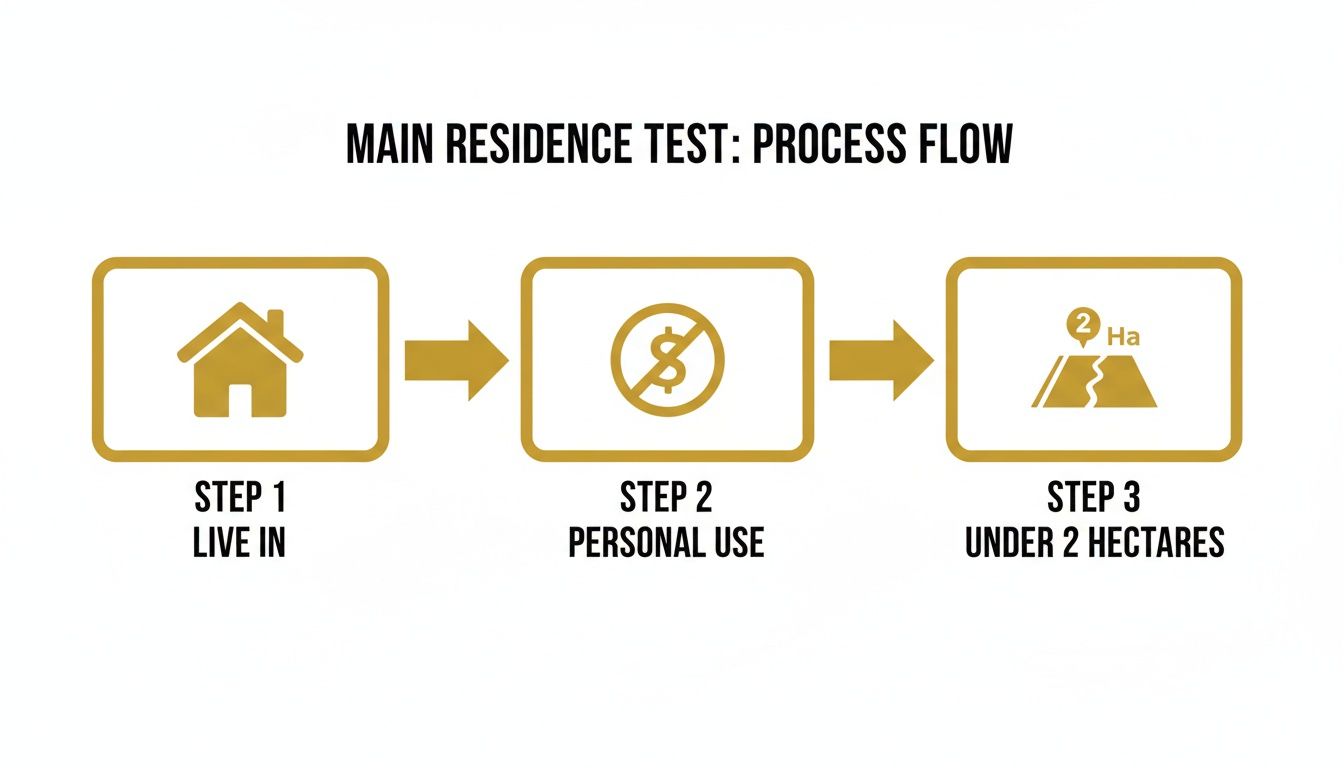
As it shows, to qualify you need to actually live in the property, use it for personal enjoyment rather than to make money, and the land must be under two hectares.
Step-by-Step Apportionment Calculation
The formula itself can look a bit intimidating at first glance, but it makes a lot more sense when you walk through a real-world example.
The basic formula is:
Total Capital Gain x (Number of Non-Main Residence Days / Total Days of Ownership) = Assessable Capital Gain
Let’s put this into a story.
Example: A Homeowner's Journey
Imagine Sarah bought a house on 1 July 2014 for $500,000. She lived in it as her main home for exactly five years.
- Ownership Start: 1 July 2014
- Main Residence Period: 1 July 2014 to 30 June 2019 (1,826 days)
On 1 July 2019, she moved out and rented the property to tenants for the next five years.
- Income-Producing Period: 1 July 2019 to 30 June 2024 (1,827 days)
On 1 July 2024, she sells the house for $900,000, making a total capital gain of $400,000. Her total ownership period was 3,653 days (a neat 10 years).
Here’s how we apply the formula to Sarah's situation:
- Calculate the Total Capital Gain:
- Sale Price: $900,000
- Cost Base: $500,000
- Total Capital Gain: $900,000 - $500,000 = $400,000
- Identify the Non-Exempt Period:
- The property was rented out for 1,827 days. This is the part of the timeline that's taxable.
- Apply the Apportionment Formula:
- $400,000 (Total Gain) x (1,827 Non-Main Residence Days / 3,653 Total Ownership Days) = $200,082
So, in this case, Sarah’s assessable capital gain is $200,082. The other half of the gain, roughly $199,918, is completely tax-free thanks to the main residence exemption.
The Financial Significance of This Exemption
The main residence exemption isn't just a small tax break; it’s one of Australia’s most significant. Treasury estimates show it resulted in $47.5 billion of forgone revenue in 2023–24—a figure larger than the entire Defence budget.
This benefit largely flows to established homeowners. Research indicates that nearly 90% of the financial benefit goes to the top half of income earners, while those who rent or are on lower incomes receive no direct advantage.
Understanding this calculation is crucial for anyone who has rented out their home, even for a short time. It allows you to plan for a potential tax liability and avoid any nasty surprises when it comes time to sell.
Navigating Special Rules and Life Events
Life rarely stays still. A new job offer overseas, a family inheritance, or the breakdown of a relationship can turn your world upside down—and your tax situation along with it. When your home is involved, these major life events can create tricky scenarios for the capital gains tax main residence exemption. Get it wrong, and you could be staring down an unexpected and hefty tax bill.
Thankfully, the ATO has built in several special rules to handle these exact situations. Knowing how they work is the key to protecting your exemption when your life takes an unexpected turn.
The Powerful Six-Year Absence Rule
Of all the special provisions, the six-year absence rule is one of the most valuable tools available to homeowners. It’s like a pause button for your main residence status. It lets you move out of your home—even rent it out and earn an income—and continue treating it as your tax-free main residence for up to six years.
This rule is a lifesaver for anyone who needs to relocate temporarily. Think of an overseas work assignment, an interstate secondment, or even an extended trip. You get the flexibility to generate rental income from your property without immediately exposing it to capital gains tax.
There’s just one critical catch: you can’t treat any other property as your main residence during that same period. If you buy and move into a new place while renting out the old one, you have to choose which property gets the CGT exemption for that overlapping time. You can’t double-dip.
Key Insight: The six-year absence rule isn't something that happens automatically. It’s a choice you make when you lodge your tax return for the year you sell the property. This gives you the power to look back and apply the exemption to whichever property delivers the better tax outcome.
Understanding the Six-Year Rule in Practice
When applied correctly, this rule can save homeowners a fortune. Picture a professional who buys a home, lives in it for a couple of years, and then lands a dream job contract overseas. This is the classic scenario where the six-year absence rule becomes a game-changer.
The financial impact is huge. Let's look at Chloe's situation. She bought a Melbourne home for $800,000 in 2022 and lived in it for two years. In 2024, she took a job in London and rented out her home. Her contract ends in 2029, and after five years away, she decides to sell the property for $1.3 million.
Thanks to the six-year rule, she could pocket the entire $500,000 capital gain completely tax-free, provided she didn't nominate another home as her main residence while she was gone. You can find more detail on this powerful ATO provision in recent tax research.
Comparing Key Special Rules
To help you get a quick handle on these provisions, here’s a simple table comparing the most common scenarios.
| Special Rule | Key Condition | Potential CGT Outcome |
|---|---|---|
| Six-Year Absence Rule | You don't nominate another property as your main residence during the absence. | Full exemption for up to six years while the property is income-producing. |
| Inherited Main Residence | You sell the property within two years of the deceased's passing. | Full exemption is often available if it was the deceased's home and not used for income. |
| Divorce/Separation Rollover | Ownership is transferred between spouses as part of a relationship breakdown. | No immediate CGT. The original cost base is "rolled over" to the receiving partner. |
This table is just a starting point, as each rule has its own set of detailed conditions. It's always best to get advice tailored to your specific circumstances to make sure you're ticking all the right boxes.
Inheriting a Main Residence
When you inherit a property that was the main residence of the person who passed away, a special set of CGT rules comes into play. The tax treatment isn't one-size-fits-all and hinges on a few key questions:
- Was the property the deceased's main residence right before they died?
- Was it being used to produce income at that time?
- How long do you hold onto it before selling?
As a general guide, if you sell the inherited property within two years of the person's death, you can often claim a full main residence exemption. If you hold it for longer than two years, you’ll likely face a partial CGT bill, calculated from the date of death.
Divorce or Separation
A relationship breakdown is tough enough without adding a massive tax bill to the mix. The family home is usually the biggest asset to be divided, and special ‘rollover’ rules are designed to prevent an immediate CGT event during this difficult time.
These rules allow the main residence to be transferred from one partner to the other without triggering any capital gains tax at the time of the transfer. The original cost base of the property simply "rolls over" to the receiving partner, deferring any CGT liability until the property is eventually sold down the track.
This is a critical provision that prevents separating couples from being forced into a fire sale just to cover an immediate and often unmanageable tax bill. The partner who keeps the house effectively inherits its entire CGT history.
Essential Record Keeping and Common Pitfalls
Claiming the capital gains tax main residence exemption isn’t as simple as ticking a box. The Australian Taxation Office (ATO) works on a "show, don't tell" basis, and they expect you to have the proof to back up your claim. Without the right paperwork, your exemption could be challenged, leaving you with a massive and completely unexpected tax bill.
Think of your records as the evidence that validates your property's story. Keeping a meticulous file is your best defence against ATO scrutiny and the only way to ensure you can confidently apply the rules to your unique situation. This goes way beyond just the purchase and sale contracts; it’s about documenting the entire life of the property under your ownership.
Your Essential Documentation Checklist
To properly support your main residence exemption claim, you need a solid file of documents. It’s a whole lot easier to collect these as you go rather than trying to dig them up years down the track when memories are fuzzy and paperwork is lost.
Your file must include:
- Proof of Ownership: This is the obvious one. Keep the contracts of sale for both the purchase and sale of the property, along with all conveyancing documents.
- Cost Base Records: Hang on to receipts for every cost tied to buying, holding, and selling the property. This means stamp duty, legal fees, agent commissions, and—crucially—the costs of major capital improvements like that new kitchen or extension.
- Proof of Residency: This is where you prove the "main residence" part of the claim. Gather documents like utility bills, bank statements, and any other mail showing your name at that address. Being on the electoral roll for that address is also powerful evidence.
- Income-Producing Periods: If you rented out the property or ran a business from a home office, you absolutely must keep detailed records. We’re talking rental agreements, property manager statements, and clear records of all income earned and expenses claimed.
Key Takeaway: The ATO can go back several years to review your tax affairs. As a non-negotiable rule, you must keep organised records for at least five years after you sell your property.
Common Mistakes That Jeopardise Your Exemption
Even homeowners with the best intentions can stumble into traps that put their tax-free exemption at risk. Knowing what these common pitfalls are is the first step to making sure you don't make a costly mistake.
Here are some of the most frequent blunders we see:
- Nominating the Wrong Property: If you own more than one property, you can only claim one as your main residence at any given time. A classic mistake is continuing to claim the old family home after you’ve already bought and moved into a new place. You have to make a choice.
- Miscalculating Income-Producing Periods: People often forget that renting out a room on Airbnb or claiming home office deductions officially turns part of their home into an income-producing asset. Failing to calculate the partial capital gain for these periods is a major red flag for the ATO.
- Ignoring Foreign Residency Rules: The rules for Australian expats and foreign residents have tightened significantly. In most cases, if you are a non-resident for tax purposes when you sign the contract to sell your property, you may lose the main residence exemption entirely, even for the years you did live in it.
- Forgetting the Two-Hectare Limit: If your home is on a block of land larger than two hectares, the exemption gets limited. You must calculate CGT on the portion of land that exceeds this limit.
Avoiding these errors comes down to careful planning and being honest about how you’ve used your property. Getting it right from the start protects this valuable tax break and gives you total peace of mind when it’s finally time to sell.
How to Get Expert CGT Guidance
Figuring out the rules for the capital gains tax main residence exemption can feel like you're walking through a minefield. One wrong step could easily cost you tens, or even hundreds, of thousands of dollars. As this guide shows, what seems simple on the surface gets complicated fast with life events, renting out a room, or special tax conditions. Frankly, getting it wrong is a risk you can’t afford to take.
This is exactly where getting professional advice becomes a non-negotiable. An expert can cut through the dense ATO legislation and give you clear, practical steps for your exact situation—whether you're a homeowner, a seasoned property investor, or an Aussie living overseas. They make sure you’re applying the rules correctly and squeezing every last drop out of the tax benefits available to you.
Personalised Strategies for Property Owners
No two property journeys are the same, and your tax advice shouldn't be either. At Australia Wide Tax Solutions, we live and breathe property and capital gains tax, providing specialised guidance that fits your unique circumstances.
Our services are designed to give you clarity and confidence, including:
- Accurate CGT Calculations: We handle the tricky apportionment for partial exemptions, making absolutely sure you only pay the tax you legally owe.
- Strategic Rental Property Advice: We’ll help you understand the tax impact of earning rental income from your home, now or in the past.
- Tax Planning for Property Sales: Before you even think about selling, we identify opportunities to minimise your tax bill and protect your hard-earned profit.
Don’t leave your biggest asset to chance. A proactive approach to tax planning means you’re fully prepared. You can go into your property sale with complete peace of mind, knowing your financial future is secure.
The rules are detailed, but you don't have to become an expert overnight. For support tailored to your property goals, take a look at our capital gains tax services and book a chat with our experienced team today.
The Six-Year Rule Explained
One of the most valuable features of the main residence exemption is the "six-year rule." If you move out of your home and rent it out, you can continue to treat it as your main residence for capital gains tax purposes for up to six years.
How the Six-Year Rule Works
During that period, a sale can still be fully exempt from CGT — provided you are not claiming another property as your main residence at the same time. If you move back in and leave again, the six-year period resets. If the property is left vacant rather than rented, the exemption can apply indefinitely. This rule makes it possible to relocate for work or family reasons without immediately losing your exemption, but the "only one main residence at a time" condition is the common trap.
Common Questions Answered
When you're dealing with the main residence exemption, a lot of specific "what if" scenarios pop up. It's one of the most common areas we get questions about. Here are some straightforward answers to the tricky situations homeowners often face.
Can I Have Two Main Residences at the Same Time?
No, you can't. The Australian Taxation Office (ATO) is very clear on this: for any single period, you can only nominate one property as your main residence.
Even if you own and live in multiple homes—say, a city apartment for the work week and a house on the coast for weekends—you have to pick one. That choice determines which property gets the tax-free exemption for that specific timeframe. This becomes really important when you sell one of them, as you'll need to declare which periods it was your main residence to work out if you owe any CGT.
What if My Land is Bigger Than Two Hectares?
The full exemption is capped at a dwelling and its adjacent land up to a maximum of two hectares (which is about five acres). If your property is larger than this, it doesn't mean you lose the whole exemption, but it does get a bit more complicated.
You can still claim the full exemption on your home and the two hectares you use most for private purposes. However, the capital gain on the rest of the land will be subject to CGT. You'll need to get a formal valuation to figure out what portion of the sale price is tied to that excess land so you can calculate the taxable gain correctly.
Heads Up: This two-hectare rule is a hard limit. It doesn't matter if local council zoning prevents you from subdividing and selling the extra land separately. For tax purposes, the ATO still treats that excess area as a separate asset.
Does Working from Home Affect My Exemption?
This is a big one, and the answer is: it depends on how you use your home for work. If you're just using a home office or have your laptop set up on the dining table, you generally have nothing to worry about. The ATO knows this is just part of modern life and it won’t affect your capital gains tax main residence exemption.
The situation changes when you start claiming business expenses for your home's running costs—things like a portion of your mortgage interest, council rates, or home insurance. By claiming these deductions, you're officially telling the ATO that part of your home was used to produce income. That's the trigger that will almost certainly lead to a partial CGT bill when you sell.
Do I Owe CGT if I Knock Down and Rebuild My Home?
Usually, no. If you demolish your main residence to build a new one on the same block of land, you can continue treating the property as your main residence right through the construction period.
The ATO gives you a handy concession here. It allows you to treat the vacant land as your main residence for up to four years, as long as you move into the new home as soon as it's practical to do so. This is a lifesaver, ensuring you don't lose your valuable exemption while the builders are on site. Just make sure you keep meticulous records of all the building costs, as they'll become part of the cost base for your new home.
Getting the main residence exemption right can save you a fortune, but a small mistake can be costly. The team at Australia Wide Tax Solutions lives and breathes this stuff, helping homeowners and investors get the best possible tax outcomes while staying fully compliant.
For advice tailored to your specific situation, book a consultation!
CGT is not a separate tax — a capital gain is included in your assessable income for the year a CGT event occurs. It applies when you dispose of a CGT asset including shares, investment properties, business assets, and cryptocurrency. Your primary residence is generally exempt, though partial exemptions apply in specific circumstances.
The capital gain is capital proceeds (sale price) minus the cost base. The cost base includes purchase price, stamp duty, legal fees, and capital improvement costs. If the asset was held for more than 12 months, apply the 50% CGT discount to reduce the gain before adding it to taxable income. Keep all acquisition records from the purchase date.
Australian resident individuals and trusts that have held a CGT asset for more than 12 months can reduce their capital gain by 50% before inclusion in assessable income. Superannuation funds receive a one-third discount. Companies do not qualify. The holding period begins on the purchase date and ends on the disposal contract date.
Shares are CGT assets. When you sell shares, the gain or loss is proceeds less cost base (purchase price plus brokerage). Gains on shares held more than 12 months qualify for the 50% discount. Capital losses can only offset capital gains — they cannot reduce other income. Carry forward unused losses to offset future gains.
The main residence exemption can entirely or partially exempt the gain from selling your home. Full exemption applies if the property was your main residence throughout the ownership period, was never used to produce income, and sits on land of two hectares or less. Partial exemption applies where it was rented or used for business during part of the ownership period.
If you make a $100,000 capital gain in Australia — from selling an investment property, shares, or other CGT asset — the tax you pay depends on your other taxable income, whether you held the asset for more than 12 months, and whether any cost base deductions apply. In 2026, a $100,000 capital gain can result in anywhere from $0 to $45,000+ in additional tax depending on your circumstances. Here is exactly how the calculation works.
The 50% CGT Discount: The Most Important Variable
If you held the asset for more than 12 months before the disposal (selling date), you are entitled to the 50% CGT discount. This reduces your taxable capital gain from $100,000 to $50,000 — halving the tax you pay. The discount is available to individuals and trusts (not companies). Foreign residents cannot access the discount on gains accrued after May 2012.
Tax Calculation: $100,000 Gain, Held Under 12 Months
Without the 50% discount, the full $100,000 gain is added to your other taxable income and taxed at your marginal rate:
- Income of $80,000 + $100,000 gain = $180,000 total — the $100,000 is split across the 32.5% and 37% brackets, resulting in approximately $35,000-$37,000 in additional tax
- Income of $50,000 + $100,000 gain = $150,000 total — gain is taxed across 32.5% and 37% brackets, approximately $32,000-$35,000 in additional tax
- Income of $130,000 + $100,000 gain = $230,000 total — gain is entirely in the 45% bracket, approximately $45,000 in additional tax
Tax Calculation: $100,000 Gain, Held Over 12 Months
With the 50% discount, only $50,000 is added to your taxable income:
- Income of $80,000 + $50,000 discounted gain = $130,000 total — additional tax of approximately $16,250-$17,500
- Income of $50,000 + $50,000 discounted gain = $100,000 total — additional tax of approximately $15,000-$16,000
- Income of $190,000 + $50,000 discounted gain = $240,000 total — additional tax of approximately $22,500 (at 45%)
Capital Losses Can Reduce Your Gain
If you have capital losses from the same year or carried forward from prior years, these reduce your capital gain before the 50% discount is applied. For example, if you have a $100,000 gain and a $30,000 capital loss, your net gain is $70,000 — then the 50% discount applies (if held 12+ months), leaving $35,000 to add to your taxable income. Strategic use of capital losses is one of the most effective CGT reduction tools.
Frequently Asked Questions
How do I calculate my capital gain on a property sale?
Capital gain = Sale price minus cost base. The cost base includes: the original purchase price, stamp duty, legal costs on purchase, improvement costs (renovations, extensions), and selling costs (agent commission, legal fees on sale). You do not deduct previous depreciation claims from the cost base (though you must add back Building and Plant depreciation previously claimed for investment properties — this is called the depreciation recapture rule).
Do I pay CGT on my family home?
Generally no. Your principal place of residence is exempt from CGT under the main residence exemption, provided you lived in it for the entire period of ownership and it was not used to produce income. Partial exemptions apply if you rented part of the property, rented it out for a period, or the property exceeds 2 hectares. Moving overseas and renting your former home can also partially reduce the exemption.
Have a significant capital gain in 2025-26? Contact AWTS — we help clients minimise CGT through timing strategies, loss harvesting, and correct application of the 50% discount.
Child care costs are not directly tax-deductible in Australia — but the Child Care Subsidy (CCS) provides means-tested government assistance that effectively reduces the out-of-pocket cost of approved child care for most Australian families. In 2026, CCS rates have been increased under the government's affordability agenda, with families earning under $83,280 now eligible for the maximum 90% subsidy rate. Here is what you need to know.
Are Child Care Expenses Tax-Deductible in Australia?
No. The ATO does not allow individuals to claim child care expenses as a tax deduction, even if you are working or studying. This has been the position since 1994 when the government moved child care support to the welfare system through the Child Care Subsidy (and previously the Child Care Rebate). The rationale is that child care is a private expense rather than one incurred in the course of earning assessable income.
Child Care Subsidy (CCS) Rates in 2026
The Child Care Subsidy is paid directly to your approved child care provider, reducing your fees. The subsidy rate depends on your combined family income:
- Under $83,280: 90% subsidy rate (maximum)
- $83,280 to $530,000: Subsidy rate tapers from 90% down to 0%
- Above $530,000: No CCS entitlement
The subsidy also depends on your activity level (hours of work, study, or training), the approved hourly rate cap for your service type, and the number of children in care (higher subsidy for second and subsequent children from July 2023).
Activity Test: Hours of Care Subsidised
The number of subsidised hours per fortnight depends on the lowest activity level of either parent. Activities include paid work, study, training, volunteering, and looking for work.
- 8 hours or less: Up to 36 subsidised hours per fortnight
- 8-16 hours: Up to 72 subsidised hours per fortnight
- 16-48 hours: Up to 100 subsidised hours per fortnight
- 48 hours or more: Up to 100 subsidised hours per fortnight
What About the Family Tax Benefit?
Families with children may also be eligible for Family Tax Benefit (FTB) Part A and Part B, which provide additional fortnightly payments based on income and family circumstances. FTB is separate from CCS but both are managed through Services Australia (Centrelink). Unlike CCS, FTB Part B can apply to single-income families and single parents.
Frequently Asked Questions
Can I claim child care on my tax return?
No. Child care expenses are not tax-deductible in Australia. The Australian government provides support through the Child Care Subsidy (CCS), which directly reduces your fees with the child care provider. If you believe you were under-subsidised, you can request a CCS reconciliation through myGov after the end of the financial year.
How do I claim Child Care Subsidy?
Apply through myGov linked to your Centrelink account. You will need your family's estimated combined income, details of your approved child care service, and your activity information. The subsidy is paid directly to the provider — your fees are reduced at the point of billing.
Does Child Care Subsidy affect my tax return?
Yes indirectly. CCS is means-tested and based on estimated income. After the financial year, Services Australia reconciles your actual income against the estimated income used to calculate your subsidy. If your actual income was higher, you may need to repay some CCS. If lower, you may receive a top-up. This reconciliation uses your lodged tax return data.
Questions about family tax benefits, CCS, or how government payments affect your tax return? Contact AWTS for a complete family tax review.