
The big question for any business owner in Australia—sole trader or company—really boils down to one thing: how your profits are taxed. As a sole trader, every dollar you earn is taxed at your personal marginal rate. As your business grows, so does your tax bill. In contrast, a company pays a flat corporate tax rate, which can be a game-changer for reinvesting profits and scaling up.
- Choosing Your Business Structure: Key Tax Differences
- How Tax Rates And Profit Treatment Differ
- Navigating Deductions And Business Expenses
- Comparing Asset Protection And Legal Liability
- Understanding Compliance Costs And Administration
This single difference is the foundation upon which your financial future is built. Getting it wrong can mean handing over a huge chunk of your hard-earned profits to the tax office.
Choosing Your Business Structure: Key Tax Differences
Deciding to operate as a sole trader versus a company is one of the most important financial calls you'll make. It directly shapes your tax bill, how protected your personal assets are, and your capacity to grow. The simplicity of being a sole trader is tempting, but the tax realities are worlds apart from a company structure.
Let's cut through the noise and focus on what really hits your bottom line: the tax treatment of your profits.
- Tax Treatment: As a sole trader, your business profit is your personal income, so it's taxed at ever-increasing individual rates. Company profits are taxed at a fixed, lower corporate rate, creating a clear advantage for keeping more money in the business to fuel growth.
- Legal Liability: When you're a sole trader, there's no legal distinction between you and the business. Your personal assets—your house, your car—are on the line. A company is a separate legal entity, which acts as a shield to protect your personal wealth from business debts.
- Administrative Burden: Sole traders have it easy here with minimal setup and compliance. Companies demand formal registration with ASIC, annual reviews, and much more rigorous record-keeping. It's more work, no doubt about it.
This infographic gives you a quick visual snapshot of the key trade-offs.
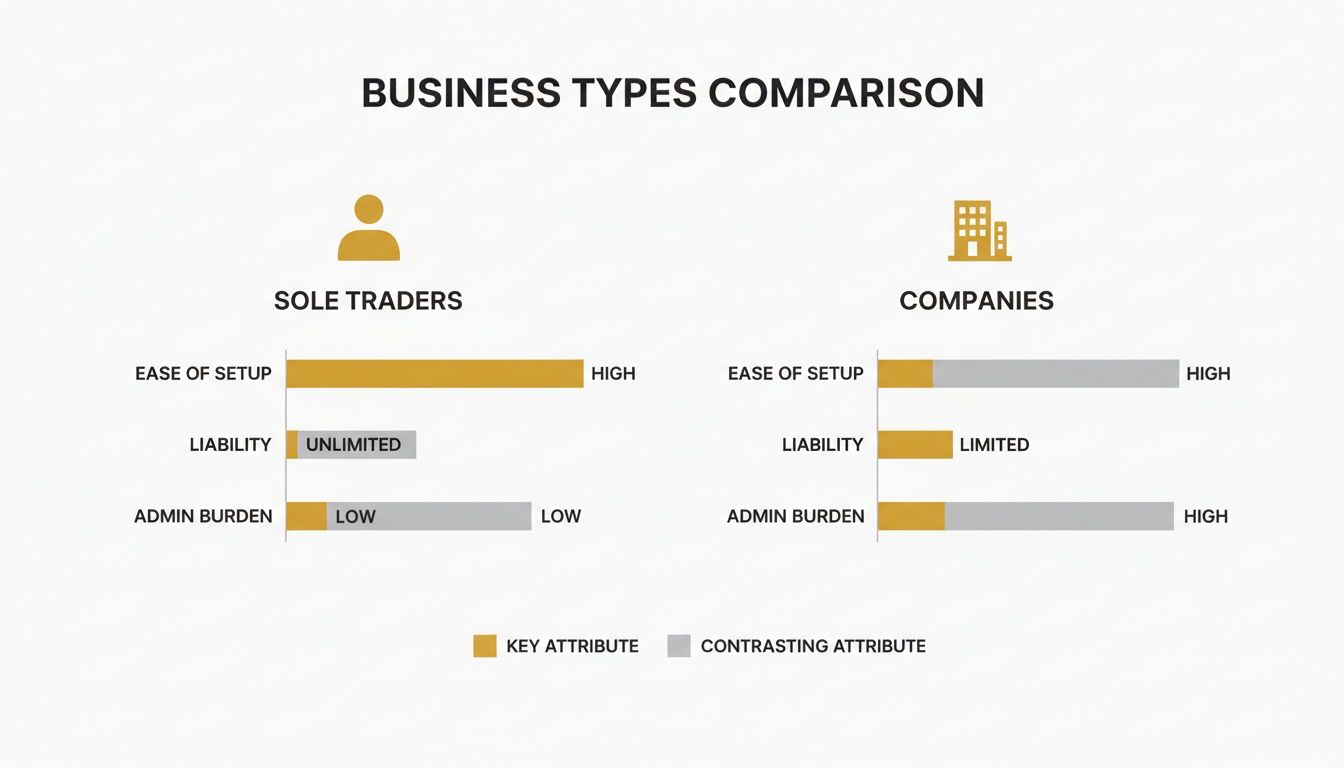
As you can see, it's a classic balancing act. The sole trader route offers simplicity but comes with high personal risk. A company provides that crucial legal protection but at the cost of more admin.
The core decision hinges on balancing immediate simplicity against long-term financial efficiency and legal protection. As your business grows, the tax benefits of a company structure often become too significant to ignore.
In Australia, where a massive 67% of businesses are sole traders, the tax pain kicks in quickly as you become more successful. Under the 2023-24 ATO rates, a sole trader pulling in $180,000 in profit pays an effective tax rate of around 40%. A company with the same profit (as a base rate entity) is taxed at a flat 25%. That's a huge difference that highlights a powerful path for scaling your operations.
When you're trying to make this call, a solid guide on how to choose your business structure can be invaluable, especially when you start weighing up these significant tax implications.
How Tax Rates And Profit Treatment Differ
The biggest financial question when comparing a sole trader to a company comes down to one thing: how each dollar of profit gets taxed. This isn't just a small detail on a tax form; it's the core difference that could save—or cost—you thousands over the life of your business. The structure you choose directly dictates how much cash stays in your pocket and how much you can reinvest.
For a sole trader, the maths is simple. Your business profit is your personal income. It gets lumped in with any other income you earn and is taxed at your marginal personal income tax rate. As your business grows and your profits climb, you inevitably get pushed into higher tax brackets, meaning the ATO takes a bigger slice of every new dollar you make.
A company, however, is a completely separate legal and tax entity. It pays tax on its profits at a flat corporate rate, which for most small businesses in Australia is currently 25%. This separation is what creates a clear and often immediate tax advantage, especially for businesses that want to keep profits in the tank to fund future growth.
A Real-World Profit Scenario
Let's make this tangible. Imagine you're a skilled plumber in Sydney having a great year, clearing $80,000 in profit. As a sole trader, that entire $80,000 lands on your personal tax return. Once you account for the different tax brackets and the 2% Medicare levy, you'd be looking at a tax bill of roughly $18,447.
Now, let's see what happens if that same business is structured as a company. The $80,000 profit is first taxed at the flat 25% corporate rate, resulting in a $20,000 tax bill. The crucial part is what happens next. The company now holds the remaining $60,000. That money can be used to buy new equipment, hire staff, or invest in marketing—all without you personally paying any more tax on it until it's paid out to you as a wage or dividend.
Here's the key takeaway: As a sole trader, every dollar of profit is taxed at your personal rate, straight away. With a company, only the money you physically take out is taxed at your personal rate. Profits left inside the business are taxed at the lower, flat corporate rate.
Tax Liability At Different Income Levels
This difference in tax treatment becomes much more dramatic as your income rises. Because personal tax rates are progressive, a sole trader's tax burden accelerates far more quickly than a company's. For a closer look at how the brackets work, check out our detailed guide on Australian sole trader tax rates.
To really see the impact, let's run the numbers and compare the tax payable at different profit levels. This shows the potential savings a company offers if you plan on retaining profits in the business.
Tax Liability Comparison: Sole Trader vs Company
This table breaks down the tax payable for each structure, assuming all profits are kept within the business for the company scenario.
| Taxable Income | Sole Trader Tax Payable (incl. Medicare Levy) | Company Tax Payable (at 25%) | Potential Annual Tax Saving on Retained Profits |
|---|---|---|---|
| $80,000 | ~$18,447 | $20,000 | -$1,553 (Sole trader is slightly better) |
| $150,000 | ~$44,247 | $37,500 | $6,747 |
| $250,000 | ~$87,497 | $62,500 | $24,997 |
As you can see, the numbers tell a clear story. Once your taxable income climbs past the $90,000 mark, the company structure starts to pull ahead, delivering significant tax savings on any profits you want to reinvest. For any business owner focused on scaling up, this is a critical tipping point to be aware of.
Navigating Deductions And Business Expenses
On the surface, both sole traders and companies can claim deductions for legitimate business costs. But that’s where the similarities end. The real story behind the tax benefits of a company versus a sole trader emerges when you dig into the strategic planning opportunities a company structure unlocks.
Sure, both can deduct everyday expenses like rent, supplies, and marketing. However, the company’s status as a separate legal entity opens up powerful avenues for reducing taxable profit that a sole trader simply can't access.
When you're weighing up these structures, understanding how to properly claim everything you're entitled to is essential. For sole traders, knowing the full scope of available sole trader tax deductions can make a huge difference to your final tax bill, ensuring nothing gets missed.
The game changes with a company, though, as it introduces deductions that are completely off the table for a sole trader.
Strategic Deductions for Companies
A massive advantage for a proprietary limited company is its ability to pay its owners (who are also directors) a salary, superannuation, and even director's fees. These aren't just drawings; they are treated as legitimate business expenses.
This directly reduces the company's taxable profit before the 25% corporate tax rate is even applied.
For example, paying yourself a director's salary provides a steady personal income while simultaneously lowering the company's tax bill. On top of that, the compulsory superannuation contributions paid on that salary are also a deductible expense for the business. It’s a tax-efficient way to pull money out of the business while building your own retirement nest egg.
The ability to treat owner remuneration and superannuation as deductible business expenses is a fundamental tax benefit of the company structure. It allows you to strategically lower company profit while building personal wealth in a tax-effective manner.
Limitations for Sole Traders
Sole traders, on the other hand, run into a few walls that companies don't. The biggest one is the Personal Services Income (PSI) rules. If the ATO decides your income is mainly a reward for your personal skills or effort, your ability to claim certain deductions can be severely restricted. This can include things like payments to family members for non-principal work or even some superannuation contributions.
A company structure also naturally enforces better record-keeping. The formal separation between business and personal finances creates a much clearer paper trail. This not only makes tax time simpler but also significantly lowers your risk profile if the ATO ever comes knocking for an audit, making it a much safer vehicle for growth.
Comparing Asset Protection And Legal Liability
While the tax benefits are a massive part of the sole trader vs company debate, we can't stop there. For a lot of business owners I speak to, this next point is actually more important than saving a few dollars on tax. It's about personal liability, and it hits right at your financial security and peace of mind, especially as your business starts to grow and take on bigger risks.
As a sole trader, the law sees absolutely no difference between you and your business. You are one and the same. This means if your business gets into financial strife or someone decides to sue you, your personal assets are fair game. We're talking about your family home, your car, your savings – it's all on the line to settle business debts.
This complete lack of separation is hands down the single biggest risk of being a sole trader. If you're in an industry with a higher chance of things going wrong, like construction or professional consulting, this unlimited liability can be a constant source of stress.
The Company's Corporate Veil
Now, flip the coin. A company is a separate legal entity. This isn't just fancy legal talk; it creates a genuine barrier, often called the 'corporate veil', that stands between the business's finances and your personal finances. It's one of the most powerful reasons to incorporate, completely separate from any tax advantages.
What this legal wall means is that if the company racks up debt or gets sued, the liability is generally capped at the assets the company itself owns. Creditors can go after the business bank account or its equipment, but your personal assets are safely tucked away on the other side of that veil.
The corporate veil is your personal financial shield. It means a business failure doesn't have to become a personal financial catastrophe, giving you the confidence to take calculated risks and grow your venture.
A Practical Liability Scenario
Let's make this real. Imagine a business lawsuit goes badly and results in a $100,000 liability.
- Sole Trader Outcome: The business only has $30,000 in assets. The creditors can, and will, legally come after the owner for the remaining $70,000. This could mean being forced to sell your car or even having a lien slapped on your family home.
- Company Director Outcome: The company has the same $30,000 in assets. The creditors can only claim that $30,000. The director's personal assets are protected. Assuming they've acted lawfully, they are not personally on the hook for the $70,000 shortfall.
This stark difference shows exactly why asset protection is a critical piece of the sole trader vs company tax benefits conversation. The legal shield a company provides is often invaluable, laying a much safer foundation for long-term, sustainable growth.
Understanding Compliance Costs And Administration
Beyond the tax rates themselves, the day-to-day admin is a huge factor that hits your two most valuable resources: your time and your money. For many new ventures, the sheer simplicity of being a sole trader is its biggest selling point. The setup is dead simple—often just an Australian Business Number (ABN)—and the ongoing compliance is just as straightforward, usually just rolling everything into your personal tax return.
A company, on the other hand, is a completely different beast when it comes to admin. Getting started means a formal registration with the Australian Securities and Investments Commission (ASIC), which has its own upfront costs. And that’s really just the first step on a much more demanding compliance journey.
The Ongoing Demands Of A Company
Running a company means committing to a whole host of ongoing regulatory requirements. These aren't just 'nice-to-haves'; they're legal obligations, and ignoring them comes with hefty penalties. The administrative price tag you pay for the tax and liability benefits is significantly higher.
Here’s a taste of the key ongoing obligations you’re signing up for:
- Annual ASIC Review: Every year, you have to pay an annual review fee just to keep your company registered.
- Separate Tax Returns: You’ll need to prepare and lodge a separate, more complex company tax return each year. We break this down in our guide on how to lodge a company tax return.
- Stricter Record-Keeping: Corporate law demands that you keep meticulous financial records. This isn't just about receipts; it includes formal minutes of meetings and resolutions from the director.
All this extra work almost always translates into higher fees from your accountant. For instance, companies have to deal with ASIC reporting, which includes annual fees of $311, and you can expect accounting costs to be two or three times higher than for a sole trader. Despite these costs, the ATO still sees around 83% compliance among small businesses, which tells you that for many, the trade-off is worth it. You can find out more by reading this in-depth analysis of the company structure vs sole trader costs.
It all boils down to a fundamental trade-off: Do the potential tax savings and asset protection a company offers actually outweigh the extra costs and administrative headaches? This is exactly where getting professional advice is non-negotiable for making a smart financial decision.
Ultimately, the right choice really depends on the scale of your business, your risk profile, and where you see it going. A sole trader structure is perfect for low-risk, simple operations where keeping costs and complexity down is the number one priority. A company is built for businesses with big growth plans, those who need to protect their personal assets, and are ready to take on the administrative load that comes with it.
Making The Right Choice: When To Switch To a Company
Deciding when to jump from a sole trader to a company structure isn't just about tax; it’s a strategic pivot for your business's future. The beautiful simplicity of being a sole trader is perfect for getting off the ground, but there are clear signals that it’s time to evolve.
Ignoring these signs can mean handing over unnecessary tax to the ATO, putting your personal assets on the line, and artificially capping your growth potential.
This isn’t about hitting a single magic number. It's about a combination of factors reaching a tipping point. The key is spotting these triggers before they become problems, ensuring your business structure is a springboard for your long-term goals, not an anchor holding you back.
Key Triggers for Incorporation
Thinking about making the switch? Keep an eye out for these classic scenarios. If one or more of these sounds familiar, it’s a strong sign that a company structure is the next logical move.
Your Income Is Hitting Higher Tax Brackets: Once your taxable income as a sole trader consistently pushes past the $120,000 mark, your personal marginal tax rate starts to seriously outpace the flat 25% corporate rate. This is the most common financial trigger we see.
You Need to Protect Your Personal Assets: As your business grows, so does its risk profile. If you've built up personal wealth—like a family home or an investment portfolio—the unlimited liability of a sole trader structure becomes a huge, unacceptable risk. A company creates a legal firewall.
You Want to Reinvest Profits Into the Business: A company is a far more tax-efficient vehicle for growth. It lets you keep post-tax profits (taxed at just 25%) in the business to fund expansion, buy assets, or hire staff, without that money first being hit at your higher personal tax rate.
The decision to incorporate is fundamentally a forward-looking one. It’s about building a foundation that can handle increased profit, greater risk, and future complexity, turning your successful operation into a scalable and protected enterprise.
- You're Bringing on Partners or Investors: If the plan is to bring other people into the business, a company structure is non-negotiable. It provides a clean, clear framework for issuing shares, defining ownership, and managing control in a way a sole trader setup simply can't.
Recognising these triggers is the first step; the next is taking action. If you're ready to look into this more deeply, our guide on how to set up a PTY LTD company in Australia lays out a clear roadmap for the incorporation process. Making this change at the right time is absolutely crucial for locking in the best possible financial outcomes.
Your Questions Answered
When you're weighing up the sole trader vs company structure, a lot of specific questions pop up. Let's tackle some of the most common ones we hear from clients every day.
How Do I Pay Myself from a Company?
This is a fundamental shift from being a sole trader. As a sole trader, you just take 'drawings' from the business profits whenever you like. Simple.
When you're a director of a company, it’s more formal. You pay yourself a proper salary or wage, just like any other employee. This payment becomes a deductible business expense for the company, which helps lower its taxable profit.
The catch is that this brings you into the formal payroll system. You'll need to manage Pay As You Go (PAYG) withholding and meet your superannuation guarantee obligations. Your salary is then taxed at your individual marginal rate, completely separate from the company's tax affairs.
How Does Capital Gains Tax Differ?
The way Capital Gains Tax (CGT) is handled really highlights the structural divide between these two setups.
If a sole trader sells a business asset and makes a profit, that capital gain just gets added to their personal income for the year. The good news is they can often access the 50% CGT discount if they've owned the asset for more than 12 months, effectively halving the tax impact.
A company, on the other hand, gets no such discount. The entire capital gain is taxed at the flat corporate rate. It’s not all bad news, though. Companies can often access a different set of small business CGT concessions which can sometimes reduce or even wipe out the tax bill. It's a complex area, but potentially very rewarding.
The loss of the 50% CGT discount is a major sticking point for companies. However, the other small business CGT concessions available can sometimes lead to a better outcome. This is definitely not a DIY calculation—getting professional advice is essential when selling significant assets.
Is It Hard to Switch from a Sole Trader to a Company?
Making the jump isn't just paperwork; it’s a formal process with real financial implications. The transition involves registering a new company with ASIC and then officially transferring all your business assets—think equipment, client lists, and goodwill—from your name over to the new company entity.
Here's the critical part: that transfer can trigger tax events. Moving assets can crystallise a capital gain (and a CGT bill) or even attract stamp duty in some states.
Because of this, you absolutely need to get professional guidance. A good accountant can help you structure the transition in the most tax-effective way, ensuring you don't get hit with unexpected financial penalties during the changeover.
The four main structures are sole trader, partnership, company, and trust. A sole trader is simplest and cheapest but offers no liability protection. A company provides limited liability at a flat tax rate but costs more to run. A trust offers tax flexibility and asset protection but is complex to administer. The right choice depends on income, risk profile, and growth plans.
Base rate entities — companies with aggregated turnover under $50 million that derive no more than 80% of income from passive sources — pay 25%. All other companies pay 30%. Shareholders pay income tax on dividends, potentially offset by franking credits for tax already paid at the corporate level.
Consider a company when business net profit consistently exceeds $100,000–$120,000 and the rate differential generates meaningful savings, when you need liability protection from business creditors, when you plan to bring in investors, or when you want to retain earnings at the lower corporate rate rather than distributing everything as personal income.
A family trust (discretionary trust) holds assets for a class of beneficiaries. The trustee decides each year how much income to distribute to each beneficiary. By directing income to members in lower tax brackets, the trust reduces the overall family tax burden. Income retained in the trust is taxed at the highest marginal rate (47%).
Ongoing costs include the ASIC annual review fee (currently $310 for a proprietary company), company tax return lodgement fees, accounting fees for financial statements, and potentially payroll and BAS compliance. Total annual compliance costs typically range from $2,000 to $8,000 depending on activity levels and complexity.
Sole Trader vs Company: An At-a-Glance Comparison
Picking the right business structure is one of the first, and most important, decisions you'll make as an entrepreneur in Australia. It sets the foundation for your personal risk, tax obligations, and ongoing compliance workload. To really get this, it helps to understand the definition of a sole proprietorship as the most basic business form. The sole trader structure is hands-down the simplest and cheapest way to get started. All you really need is an Australian Business Number (ABN), and from a tax perspective, the business’s income is simply your personal income. While that simplicity is a huge drawcard, it comes with a major catch: unlimited liability. There's no legal wall between you and the business. If the business racks up debt, your personal assets—your house, your car—could be on the line. On the other hand, a company, specifically a Proprietary Limited (Pty Ltd) company, offers the protection of limited liability. This creates a crucial barrier between your personal finances and the business's debts, because the company is legally its own 'person'. Of course, this protection doesn't come for free. It involves higher setup costs, stricter rules, and much more complex annual reporting duties. This visual breaks down the core differences in liability, tax, and setup complexity.
Key Differences: Sole Trader vs Company at a Glance
This table cuts straight to the chase, comparing the key features of each structure.| Feature | Sole Trader | Company (Pty Ltd) |
|---|---|---|
| Legal Status | You and the business are the same legal entity. | A separate legal entity from its owners (shareholders). |
| Liability | Unlimited personal liability for all business debts. | Limited liability; personal assets are usually safe. |
| Tax Rate | Taxed at your individual marginal income tax rates. | Taxed at the flat corporate tax rate (25% or 30%). |
| Setup Cost & Complexity | Simple and cheap—often just an ABN registration. | More complex and costly; requires ASIC registration. |
| Ongoing Compliance | Much simpler; report income on your personal tax return. | More complex; needs annual reviews & separate tax returns. |
Understanding Your Legal and Financial Risk
The Protective Shield of a Company
In stark contrast, a registered company is its own separate legal entity. This isn't just a bit of paperwork; it creates a powerful protective barrier known as limited liability, and it fundamentally changes your entire risk profile. Because the company is legally distinct from its owners (the shareholders), any business debts or legal dramas are the company's problem, not yours. Your personal assets are generally shielded, safe from being used to pay for business liabilities. This separation is the single biggest reason why entrepreneurs in higher-risk industries like construction or consulting almost always opt for a company structure from day one.Key Insight: Limited liability isn’t just about protecting what you have now. It’s about building a safe foundation for future growth. It gives you the confidence to take calculated business risks, like hiring staff or taking out a loan, without gambling with your family’s financial security.
Liability in Real-World Scenarios
To see how this plays out in practice, let’s imagine a landscaping business that accidentally causes major property damage.- As a Sole Trader: The owner is personally sued. If the business insurance doesn’t cover the full cost of the damages awarded by the court, the owner’s home and personal savings could be liquidated to pay off the rest.
- As a Company: The company itself gets sued. The liability is capped at the company's assets. The owner’s personal home, car, and savings remain completely protected from the lawsuit, assuming no fraudulent activity or personal guarantees were involved.
Navigating Tax and Financial Compliance
How Companies Approach Taxation
A company, on the other hand, is a completely separate legal entity, and its tax treatment is entirely different. The company's profit is taxed at a fixed corporate tax rate—currently 25% for small businesses that meet the criteria, or 30% for all other companies. This flat rate can be a game-changer once your business profits start pushing you into the higher personal income tax brackets. But you can't just take money out of the business account whenever you like. You need to pay yourself formally, either as a director's salary (with PAYG withholding) or by distributing profits to shareholders as dividends.Key Takeaway: The tax structure difference is fundamental. A sole trader's profit is taxed at escalating personal rates, while a company's profit is taxed at a flat corporate rate. This creates strategic opportunities for tax planning in a company structure that simply don't exist for a sole trader.
Compliance and Reporting Obligations
The simplicity of the sole trader structure carries through to its ongoing compliance. While you still need to keep good financial records and may have to lodge Business Activity Statements (BAS) if you're registered for GST, the overall administrative load is pretty light. Your main job is lodging that annual personal tax return. In stark contrast, running a company brings a much heavier burden of financial and legal compliance.- Annual Company Tax Return: You are legally required to prepare and lodge a separate, detailed tax return just for the company.
- ASIC Annual Review: Every single year, you must review and confirm your company's details with the Australian Securities and Investments Commission (ASIC) and pay the annual review fee.
- Director Duties: As a company director, you have strict legal duties under the Corporations Act 2001 to always act in the best interests of the company. These aren't just suggestions; they're legally enforceable.
- Strict Record-Keeping: Both the ATO and ASIC demand a higher standard of record-keeping for companies, including maintaining proper financial statements and company registers.
Comparing Setup Costs and Ongoing Administration
When you're starting out, every dollar and every minute counts. The initial setup costs and the long-term admin load are two of the most practical differences between a sole trader and a company. This isn’t just about paperwork; it directly hits your wallet and your schedule. Registering as a sole trader is as straightforward as it gets. The main step is getting an Australian Business Number (ABN), which is completely free. For many, this simple online application is all it takes to start trading. It’s hands down the fastest and cheapest way to get your business off the ground. Setting up a company, on the other hand, is a much bigger deal, both in terms of effort and cost. You have to formally register with the Australian Securities and Investments Commission (ASIC), which comes with a significant one-off fee. As of 2024, you’re looking at over $500 just for the registration – a stark contrast to the zero cost of an ABN.The Initial Setup Hurdle for Companies
It’s not just the money; it’s the administrative legwork. You need to officially choose a company name, appoint directors, issue shares to owners, and set up a registered office address. This isn't just a to-do list; it's the formal governance structure of your business, and it needs to be right from day one. If you're going down this path, our detailed guide on how to set up a Pty Ltd company in Australia is a must-read.Weighing Ongoing Administrative Burdens
Once you're up and running, the day-to-day admin requirements couldn't be more different. For sole traders, the main ongoing task is lodging your annual personal tax return, where you simply include your business income and expenses. The record-keeping is simpler because it’s all tied to you personally. Companies, however, are in a different league. They have a heavy compliance load and are legally bound by the standards in the Corporations Act 2001. This brings a list of non-negotiable annual jobs that demand time, attention, and often, professional help. Key Annual Company Obligations:- ASIC Annual Review: Every year, you have to pay an annual review fee to ASIC (currently over $300) and formally confirm your company details are still correct.
- Separate Company Tax Return: A company must lodge its own, more complex tax return, completely separate from your personal finances.
- Formal Record-Keeping: Directors are legally required to maintain detailed financial records, keep minutes of important meetings, and manage a register of all members (shareholders).
This isn't just about extra paperwork. A company’s compliance is a serious legal responsibility. If you fail to meet your ASIC obligations, you can be hit with late fees and penalties personally as a director. It’s a whole other layer of accountability.For any business, but especially for trades and service-based companies, getting systems in place for efficient job and cost tracking from the start is essential to manage this burden. Ultimately, your choice has to match how much time and money you’re prepared to commit to ongoing admin.
Choosing the Right Structure for Your Goals
When a Sole Trader Structure Makes Sense
In many common scenarios, operating as a sole trader is simply the most logical and efficient way to go. This structure is all about simplicity, low costs, and minimal paperwork, making it ideal for testing out a business idea without a massive commitment. Think about these situations where being a sole trader is the clear winner:- Testing a New Business Idea: If you're launching a side hustle or trying out a new concept with very little capital, the sole trader setup lets you start trading almost instantly with just a free ABN.
- Freelancers and Consultants: For graphic designers, writers, IT consultants, and other independent professionals, this model is a natural fit. Your income is tied directly to your personal work, and the administrative simplicity means you can focus on clients instead of paperwork.
- Gig Economy Participants: Anyone earning income from platforms like Uber, Airtasker, or Deliveroo can easily manage their tax obligations as a sole trader.
When a Company Structure Is the Right Move
As your business grows, so do your risks and your needs. Moving to a company structure often becomes not just a good idea, but an essential step for businesses that are planning to scale, build credibility, and protect themselves. A company is the better path when your plans involve:- Hiring Employees: The moment you start taking on staff, the limited liability a company offers becomes critical. It shields your personal assets from things like workplace claims or other liabilities.
- Seeking Investment: Investors nearly always insist on a formal company structure. It makes selling shares straightforward and provides a clear, regulated framework for them to manage their investment.
- Operating in High-Risk Industries: For trades like construction or businesses that offer professional advice, the "corporate veil" is non-negotiable. It protects your personal wealth if the business runs into major debts or faces a lawsuit.
A company structure is a signal to the market—to clients, lenders, and investors—that you are building a serious, scalable, and enduring enterprise. It builds a level of credibility and trust that is often harder to achieve as a sole trader. This framework is designed for growth.
Answering Your Key Questions
Even after laying out the core differences, many entrepreneurs we talk to still have those nagging "what if" questions when deciding between a sole trader and company setup. It’s often these practical, real-world scenarios that make all the difference. This section tackles the most common queries we hear day in and day out. Think of this as the final piece of the puzzle, designed to give you the confidence to move forward by clearing up any lingering doubts about flexibility, growth, and long-term planning.Can I Change My Business Structure Later On?
Yes, absolutely. In fact, it’s one of the most common pathways for a successful Australian business. Starting out as a sole trader and then switching to a company structure as you grow is a well-trodden path. The process involves registering a new company with ASIC and then formally transferring the business assets, name, and ABN from your sole trader setup to the new company. It definitely requires some administrative work—and getting advice from an accountant is a smart move—but it's a standard procedure.Key Insight: Starting as a sole trader isn't a life sentence. It’s a flexible starting point that lets you test your business idea with minimal cost and paperwork before you take on the bigger responsibilities of running a company.This flexibility means you can pick the structure that fits you right now, without stressing that you're locked in forever. Your legal structure can—and should—scale up right alongside your business success.
Can a Sole Trader Hire Employees?
Yep, a sole trader can legally hire employees. You’ll need to get set up for Pay As You Go (PAYG) withholding with the ATO and make sure you’re meeting your superannuation obligations for any eligible staff. However, this is where the unlimited liability of a sole trader becomes a serious risk. The moment you have employees, you’re responsible for their safety at work and become exposed to potential issues like unfair dismissal claims or workplace accidents. Because there's no legal wall between you and the business, any liability from your role as an employer lands squarely on your personal shoulders. This is one of the biggest reasons many businesses incorporate before they even think about building a team. The company structure acts as a container, keeping that employment-related risk inside the business and away from your personal assets.Which Structure Is Better for Getting a Business Loan?
When it comes to securing serious business finance, a company structure is generally looked upon much more favourably by banks and lenders. There are a few very clear reasons why. Lenders see a company as a more formal, stable, and permanent entity. The strict reporting and governance rules give them a lot more confidence in the business's financial management and its chances of long-term survival. A company's status as a separate legal entity also creates a cleaner framework for securing loans. A lender can take security over the company's assets, which is far more straightforward than trying to untangle an individual's personal and business assets, which are all mixed together in a sole trader structure. While it's not impossible for a sole trader to get a big business loan, it’s often a much tougher conversation.Navigating these structural decisions is a critical step in setting up your business for success. For expert guidance tailored to your specific situation, the team at Australia Wide Tax Solutions can help you understand the tax and compliance implications of each choice, ensuring you start on the right foot.
The four main structures are sole trader, partnership, company, and trust. A sole trader is simplest and cheapest but offers no liability protection. A company provides limited liability at a flat tax rate but costs more to run. A trust offers tax flexibility and asset protection but is complex to administer. The right choice depends on income, risk profile, and growth plans.
Base rate entities — companies with aggregated turnover under $50 million that derive no more than 80% of income from passive sources — pay 25%. All other companies pay 30%. Shareholders pay income tax on dividends, potentially offset by franking credits for tax already paid at the corporate level.
Consider a company when business net profit consistently exceeds $100,000–$120,000 and the rate differential generates meaningful savings, when you need liability protection from business creditors, when you plan to bring in investors, or when you want to retain earnings at the lower corporate rate rather than distributing everything as personal income.
A family trust (discretionary trust) holds assets for a class of beneficiaries. The trustee decides each year how much income to distribute to each beneficiary. By directing income to members in lower tax brackets, the trust reduces the overall family tax burden. Income retained in the trust is taxed at the highest marginal rate (47%).
Ongoing costs include the ASIC annual review fee (currently $310 for a proprietary company), company tax return lodgement fees, accounting fees for financial statements, and potentially payroll and BAS compliance. Total annual compliance costs typically range from $2,000 to $8,000 depending on activity levels and complexity.
Quick Snapshot Of Dividend Tax Rates
Summary Of Dividend Tax Rates
| Investor Type | Dividend Type | Tax Rate | Withholding Tax Rate |
|---|---|---|---|
| Resident | Franked | Marginal rate | 0% |
| Resident | Unfranked | Marginal rate | 0% |
| Non-resident | Franked | N/A | 30% |
| Non-resident | Unfranked | N/A | 30% |
- Residents unlock a franking credit to cancel out company tax already paid.
- Unfranked dividends are simply taxed at your personal marginal rate.
- All dividends to non-residents incur a 30% withholding tax.
- Even franked payments to non-residents get taxed on their unfranked portion.
Key takeaway: Franking credits act like a voucher for company tax paid, preventing you from being taxed twice.Before we dive into worked examples, keep these figures front of mind as your quick reference.
Key Rate Highlights
To bring these numbers to life, consider a mid-income Australian resident on a 30% marginal rate. If they receive a $70 fully franked dividend (with a gross-up to $100), their franking credit wipes out any extra tax—leaving them square.- A fully franked dividend carries a 30% credit for company tax already paid.
- Unfranked dividends are added to your assessable income and taxed at your full marginal rate.
- Non-resident investors see 30% withheld before you even touch the cash.
- Double tax agreements can slice that withholding—depending on your home country.
Treaty example: A UK resident might only pay 15% under the Australia–UK Double Tax Agreement.Cross-checking your dividend statement with these highlights makes sure you never miss franking credits or spot under-withholding.
Next Steps
Now that you’ve got the big picture, grab your latest dividend statement and match it line-by-line. If anything feels murky, chat with an AWTS adviser for clear, expert guidance. This overview paves the way for the detailed sections ahead—where we’ll break down gross-up calculations, credit claims and non-resident treaty nuances. Bookmark this guide for your next tax return lodgement.Understanding Dividend Tax Concepts
Dividends are a way companies share profits with investors. It’s your return for owning a slice of the business. When you hold shares, you’ll often see a cash payment labelled a dividend. Sometimes these payments come with a tax offset, depending on how much company tax has already been paid. Imagine handing out sweets from a packet. Each share is like a ticket in the draw. The more tickets you hold, the more sweets you collect. Without a franking credit, it can feel like paying twice for the same treat.- Franked Dividends include a credit for company tax already paid.
- Unfranked Dividends have no tax offsets attached.
- Franking Credits can reduce or even eliminate extra tax bills.
Key Dividend Definition
A franked dividend brings with it a franking credit, matching the tax the company has already paid on that profit. This mechanism stops you from being taxed twice. By contrast, an unfranked dividend carries no credit. You pay tax on the full amount at your personal marginal rate.Franking credits act like coupons for tax already paid, offsetting what you owe at tax time.
How Imputation Works
Australia’s dividend imputation system hands company tax paid straight to shareholders as credits. Picture a company earning $100 in profit, paying $30 in tax, then distributing $70 cash plus a $30 credit. Key steps include:- Company earns profit and pays tax at 30%
- Company issues a dividend with an attached franking credit
- Shareholder reports the grossed-up dividend as income and claims the credit
Why System Matters
By preventing double taxation, the imputation system keeps more money in investors’ pockets. Without it, profits would be taxed at the corporate level and again on your personal return. It also makes Australian shares more appealing by aligning company and shareholder tax outcomes.| Feature | Before | After |
|---|---|---|
| Taxation | Double taxed | Single tax with credit |
- Lower overall tax on dividends
- Simpler reporting at lodgement time
- Better alignment between company profits and investor returns
Case Study
Anna holds 100 shares in XYZ Ltd. She receives an $80 fully franked dividend with a $34.29 credit. At her marginal rate of 34.5%, she owes no extra tax and even sees a small refund.Historical Shift Explained
On 1 July 1987, Australia reformed its dividend tax rules to stamp out double taxation. Before this change, shareholders paid personal income tax on dividends with no credit for company tax already paid. Learn more about the 1987 imputation reform on EndureGo.Key takeaway: Franking credits ensure you aren’t taxed twice on the same profit, supporting fairer and more efficient capital markets.Understanding these fundamentals sets you up to tackle resident versus non-resident dividend rules. Next, we’ll unpack how different tax rates apply depending on where you live.
Resident And Nonresident Dividend Tax Rates
Your residency status can make a huge difference to how dividends are taxed in Australia. If you’re an Australian resident, every dollar of dividend income slides into your marginal tax bracket. Non-residents, by contrast, face a fixed withholding rate on dividends. Each tax year, the ATO applies tests—domicile, physical presence and intention—to determine where you stand. It pays to review your situation annually so you’re not caught off-guard at lodgement time.Resident Rates For Dividends
For Aussie residents, franked dividends come with an attached franking credit representing the 30% company tax already paid. Think of it as a prepaid tax voucher. When you lodge your return, you offset that credit against your personal tax bill. Unfranked dividends, however, land straight into your taxable income and get hit at your marginal rate. If you sit in the 34.5% bracket, there’s no franking credit to soften the blow. Key Points:- Franked Dividends carry a credit equal to the 30% company tax.
- Unfranked Dividends have no credit and attract full personal tax.
- You claim franking credits on lodgement to reduce tax payable.
- If your marginal rate is below 30%, excess credits become a refund.
Nonresident Withholding Rules
Non-residents pay a flat 30% withholding tax on most dividends. But thanks to Australia’s network of double tax agreements, that rate can drop significantly.Under many double tax agreements, withholding rates can drop from 30% to between 0–15% depending on country.A simple example: a UK resident typically sees withholding fall to 15% under the Australia–UK treaty. You simply supply your foreign tax ID and the ATO applies the reduced rate at source.
Side By Side Rate Comparison
Let’s walk through a $100 dividend to see who keeps what:| Profile | Dividend Type | Gross Amount | Tax Outcome |
|---|---|---|---|
| Resident | Fully Franked | $100 | $0 net tax after credits |
| Resident | Unfranked | $100 | $34.50 at 34.5% rate |
| Non-Resident | Any Dividend | $100 | $30 withheld (30%) |
| UK Resident* | Any Dividend | $100 | $15 withheld (15% treaty) |
Tips To Optimise Your Position
Smart planning can trim your tax on dividends:- Confirm your residency each year against ATO guidelines.
- Keep dividend statements and franking credit certificates organised.
- Apply the correct withholding rate under relevant double tax agreements.
- Seek professional advice to ensure compliance and spot savings.
Residency Test Example
Meet Maria, who arrived in Brisbane from Singapore on July 1 and leased a flat for six months. She intended to stay long-term, so the ATO treated her as an Australian resident.- Her dividend portfolio was registered to her Aussie address.
- She provided an Australian bank account for all payouts.
- On her tax return, franking credits wiped out company tax entirely.
How Franking Credits Work
When an Australian company pays you a franked dividend, it’s like receiving a prepaid tax voucher. Because the company has already met its 30% tax obligation on profits, you pick up that tax as a franking credit attached to your dividend. Think of each credit as a $1 store voucher you can use to offset your own tax bill.- The company pays tax at 30% on its profits.
- The dividend is then grossed up by the amount of tax already paid.
- A matching franking credit attaches to your dividend payment.
- https://youtube.com/shorts/EJmk8hRFMy4?feature=share
Gross Up And Offset Example
Let’s break it down with numbers. You receive a $70 franked dividend, but it’s grossed up to $100 because of the attached $30 credit. On your tax return, you declare the full $100 as assessable income. Then you claim back the $30 franking credit to reduce your tax liability. Dividend imputation has made Australia a go-to market for yield hunters. By offsetting personal tax with franking credits valued at the 30% corporate rate, investors across brackets enjoy healthier after-tax payouts. A $70 franked dividend grossed to $100 with a $30 credit not only cushions your tax but fuels stronger dividend policies. Discover more about high-dividend strategies in Australia through this S&P Global research.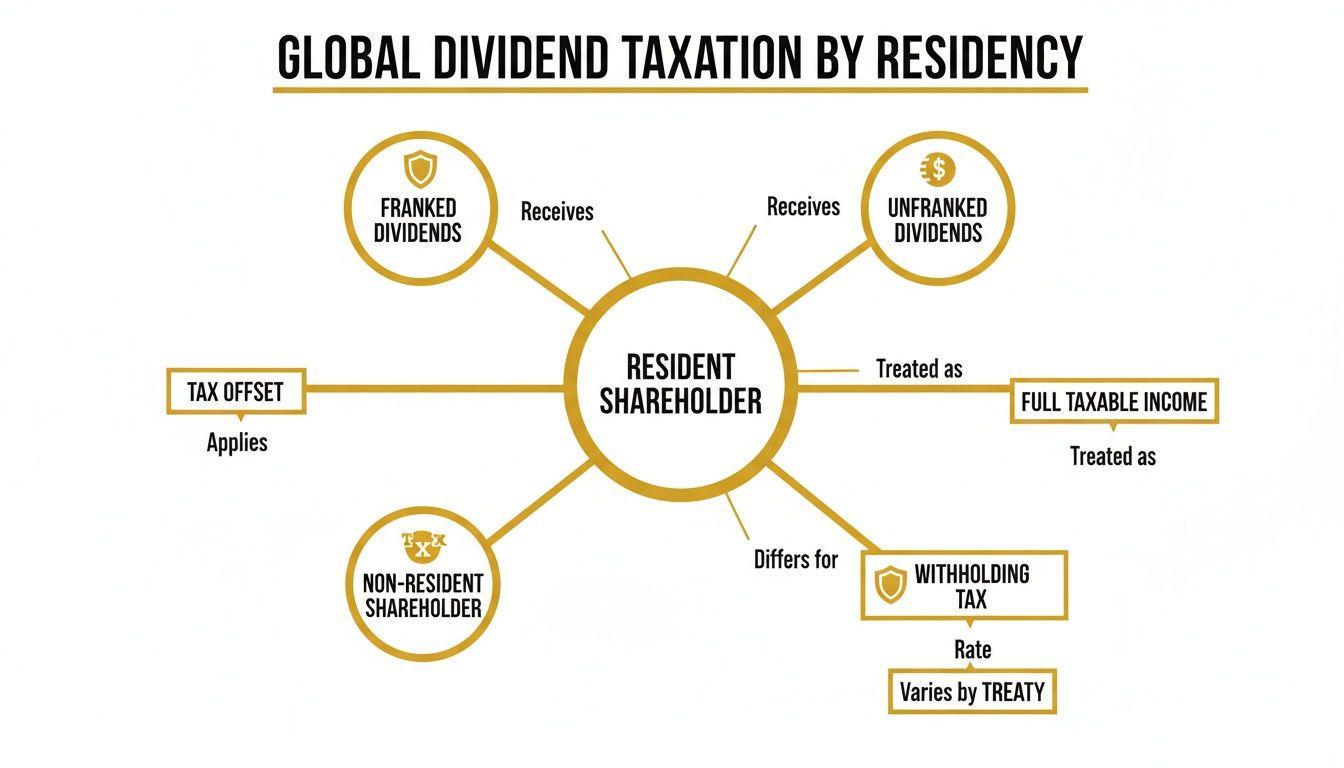
Tax Impact Across Brackets
How much you benefit depends on your marginal rate:| Marginal Rate | Dividend Grossed | Franking Credit | Tax Owing or Refund |
|---|---|---|---|
| 25% | $100 | $30 | $5 refund |
| 30% | $100 | $30 | $0 net tax |
| 45% | $100 | $30 | $15 owing |
“Franking credits are like prepaid tax vouchers that ensure you never pay tax twice.”Learn more about franking credits in our article on How Franking Credits Work
Common Misconceptions And Tips
- Misconception: Lower-rate taxpayers can’t get refunds. In fact, rates under 30% receive cash back.
- Misconception: Non-residents enjoy franking credits. They don’t—non-residents face withholding on unfranked portions.
- Tip: Check your dividend statement for the exact franking percentage.
- Tip: Lodge your return early to claim any refunds sooner.
How To Claim Your Credits
- Gather your dividend statements and note the franking details.
- Report the grossed-up dividend amount under your assessable income (Label 6).
- Enter the franking credits in the credits section of your tax return.
- Lodge online or via a tax agent before the deadline.
Practical Example For Investors
Sarah, a retiree on a 19% marginal rate, collects two fully franked dividends totalling $140. The grossed-up amount is $200 ($140 cash + $60 credit). Her tax on $200 at 19% is $38, but she holds $60 in credits—so she receives a $22 refund. Sarah also has unfranked dividends that flow straight into her assessable income. By blending franked and unfranked streams, she designs a diversified income plan with clear tax outcomes.Key Takeaway
Franking credits transform company tax into your own prepaid tax vouchers. Use the gross-up and credit steps to cut your liability or secure refunds—and boost the net return on your dividend income. Start planning today.Calculation Examples For Dividend Tax
Turning ideas into action is the best way to truly get dividend tax. Below, you’ll find three clear examples: a fully franked dividend for a middle-income resident, an unfranked payout for a high-income earner, and a non-resident withholding tax scenario. Each walk-through shows how to gross up dividends, apply the right rate, and land on your final tax number.Standard Steps For Dividend Tax Calculation
Before you dive into the maths, break the process into bite-sized tasks:- Decide if your dividend is franked or unfranked.
- Confirm your residency status for tax.
- Gross up franked dividends by adding the imputation credit to your assessable income.
- Apply your marginal rate (residents) or withholding rate (non-residents).
- Subtract the franking credit or withheld tax.
- Note your net cash result and any refund or payable amount.
Middle-Income Resident With Fully Franked Dividend
Imagine you’re on a 30% tax rate and you get a $70 fully franked dividend. You add the $30 imputation credit to report $100 of assessable income.- Grossed-up income: $100
- Attached franking credit: $30
- Tax on $100 at 30%: $30
- Credit offsets tax: $30
- Final tax payable: $0
“Franking credits prevent double taxation—and if your rate sits below the company rate, you might even get a refund.”Case Study: Emma picks up four fully franked dividends of $75 each from BlueCo. She ends up with no quarterly tax bill and even spots a small refund at year end, thanks to her 28% effective rate.
High-Earner Resident With Unfranked Dividend
Now picture a top-bracket earner on a 45% rate taking home a $1,000 unfranked dividend. With no franking credit to cushion the blow, the entire amount faces tax.- Dividend: $1,000
- Marginal rate: 45%
- Tax due: $450
| Component | Amount |
|---|---|
| Dividend received | $1,000 |
| Tax at 45% | $450 |
| Net cash after tax | $550 |
Non-Resident Withholding Tax Computation
Non-residents face a flat 30% withholding on dividends. If you’re paid $500, the ATO automatically takes $150, and you pocket $350.- Gross dividend: $500
- Withholding rate: 30%
- Tax withheld: $150
- Net payment: $350
Key takeaway: Always budget for withholding at source and explore any treaty benefits you can claim.If your home country has a 15% treaty rate—say, the UK—you can apply for the lower rate. On a $500 dividend, that saves you $75, leaving $425 in your account. Case Study: Li, studying in Australia, receives a $2,000 dividend and uses her UK tax ID to claim the 15% rate. She saves $300 compared to the standard 30% withholding.
Calculation Template For Your Portfolio
Here’s a template you can copy into your own spreadsheet:| Field | Value |
|---|---|
| Dividend amount | $ |
| Franking percentage | % |
| Gross-up calculation | $ |
| Franking credit | $ |
| Applicable tax rate | % |
| Tax on grossed income | $ |
| Tax withheld (non-resident) | $ |
| Final tax payable or refund | $ |
| Net dividend after tax | $ |
- Fill in your dividend amount and franking percentage.
- Calculate the grossed-up figure and credit.
- Apply your marginal or withholding rate.
- Deduct credits or withheld tax.
- Review your net cash and any refund.
Pro tip: Save a blank version of this table so you can plug in new dividend statements without reformatting.
Advanced Tips And Common Pitfalls
Attention to detail pays off. A small slip in your franking percentage or residency label can throw off the result.- Double-check your residency status if you move mid-year.
- Request a franking credit statement from the payer if it isn’t provided.
Reflection On Tax Opportunities
Looking across these examples reveals clear strategies:- Middle-income taxpayers often pay zero on fully franked dividends.
- High earners can boost after-tax returns by favouring franked shares.
- Non-residents should always verify treaty rates to cut withholding.
Lodgement And Compliance For Dividend Tax
Key Lodgement Steps
The first step is simple: collect all your dividend statements from share registries and franking credit certificates. Treat this as gathering the pieces of a puzzle. Next, log in to myTax or hand over your paperwork to a registered tax agent. Your goal here is to slot each figure into the right label in your tax return.- Step 1 Gather dividend statements and franking certificates to confirm exact amounts.
- Step 2 Report grossed-up dividends under Label 6 as part of your assessable income.
- Step 3 Enter total franking credits in the credits section to reduce your tax bill.
- Step 4 Double-check every figure to catch common data-entry errors.
Expert Insight: “Precise dividend reporting stops unexpected ATO queries in their tracks,” notes a senior AWTS tax adviser.Deadlines are non-negotiable. The standard lodgement date is 31 October, but if you’ve engaged an agent by then, you may qualify for an extended due date.
| Common Error | Fix |
|---|---|
| Missing franking credit | Cross-check your registry statement |
| Incorrect gross-up amount | Use the ATO’s official formula |
| Omitted dividend entry | Reconcile against all registry data |
Correcting Past Lodgement Errors
Under-claiming franking credits is like leaving money on the table. Don’t do it. Amendments delayed beyond two years can attract interest or penalties, so tackle them as soon as they surface.- Keep dividend statements and franking certificates organised for at least five years.
- Match dividend payments against your bank records.
- Archive copies of any correspondence with the ATO.
- For complex corrections, consider professional help from AWTS.
Record Keeping Best Practices
Think of your digital filing system as your safety net during audits and corrections. Create clear folders labelled by year and type, then drop all relevant documents inside.- Save dividend statements, franking certificates and broker confirmations together.
- Log arrival dates of statements and payments for quick cross-checks.
- Back up your files regularly and protect them with passwords.
- Retain records for a minimum of five years, per ATO rules.
Case Study: When John merged his spreadsheets with his broker’s data, he uncovered a missing $500 credit—right before lodgement.Solid record keeping isn’t just about avoiding chaos; it gives you confidence in every number. Start your lodgement process well ahead of deadlines, and you’ll reduce stress come tax time.
Frequently Asked Questions
First off, many investors ask: how exactly do residents claim franking credits on dividends? It all comes down to the gross-up and offset rules when you file your return. For instance, if you receive a $70 franked dividend, you’ll gross it up to $100 and show a $30 franking credit. You report the full $100 as income, then use that $30 credit to shave down your tax bill. Next, what withholding rates apply to non-residents? In most cases, a flat 30% is withheld from dividend payments at source.Common Scenarios
- Non-resident franked dividends face 30% withholding on their unfranked portion.
- Under double tax treaties, you might see that rate cut to 0–15%.
Clarity around dividend statements prevents costly mistakes and ensures you capture every franking credit.So, how do you stay on top of it all? Keep accurate dividend statements, make sure to lodge before the deadlines and consider a professional review for peace of mind. These FAQs should clear up the confusion around Australia’s tax on dividends and give you the confidence to lodge correctly.
- Download your dividend statement.
- Schedule a chat with an AWTS adviser for any questions.
Get clarity on your dividend tax with Australia Wide Tax Solutions
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
Navigating the Path to Registering a Company in Australia
Starting a business in Australia can be an exciting and rewarding journey, but navigating the necessary legal and administrative steps is essential to ensure a smooth process. One of the crucial first steps is registering your company with the appropriate authorities. In this comprehensive blog post, we'll guide you through the essential elements of registering a company in Australia, covering everything from the different business structures to the registration process and the ongoing compliance requirements.
- Navigating the Path to Registering a Company in Australia
- Understanding Business Structures in Australia
- The Company Registration Process in Australia
- A Apply for a Director Identification Number
- Ongoing Compliance Requirements
Understanding Business Structures in Australia
Before registering your company, it's essential to determine the most suitable business structure for your venture. Australia offers several options, each with its advantages and considerations:
Sole Trader
As a sole trader, you'll be operating the business as an individual, with complete control over the decision-making and the profits. This structure is relatively simple to set up and maintain, but you'll be personally liable for any debts or liabilities incurred by the business.
Partnership
A partnership involves two or more individuals or entities cooperating to operate the business. Partnerships can be general, limited, or incorporated, each with its legal and financial implications. Careful consideration of the partnership agreement is crucial to ensure a harmonious and successful collaboration.
Company
Registering as a company is a more formal business structure, which provides shareholders with limited liability. Companies can be proprietary (Pty Ltd) or public (Ltd), and the registration process is more involved than a sole trader or partnership.
Trust
A trust is a legal arrangement in which a trustee holds and manages assets on behalf of the beneficiaries. Trusts can be used for various purposes, such as estate planning, asset protection, or business operations.
Cooperative
A cooperative is a business structure owned and controlled by its members, who share the risks and benefits of the enterprise. Cooperatives are often used in agriculture, housing, or consumer goods industries.
The Company Registration Process in Australia
Once you've determined the most suitable business structure, it's time to begin the company registration process. Here are the key steps:
A Apply for a Director Identification Number
Set up your digital ID.
1. Choose a Company Name
Selecting a unique and memorable company name is an important first step. Your chosen name must be available and comply with the Australian Securities and Investments Commission (ASIC) naming guidelines.
2. Register the Company
To officially register your company, you'll need to submit the necessary forms and documentation to ASIC, the government agency responsible for company registrations. This includes providing details such as the company name, directors, shareholders, and registered office address.
3. Obtain an Australian Business Number (ABN)
An ABN is a unique 11-digit number that identifies your business to the Australian Taxation Office (ATO) and other government agencies. You can apply for an ABN as part of the company registration process.
4. Register for Goods and Services Tax (GST)
Depending on your business's annual turnover, you may be required to register for GST, which is a broad-based consumption tax levied on the supply of goods and services in Australia.
5. Obtain Necessary Licenses and Permits
Depending on the nature of your business, you may need to obtain additional licenses or permits from local, state, or federal authorities. This could include industry-specific licenses, trade licenses, or environmental permits.
6. Set Up Business Accounts and Insurance
To manage your company's finances effectively, you'll need to set up business bank accounts and consider appropriate insurance coverage, such as public liability, professional indemnity, or workers' compensation insurance.
Ongoing Compliance Requirements
Registering your company is just the first step; maintaining compliance with the various legal and regulatory requirements is an ongoing process. Here are some of the key ongoing obligations:
Annual Returns and Financial Reporting
All registered companies in Australia must submit annual returns and financial reports to ASIC, detailing the company's activities and financial performance.
Tax Obligations
Companies in Australia are required to pay various taxes, including corporate income tax, GST, and payroll tax (if you have employees). Ensuring accurate and timely tax filings is crucial to avoid penalties and maintain good standing with the ATO.
Employee-related Obligations
If you have employees, you'll need to comply with workplace laws, including payroll, superannuation contributions, and workplace health and safety requirements.
Changes to Company Details
Whenever there are changes to your company's details, such as the registered office address, directors, or shareholders, you'll need to notify ASIC in a timely manner.
Benefits of Registering a Company in Australia
Registering your company in Australia offers several benefits:
- Limited Liability: As a company, your personal assets are generally protected from the debts and liabilities of the business, providing a layer of legal and financial protection.
- Credibility and Professionalism: A registered company is seen as a more credible and professional business entity, which can help you attract customers, partners, and investors.
- Tax Advantages: Companies in Australia may be eligible for certain tax deductions and incentives that are not available to sole traders or partnerships.
- Scalability and Growth: The company structure allows for easier expansion and the ability to bring on additional shareholders or investors as the business grows.
- Perpetual Succession: A registered company has a continuous legal existence, which means it can continue operating even if the original owners or directors change.
Preparing for Company Registration
Before you begin the registration process, it's important to have the following information and documents ready:
- Proposed company name and any alternative options
- Details of the company's directors, shareholders, and their contact information
- The company's registered office address and principal place of business
- The company's proposed business activities and industry
- Any required licenses or permits for your specific industry
- Financial information, such as projected revenue and startup capital
Conclusion
Registering a company in Australia is a crucial step in establishing a successful and compliant business. By understanding the different business structures, navigating the registration process, and fulfilling the ongoing compliance requirements, you'll be well on your way to turning your entrepreneurial dreams into reality.
Remember, seeking professional advice from accountants, lawyers, or business advisors can be invaluable in ensuring a smooth and successful company registration process. With the right preparation and guidance, you can confidently embark on your journey as a registered Australian business.
Text us for a quote tel:0488854200
The four main structures are sole trader, partnership, company, and trust. A sole trader is simplest and cheapest but offers no liability protection. A company provides limited liability at a flat tax rate but costs more to run. A trust offers tax flexibility and asset protection but is complex to administer. The right choice depends on income, risk profile, and growth plans.
Base rate entities — companies with aggregated turnover under $50 million that derive no more than 80% of income from passive sources — pay 25%. All other companies pay 30%. Shareholders pay income tax on dividends, potentially offset by franking credits for tax already paid at the corporate level.
Consider a company when business net profit consistently exceeds $100,000–$120,000 and the rate differential generates meaningful savings, when you need liability protection from business creditors, when you plan to bring in investors, or when you want to retain earnings at the lower corporate rate rather than distributing everything as personal income.
A family trust (discretionary trust) holds assets for a class of beneficiaries. The trustee decides each year how much income to distribute to each beneficiary. By directing income to members in lower tax brackets, the trust reduces the overall family tax burden. Income retained in the trust is taxed at the highest marginal rate (47%).
Ongoing costs include the ASIC annual review fee (currently $310 for a proprietary company), company tax return lodgement fees, accounting fees for financial statements, and potentially payroll and BAS compliance. Total annual compliance costs typically range from $2,000 to $8,000 depending on activity levels and complexity.