
A Guide for Investors
- Your Guide to Understanding Franking Credits
- How Franking Credits Work: A Practical Breakdown
- Who Can Actually Claim Franking Credits
- The True Impact of Franking Credits on Your Portfolio
- Three Real-World Scenarios for Claiming Credits
Ever glanced at your dividend statement and been stumped by the term 'franking credit'? You're not alone. Think of a franking credit as a tax voucher that comes attached to dividend payments from Australian companies.
The whole system is designed to solve one simple problem: preventing company profits from being taxed twice. It stops the tax man from taking a slice when the company earns the profit, and then another slice from you when you receive it as a dividend.
Your Guide to Understanding Franking Credits
At its heart, the franking credit system is all about tax fairness. When an Australian company turns a profit, it pays company tax to the ATO. Simple enough. But when it decides to share those post-tax profits with shareholders, those dividends are called 'franked'.
The attached franking credit is a record of the tax the company has already paid on your slice of the profit.
This clever setup, known as the dividend imputation system, kicked off back in 1987. It lets you, the shareholder, claim a credit for the company tax that's already been settled. The goal is to stop that double taxation and give investor returns a welcome boost.
Why This Matters to You
Getting your head around this is the first real step to making your investments work harder for you. For any Aussie investor, these credits can have a massive impact on your after-tax income.
It’s like the company has pre-paid a chunk of your tax bill. When you do your tax return, you declare both the dividend you received and the franking credit as income. But here's the kicker: you also get to subtract the full credit amount from the tax you owe.
This has some powerful implications, especially for different types of investors:
- Tax Reduction: It directly slashes the amount of tax you owe on your investment earnings.
- Potential Refunds: This is where it gets really interesting. If your personal tax rate is lower than the company tax rate (usually 30%), the ATO will actually pay you the difference in cold, hard cash.
- Strategic Investing: It makes investing in dividend-paying Aussie shares incredibly attractive, particularly if you're in a lower tax bracket or enjoying retirement.
By effectively turning a company's tax payment into a personal tax credit, the system ensures that profits are taxed only once, at the shareholder's marginal tax rate.
If you're just starting to dip your toes into the world of shares and want to build a solid foundation for growing your wealth, our guide on stock market investing for beginners is a great place to start.
How Franking Credits Work: A Practical Breakdown
To really get your head around franking credits, we need to ditch the theory and look at how they play out in the real world. When you get a dividend from an Australian company, the statement will tell you if it's 'fully franked' or 'partially franked'.
A fully franked dividend means the company has already paid tax at the full corporate rate (usually 30%) on its profits before sending you your share.
A partially franked dividend means only some tax has been paid, and an 'unfranked' dividend means no Australian tax was paid on that profit at all. The franking credit amount attached to your dividend is your ticket to a tax benefit.
This flowchart maps out the basic journey, from a company making a profit to you receiving a franked dividend with those valuable credits attached.

As you can see, the process starts with company profit. The ATO takes its cut via company tax, and what's left is paid out to you, the shareholder, along with a credit for the tax already paid.
The All-Important Gross-Up Process
Here’s a crucial step that trips a lot of people up. When you do your tax return, you don't just declare the cash dividend that landed in your bank account. The Australian Taxation Office (ATO) requires you to 'gross-up' your dividend income.
It sounds technical, but it’s really just adding the franking credit amount back onto the cash dividend you received. This step is designed to show the full, pre-tax amount of your share of the company's profit.
Let's walk through it. Imagine you own shares in an Australian company and receive a fully franked dividend of $70. Your dividend statement also notes a franking credit of $30.
- Step 1 Cash Dividend: You receive $70 in your bank account.
- Step 2 Franking Credit: Your statement shows a $30 imputation credit.
- Step 3 Gross-Up: You must add these two figures together: $70 + $30 = $100.
So, for tax purposes, you declare $100 of income, not just the $70 cash you received.
To make this crystal clear, here's how the franking credit is calculated and then 'grossed up' with the dividend. This example assumes a 30% corporate tax rate.
Franked Dividend Calculation Example
| Step | Calculation | Example (on $70 Dividend) | Description |
|---|---|---|---|
| 1. Find the Gross-Up Factor | Corporate Tax Rate / (1 - Corporate Tax Rate) | 0.30 / (1 - 0.30) = 0.42857 | This factor converts the post-tax dividend back to its pre-tax value. |
| 2. Calculate Franking Credit | Cash Dividend x Gross-Up Factor | $70 x 0.42857 = $30 | The franking credit represents the tax already paid by the company. |
| 3. Calculate Grossed-Up Dividend | Cash Dividend + Franking Credit | $70 + $30 = $100 | This is the total pre-tax income you must declare to the ATO. |
This table shows the maths behind the scenes, but your dividend statement will thankfully provide you with the key figures: the cash dividend and the franking credit.
The 'grossed-up' amount represents your share of the company's profit before it paid any tax. This is the figure the ATO uses to calculate your tax liability.
This step is critical because it puts the pre-tax profit back on the table, which allows the tax system to work fairly from there.
How Franking Credits Reduce Your Tax Bill
Once you’ve declared the grossed-up income of $100, the ATO calculates the tax you owe on it based on your personal marginal tax rate. And this is where the magic happens.
That $30 franking credit isn't just a number on a statement; it acts like a tax pre-payment you can use to slash your tax bill.
Let's say your personal tax rate is 19%. On your $100 of grossed-up dividend income, the tax would be $19.
Because you have a $30 credit sitting there, you can use it to completely wipe out that $19 tax bill. Better yet, you still have $11 left over ($30 credit - $19 tax). The ATO will pay this excess amount back to you as a cash refund.
This simple example shows just how franking credits work to either reduce your tax or even put cash back in your pocket, making them a powerful tool for savvy investors.
Who Can Actually Claim Franking Credits
Getting a dividend statement with franking credits attached is a great start, but it doesn’t automatically mean you get to use them. The Australian Taxation Office (ATO) has a few key rules you need to meet, designed to make sure the system is used fairly and as it was intended.
First and foremost, you have to be an Australian resident for tax purposes. The entire franking credit system is a feature of our local tax laws, so it’s generally not available to non-residents filing an Australian tax return.
Beyond residency, the ATO has put some important integrity rules in place. These exist to stop people from trying to game the system by buying shares just to grab the tax credit, without ever having any real skin in the game.
The Critical Holding Period Rule
One of the biggest integrity measures is the holding period rule, which you’ll often hear called the “45-day rule.” It’s a make-or-break condition for many investors.
To be eligible for franking credits, you must hold the shares “at risk” for a continuous period of at least 45 days. Critically, this clock doesn’t include the day you buy the shares or the day you sell them.
The whole point of the holding period rule is to stamp out a practice called "dividend washing." This is where someone buys shares right before a dividend is paid and then sells them straight after, just to pocket the franking credits without taking on any genuine investment risk.
The ATO wants to see that you’re a real investor, not just a trader popping in for a quick tax benefit. By holding the shares for that minimum period, you’re exposed to the normal market fluctuations, which proves your investment is truly “at risk.”
Are There Any Exceptions to This Rule?
Yes, and it’s a big one that helps out most everyday investors. It’s known as the small shareholder exemption.
You’re exempt from the 45-day rule if the total value of the franking credits you’re claiming for the financial year is less than $5,000. This makes life much simpler for individuals with smaller share portfolios, as you don't have to stress about tracking the holding period for every single parcel of shares.
Eligibility for Different Entities
It’s not just individual investors who can claim franking credits, though the specifics can change depending on the structure.
- Self-Managed Super Funds (SMSFs): SMSFs are huge beneficiaries of the franking credit system. Whether the fund is in the accumulation phase (taxed at 15%) or the pension phase (taxed at 0%), it can use the credits to slash its tax bill or even get a full cash refund.
- Trusts and Partnerships: If you get franked dividends through a trust or partnership, the franking credits are usually passed straight through to you as the beneficiary or partner. You then claim them on your personal tax return, where all the same eligibility rules apply.
Getting your head around these criteria is vital. It’s the difference between correctly claiming every credit you’re entitled to and potentially missing out—or worse, making a mistake that attracts the ATO’s attention.
The True Impact of Franking Credits on Your Portfolio
Franking credits are much more than just a small entry on your annual tax return; they are a powerful force that actively shapes investment strategies and total returns for anyone holding Australian shares. Their real magic lies in how they boost the after-tax income you receive from local companies, making them an incredibly attractive asset for Australian investors.
This tax advantage is so significant that it’s one of the main reasons for a well-known investor habit called ‘home bias’. It’s the tendency for Australians to invest more heavily in local shares than they might otherwise. The franking credit system is a huge part of that pull.
How the Market Prices In Franking Credits
Now, it’s important to understand that the value of a franking credit isn't always a straight dollar-for-dollar win. The stock market is a pretty efficient beast, and it tends to 'price in' the expected value of these tax credits. In simple terms, the share prices of companies known for paying fully franked dividends often already reflect this benefit.
You can see this in action when a company’s stock goes ‘ex-dividend’. The share price will typically drop by an amount close to the cash dividend plus a portion of the franking credit’s value. This market adjustment is why simply chasing stocks with the highest franked dividend yields isn't a guaranteed winning strategy.
The actual value an investor pockets is shaped by this market pricing. In fact, research suggests that franking credits are often 40-80% priced-in to a company's share value. This means investors don't always capture the full face value of the credit as a pure bonus.
Franking Credits and Your Overall Returns
Grasping this concept is vital when you're trying to balance your portfolio. While international shares are great for diversification, they don't offer franking credits. That makes a direct comparison of their dividend yields against Australian shares completely misleading. To get the full picture of how franking credits contribute to your wealth, it's critical to understand the mechanics of accurately calculating portfolio returns.
The real value of a franked dividend isn’t just the cash that lands in your bank account; it’s the grossed-up dividend yield minus the tax you ultimately pay. For investors on low or zero tax rates, this can deliver a return that easily beats unfranked or international dividends.
This effective boost to your returns is a cornerstone of investing in Australia. It gives you the proper context when deciding how to allocate your money between local and global shares, ensuring you're comparing apples with apples. For a deeper look at the tax side of things, our guide on dividend tax in Australia offers even more detail.
Ultimately, franking credits transform Australian shares into a unique asset class, offering tax benefits that are almost impossible to find anywhere else in the world.
Three Real-World Scenarios for Claiming Credits
Theory is great, but it only gets you so far. The best way to really grasp the power of franking credits is to see them in action with real numbers and different financial situations. It's your personal marginal tax rate that truly dictates how much value you get from these credits.
Let's walk through three common investor profiles to see how the numbers play out. For each one, we'll use the same simple example: an investor receives a $70 fully franked dividend which comes with a $30 franking credit. This means they have to declare a total of $100 in grossed-up income to the ATO.
As you'll see, the final result is dramatically different for each person.
The High-Income Earner at 45 Percent
First up is Alex, a high-income earner whose marginal tax rate is 45%. For simplicity, we'll ignore the Medicare levy in these examples. When Alex does their tax return, they declare the $100 grossed-up dividend.
The ATO calculates the initial tax on this income:
- Tax Calculation: $100 (Grossed-Up Income) x 45% (Tax Rate) = $45.00
Without franking credits, Alex would owe the tax office $45 on that dividend. But this is where the $30 franking credit steps in, acting as a direct discount on their tax bill.
- Final Tax Payable: $45.00 (Initial Tax) - $30.00 (Franking Credit) = $15.00
Instead of a $45 tax hit, Alex only has to pay an extra $15. The franking credit has effectively slashed their tax bill on this dividend by two-thirds.
The Average Income Earner at 32.5 Percent
Now, let's look at Ben, who's in the 32.5% marginal tax bracket. Just like Alex, Ben declares $100 of grossed-up dividend income from the same investment.
The ATO's initial calculation for Ben is a bit lower:
- Tax Calculation: $100 (Grossed-Up Income) x 32.5% (Tax Rate) = $32.50
Ben's initial tax bill is $32.50. He then applies his $30 franking credit to offset this.
- Final Tax Payable: $32.50 (Initial Tax) - $30.00 (Franking Credit) = $2.50
The franking credit has almost completely wiped out the tax Ben would have otherwise paid. He’s left with a tiny $2.50 tax bill on his dividend income, showing just how well the system aligns the tax paid with an individual's actual tax rate.
The Retiree in Pension Phase at 0 Percent
Finally, we have Chloe, a retiree whose Self-Managed Super Fund (SMSF) is entirely in the pension phase. This is critical because her fund's tax rate is 0%. This is where franking credits reveal their most powerful side.
Chloe's SMSF also declares the $100 grossed-up dividend income.
- Tax Calculation: $100 (Grossed-Up Income) x 0% (Tax Rate) = $0.00
Because the fund is tax-free, its initial tax liability is zero. But the $30 franking credit doesn't just vanish.
Since there's no tax bill to reduce, the franking credit can't be used as an offset. Instead, the ATO treats this excess credit as an overpayment of tax and refunds the full amount in cash.
- Final Outcome: $0.00 (Initial Tax) - $30.00 (Franking Credit) = -$30.00
Chloe’s SMSF receives the $70 cash dividend and then gets an additional $30 cash refund directly from the ATO at tax time. Her total return is $100, completely tax-free, highlighting why franking credits are such a vital source of income for many Australian retirees.
Why Franking Credits Are a Cornerstone for SMSFs
For many Aussie retirees, franking credits aren't just a nice little tax-time bonus. They're a fundamental pillar of their retirement income strategy, especially for those running their own super. This is particularly true for Self-Managed Super Funds (SMSFs), where the ability to get cash refunds for excess credits can create a significant and reliable income stream.
This powerful outcome happens whenever a fund's tax rate is lower than the corporate tax rate of 30% that the dividend was franked at.
Let's look at an SMSF in the accumulation phase. It pays tax at just 15%. When it receives a franking credit (which represents tax already paid at 30%), it can use that credit to wipe out its own tax bill and then get the remaining 15% back from the ATO as a straight cash refund.
The Power of the Zero Percent Tax Rate
The benefit gets even better for an SMSF in the pension phase, where its earnings are completely tax-free.
When an SMSF in the pension phase has a 0% tax rate, it has no tax bill to reduce. Consequently, the Australian Taxation Office (ATO) refunds the entire franking credit amount in cash, directly boosting the fund's returns.
This unique feature has made dividend-paying Australian shares a go-to asset for countless retirees. Getting the structure right is key, and you can learn more in our detailed guide explaining what an SMSF is. This direct cash injection effectively pumps up the yield on their investments, providing crucial income to fund their retirement lifestyle.
A Politically Sensitive Topic
The refundability of these credits has made them a hot-button political issue, largely because the benefits tend to flow to older, wealthier Australians.
The Parliamentary Budget Office (PBO) once estimated that a massive 60% of the revenue from a 2018-2019 proposal to axe cash refunds would have come from SMSFs. The bulk of that would have been from the top 10% of funds with the largest balances.
Despite the ongoing debates, cash refunds for excess franking credits remain a vital part of the Australian superannuation landscape for now.
Common Questions About Franking Credits
Even after getting your head around the basics, a few common questions always seem to pop up for investors new to franking credits. We've pulled together the most frequent ones we hear to give you some quick, clear answers.
Do Franking Credits Only Apply to Australian Residents?
Yes, absolutely. The ability to claim franking credits is a unique feature of the Australian tax system, designed to benefit local investors. You must be an Australian resident for tax purposes to use these credits to lower your tax bill or get a cash refund.
Unfortunately for overseas investors, non-resident shareholders generally can't claim these credits on their Australian tax returns.
What Is a Partially Franked Dividend?
Good question. A partially franked dividend simply means the company has only paid some Australian tax on its profits before paying you. Because of this, only a portion of your dividend payment will have a franking credit attached.
The rest of the dividend is considered 'unfranked' income, which you’ll still need to declare, but without the tax credit benefit.
Is There a Limit to How Much I Can Claim?
For most everyday investors, the main rule to be aware of is the small shareholder exemption. This is a handy shortcut designed to simplify things.
If your total franking credits for the financial year are less than $5,000, you’re exempt from the tricky 45-day holding period rule. This makes claiming your credits much more straightforward.
Navigating dividend income and franking credits can feel like a maze, but you don't have to figure it out on your own. The experts at Australia Wide Tax Solutions can make sure you tick all the boxes and get the maximum tax refund you're entitled to. Book your appointment online today.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
A franked dividend is a payment you receive as a shareholder from an Australian company that has already paid tax on its profits. The real magic, though, is the franking credit that comes attached—think of it as a pre-paid tax voucher just for you.
- Why Franked Dividends Exist: Solving the Double Taxation Problem
- Putting Franking Credits To Work: A Practical Example
- How to Claim Franking Credits on Your Tax Return
- Navigating the Modern Landscape of Franked Dividends
- Answering Your Top Questions About Franked Dividends
Essentially, the company has already settled a portion of your tax bill on that dividend income before it even hits your bank account.
What Are Franked Dividends in Simple Terms?
Let's break it down. Imagine a company you've invested in makes a profit. Before it can share that profit with its shareholders, it first has to pay company tax to the Australian Taxation Office (ATO). A franked dividend is simply your slice of the pie after the company has paid its tax.
The entire system was created to fix one huge problem for investors: double taxation. Without it, a company's profit would be taxed once at the corporate level, and then you'd get taxed on it again when you receive your dividend. Franking credits put a stop to that.
The core idea is simple yet powerful: company profits should only be taxed once, at the shareholder's marginal tax rate. Franking credits are the mechanism that makes this possible, ensuring a fairer and more efficient tax system for investors.
This process is a game-changer. It turns what could be a tax headache into a tax-effective way to earn investment income. For many Aussies trying to build passive income with dividend stocks, understanding franked dividends is the key to a successful strategy.
Fully Franked vs Unfranked Dividends
Now, not all dividends are the same. The amount of tax a company has paid on its profits determines whether your dividend is fully franked, partially franked, or unfranked. Each one affects your tax situation differently.
A fully franked dividend means the company paid tax at the full corporate rate (currently 30% for large companies) on the profit it's sharing with you. A partially franked dividend means only some tax was paid. And an unfranked dividend means no Australian tax was paid on those profits at all, which often happens when the profits were earned overseas.
You can dive deeper into how different dividends pay tax in Australia in our detailed guide.
Franked vs Unfranked Dividends at a Glance
To make it even clearer, this table breaks down the key differences between the types of dividends you might receive. It’s a quick way to see how each one impacts your bottom line.
| Dividend Type | Company Tax Paid? | Franking Credit Attached? | Impact on Shareholder's Tax |
|---|---|---|---|
| Fully Franked | Yes, at the full corporate rate. | Yes, a full credit is attached. | Significantly reduces your personal tax payable, may result in a refund. |
| Partially Franked | Yes, but at less than the full rate. | Yes, a partial credit is attached. | Reduces your personal tax payable, but less than a fully franked dividend. |
| Unfranked | No Australian tax paid. | No, there is no credit attached. | The full dividend amount is added to your taxable income and taxed at your marginal rate. |
This distinction is absolutely crucial because it directly shapes your after-tax return. As we'll get into, your personal tax rate is what ultimately determines whether these credits mean you pay less tax or even get a cash refund from the ATO.
Why Franked Dividends Exist: Solving the Double Taxation Problem
To really get your head around franked dividends, you first need to understand why they even exist. They’re not just some quirky feature of the Aussie market; they were a purpose-built solution to a major headache that used to plague shareholders: double taxation.
Picture this: before 1987, the system was seriously flawed. A company would make a profit and, quite rightly, pay company tax on it. But when it shared what was left with its owners (the shareholders) as a dividend, those investors had to pay income tax on that exact same money all over again.
That meant a single dollar of profit was getting taxed twice—once in the company's hands, and a second time in the shareholder's. This created a huge drag on investment returns and gave companies very little incentive to pay dividends. It just wasn't fair.
The Fix: Australia’s Dividend Imputation System
Recognising how inefficient this was, the Australian government rolled out the dividend imputation system in 1987. The goal was simple but powerful: make sure that company profits paid out to Australian shareholders are only taxed once, at that shareholder's personal tax rate.
This completely changed the game for local investors. It effectively got rid of the double taxation penalty and created one of the most shareholder-friendly dividend systems in the world. The magic ingredient? Franking credits. When a company pays tax on its profits, it generates these credits, which it can then "impute" or attach to the dividends it pays out.
At its heart, the dividend imputation system is about fairness. It treats the tax paid by the company as a pre-payment of tax on behalf of its shareholders. It’s like the company has already taken care of a chunk of your tax bill for you.
This clever setup directly connects the tax paid by a company to the tax its owners owe. For Australian resident investors, it makes the whole process far more transparent and equitable.
How It Stops Double Taxation in its Tracks
The process itself is quite straightforward, but the impact is massive. Let’s follow a dollar of profit from the company’s bank account to yours.
- A Company Earns a Profit: An Australian company makes $100 in pre-tax profit.
- The Company Pays Tax: Assuming a 30% corporate tax rate, the company pays $30 in tax to the ATO. This leaves it with $70 of after-tax profit.
- A Dividend is Paid: The company decides to pay out this entire $70 to you as a fully franked dividend.
- A Franking Credit is Attached: Here’s the key part. Along with the $70 in cash, the company attaches a $30 franking credit—the exact amount of tax it already paid on that original profit.
When it comes to your tax return, you have to declare the full pre-tax amount of $100 as income (your $70 cash dividend + the $30 franking credit). But the good news is, you also get a $30 tax credit to lower your final tax bill. That’s the mechanism that prevents the tax from being paid twice.
Australia's dividend imputation system, introduced in 1987, fundamentally changed how dividends are taxed. It was specifically designed to solve the problem where companies paid tax on earnings at the corporate rate of 30%, and then shareholders paid tax again on the dividends they received. By attaching franking credits, the system allows you to offset your personal income tax liabilities, which can even result in refunds from the ATO. You can explore more about how analysts view these high-dividend strategies on S&P Global.
Putting Franking Credits To Work: A Practical Example
Understanding the theory behind franked dividends is one thing, but seeing how they actually hit your tax return is where it all clicks. Let’s walk through a real-world, step-by-step calculation to see just how much these tax credits can affect your bottom line.
First, we have to tackle a concept called 'grossing up' the dividend. It sounds complicated, but it’s not. Before you work out the tax, you simply add the value of the franking credit back to the cash dividend you received. This total amount represents the company's full, pre-tax profit that your dividend was paid from, and it’s this 'grossed-up' figure you declare as income.
The Core Calculation
Imagine you own shares in an Australian company and receive a fully franked dividend payment of $700 in cash. Nice.
Let's say the company pays tax at the corporate rate of 30%. To figure out the franking credit attached to your dividend, we use a straightforward formula:
Franking Credit = (Cash Dividend Amount / (1 - Company Tax Rate)) - Cash Dividend Amount
Plugging our numbers in:
($700 / (1 - 0.30)) - $700 = ($700 / 0.70) - $700 = $1,000 - $700 = $300
So, your $700 cash dividend comes with a $300 franking credit. Your total 'grossed-up' dividend income for tax purposes is now $1,000. This is the amount you'll add to your assessable income on your tax return.
This flowchart shows how that profit flows from the company, through the tax system, and finally to you as a dividend with the tax credit already attached.
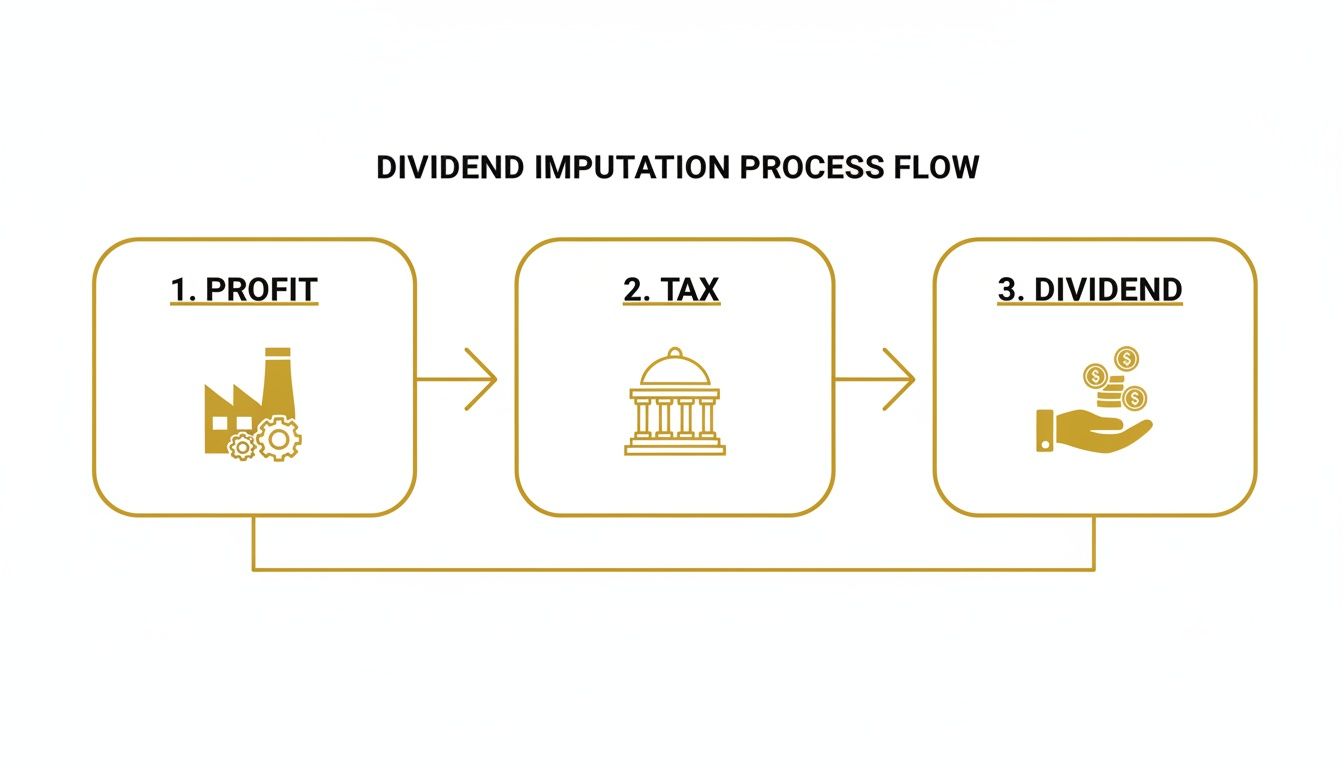
As you can see, the tax the company paid on its profits is passed directly to you, the shareholder, as a franking credit.
How Your Tax Rate Changes Everything
Now for the magic. The final result—whether you pay more tax, break even, or get a refund—boils down to how your personal marginal tax rate stacks up against the 30% corporate tax rate the company already paid.
Let's run the numbers for three different investors, all receiving the same $1,000 grossed-up dividend.
To make this crystal clear, here’s a quick summary of how the same franked dividend impacts investors on different tax rates.
Franking Credit Impact by Marginal Tax Rate
| Investor's Marginal Tax Rate | Tax on Grossed-Up Dividend ($1,000) | Franking Credit Offset | Final Outcome (Tax Payable / Refund) |
|---|---|---|---|
| 47% (High-Income Earner) | $470 | -$300 | $170 Tax Payable |
| 32.5% (Middle-Income Earner) | $325 | -$300 | $25 Tax Payable |
| 19% (Low-Income Earner/Retiree) | $190 | -$300 | $110 Tax Refund |
Let's break down each of those scenarios.
Scenario 1: The High-Income Earner (47% Marginal Tax Rate)
An investor in the top tax bracket still gets a huge benefit, but the credit doesn't cover their entire tax bill on the dividend.
- Total Taxable Income: $1,000
- Tax Payable Before Credit (at 47%): $1,000 x 0.47 = $470
- Less Franking Credit: -$300
- Final Outcome: $170 Tax Payable
Without the franking credit, this investor would have owed $470. Instead, they only need to pay the $170 difference—a massive saving. If you want a deeper dive into how do franking credits work, our detailed guide has you covered.
Scenario 2: The Middle-Income Earner (32.5% Marginal Tax Rate)
For someone whose tax rate is just a touch above the corporate rate, the system works to almost completely wipe out their tax bill.
- Total Taxable Income: $1,000
- Tax Payable Before Credit (at 32.5%): $1,000 x 0.325 = $325
- Less Franking Credit: -$300
- Final Outcome: $25 Tax Payable
In this case, the investor only pays a tiny "top-up" tax of $25. The company has already covered the vast majority of their tax liability for them.
Scenario 3: The Low-Income Earner or Retiree (19% Marginal Tax Rate)
This is where the dividend imputation system really flexes its muscles. For investors with a marginal tax rate lower than the company’s, the outcome isn’t just zero tax—it’s a cash refund from the ATO.
- Total Taxable Income: $1,000
- Tax Payable Before Credit (at 19%): $1,000 x 0.19 = $190
- Less Franking Credit: -$300
- Final Outcome: $110 Tax Refund from the ATO
Because the investor's tax liability ($190) is less than the tax credit ($300), the ATO refunds the $110 difference directly to them. This makes fully franked dividends an incredibly powerful source of income for retirees and people on lower incomes.
How to Claim Franking Credits on Your Tax Return
Receiving a franked dividend is a fantastic perk for any investor, but the real magic only happens when you correctly claim the credits on your annual tax return. This isn't just about ticking a box; it's about understanding your dividend statements and navigating a few key eligibility rules set by the Australian Taxation Office (ATO).
Think of it like this: the company has handed you a tax voucher. It's now your job to cash it in with the ATO. Getting this right is what turns a good investment return into a great one, either by slashing your tax bill or landing a welcome refund.
Decoding Your Dividend Statement
First things first, you need to know where to find the right information. Whenever a company pays you a dividend, you'll get a dividend statement, either in the mail or electronically. This little document is your treasure map for tax time.
It contains all the crucial figures, but you have to know what you’re looking for. Keep an eye out for these specific items:
- Cash Dividend Paid: This is the actual amount of money that hit your bank account.
- Franking Credit (or Imputation Credit): This is the value of the tax credit the company has passed on to you.
- Franked Amount: The portion of your cash dividend that has a franking credit attached.
- Unfranked Amount: Any portion of the dividend that came without a credit.
Here's the most important step: you must add the cash dividend and the franking credit together. This "grossed-up" figure is what you declare as assessable income. It might seem strange to declare more income than you received, but it’s the only way to claim the credit. For a deeper dive, check out our guide on dividend tax in Australia.
Meeting the Key Eligibility Rules
Before you can claim those valuable credits, the ATO has a few conditions you need to meet. The biggest one is the holding period rule, which you’ll often hear called the "45-day rule." This rule is there for one reason: to stop people from buying shares just before a dividend is paid and selling them straight after simply to pocket the credit—a tactic known as "dividend stripping."
To satisfy the rule, you have to hold the shares "at risk" for a continuous period of at least 45 days. This period doesn't include the day you buy or the day you sell. For some preference shares, this extends to 90 days.
The "at risk" part is absolutely critical. It means you must be genuinely exposed to the financial ups and downs of owning the shares. If you use certain financial products to protect yourself from any loss in the share's value during that time, the ATO might decide you weren't truly "at risk" and deny your claim to the credits.
This rule makes sure that the benefits of the dividend imputation system go to genuine, long-term investors, not short-term opportunists.
Exceptions to the Holding Period Rule
Thankfully, the ATO applies some common sense for smaller investors, making the process much simpler.
You are generally exempt from the 45-day rule if you're an individual investor and your total franking credit entitlement for the entire financial year is less than $5,000. This is known as the "small shareholder exemption," and it covers the vast majority of everyday retail investors.
There are a couple of other specific situations where the rule doesn't apply:
- The shares were acquired through an employee share scheme.
- The shares were inherited as part of a deceased estate.
These exceptions cut out a layer of complexity for most people. But it's vital to stay aware of the rules. If your portfolio grows and your total franking credits climb over that $5,000 threshold, you'll need to make sure you meet the holding period for all your dividend-paying shares.
Navigating the Modern Landscape of Franked Dividends
While the tax benefits of franked dividends are compelling, finding them isn't as simple as just picking any stock on the ASX. The reality is, not every company offers these tax-effective payments, and the landscape has become more concentrated than many investors first assume.
Knowing where to look is the first step in building a portfolio that generates that reliable, tax-advantaged income stream investors are chasing.
Historically, you could find fully franked dividends across a pretty broad range of industries. These days, however, they are heavily concentrated among the big, established "blue-chip" companies. We're talking about businesses that make most of their profits right here in Australia—think major banks, leading retailers, and telecommunication giants.
These are the companies paying significant Australian corporate tax, which is the very thing that fuels the franking credit system. Their stable, profitable operations give them the capacity to consistently share these tax credits with their shareholders.
Why Some Companies Offer Limited Franking
On the flip side, you'll often come across companies paying partially franked or completely unfranked dividends. This isn't necessarily a red flag or a sign of a struggling business. More often than not, it's just a reflection of where their profits are being made.
A classic example is a company with significant overseas earnings. Many of Australia’s biggest names in resources and healthcare, for instance, generate a huge chunk of their revenue abroad. Because they pay corporate tax in those foreign countries, not to the ATO, they simply don't build up a large balance of franking credits to pass on to their Australian shareholders.
Key Takeaway: The level of franking on a dividend is a direct signal of how much Australian tax a company has paid. High domestic profits typically mean high franking levels, while large international operations often lead to unfranked dividends.
Understanding this distinction is crucial. It helps you set realistic expectations and avoids the disappointment of investing in a globally successful Australian company, only to find it doesn't offer the same tax perks as a domestic-focused bank.
A Concentrated Market for Franked Dividends
The pool of companies consistently paying fully franked dividends has become increasingly focused. As you get to grips with the opportunities franked dividends present, it's smart to explore broader dividend investing strategies to ensure your approach is well-diversified.
As of December 2024, the landscape has become even more concentrated. While 111 members of the S&P/ASX 300 index pay fully franked dividends, the distribution of this income is incredibly top-heavy. By July 2025, it's projected that just ten companies will account for a massive 55% of all dividends paid by the S&P/ASX 200 index.
This isn't a random trend. It reflects broader economic shifts, with declining earnings in parts of the Australian corporate sector and company boards growing more cautious in an uncertain climate. For many, maintaining those high levels of fully franked dividends investors have come to expect is getting tougher.
This data really drives home an important lesson for investors: relying on just a handful of big names for your franked income creates a serious concentration risk in your portfolio. While these blue-chip stocks are popular for good reason, a truly robust strategy involves looking beyond the obvious choices to build a more resilient and diversified income stream.
Answering Your Top Questions About Franked Dividends
As you get more familiar with how franked dividends work, a few specific questions tend to bubble up. The concepts can feel a bit complex at first, but once you grasp the underlying logic, the answers are surprisingly straightforward. Let's tackle some of the most common queries we hear from investors.
A big one we get asked about is what happens when you choose to reinvest dividends instead of taking the cash. It’s a common worry – do you miss out on the franking credits?
Do I Get Franking Credits with a Dividend Reinvestment Plan?
Yes, you absolutely do. When you're enrolled in a Dividend Reinvestment Plan (DRP), the Australian Taxation Office (ATO) treats the transaction as if you received the cash dividend and its franking credits first.
You’re still required to declare the full, grossed-up dividend as income on your tax return, exactly the same as any other dividend. That cash portion is then simply used to buy more shares on your behalf. It’s a common point of confusion, but remember: forgoing the cash payout doesn't mean you forgo the tax credit.
Why Would a Company Pay an Unfranked Dividend?
Seeing an unfranked or partially franked dividend from a company you own usually boils down to one simple reason: the company hasn't paid enough Australian corporate tax to attach credits to the full dividend. This is very common for businesses that earn a large chunk of their profits overseas.
Because they pay taxes in other countries, they don't build up a big enough franking credit balance here in Australia to pass on. Another possibility is that the company has carried-forward tax losses, which have wiped out its local taxable income for the period.
A dividend's franking level is a direct signal of how much Australian tax the company has recently paid. Think of it as a transparent clue about where its profits are being taxed.
This is a really important distinction to understand when you're managing your expectations about how tax-effective your different investments will be.
What Is the Small Shareholder Exemption?
The ATO has a handy rule in place designed to make life a little easier for investors with smaller portfolios. If your total franking credit entitlement for the entire financial year is less than $5,000, you are generally exempt from the 45-day holding period rule.
This rule normally requires you to hold shares "at risk" for a minimum period to be eligible for the credits. The exemption means you can claim your credits without having to worry about that specific condition. It’s a practical measure that simplifies tax time for most everyday Aussie investors. Just be aware, this exemption won't apply if you've set up a special arrangement to pass the dividend benefits on to someone else.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
Getting your head around the details of franked dividends is the key to maximising your investment returns. At Australia Wide Tax Solutions, our experts help investors navigate their tax obligations with confidence, ensuring you claim every single credit you're entitled to. Contact us for personalised tax advice today.
Navigating the Australian tax landscape can seem complex, but understanding how to legally reduce your tax liability is one of the most powerful financial skills you can develop. It’s not about avoiding tax, but about structuring your finances intelligently to ensure you're not paying a dollar more than you need to. Mastering this is crucial for anyone, from small business owners and property investors to high-net-worth individuals and Australians working overseas.
- 1. Negative Gearing for Investment Properties
- 2. Capital Gains Tax (CGT) Discount Strategy
- 3. Salary Sacrifice (Concessional Contributions)
- 4. Small Business Tax Concessions and Deductions
- 5. Trust Structures and Discretionary Distributions
This guide moves beyond generic advice to provide a comprehensive roundup of ten practical and ATO-compliant tax minimisation strategies Australia offers. We will explore specific, actionable methods that apply directly to your unique financial situation. For investors, understanding various real estate investment tax benefits can be a significant game-changer, and we'll cover key aspects like negative gearing and capital gains discounts.
We will also detail powerful strategies like optimising superannuation through salary sacrificing, leveraging small business concessions, and using trust structures for effective income distribution. Each point is designed to give you clear, implementable steps to help you retain more of your hard-earned money and accelerate your financial growth. Let’s explore how you can make the tax system work for you.
1. Negative Gearing for Investment Properties
Negative gearing is a foundational tax minimisation strategy in Australia for property investors. It occurs when the deductible expenses of owning a rental property, such as mortgage interest, council rates, insurance, and maintenance, exceed the income it generates. This net rental loss can then be offset against your other assessable income, like your salary, effectively reducing your overall taxable income and the amount of tax you pay.
This strategy allows you to build a property portfolio and accumulate capital growth over the long term, while receiving an immediate tax benefit. For those considering diversifying their portfolio, understanding the implications of different property types, such as short-term leasing, is also crucial as it can affect income and expense calculations.
Implementation and Key Considerations
To successfully implement negative gearing, meticulous record-keeping is non-negotiable. Here’s what to focus on:
- Document Everything: Diligently track all expenses related to the property. This includes everything from loan interest and agent fees to minor repairs and depreciation on assets like carpets and air conditioners.
- Maximise Depreciation: Engage a quantity surveyor to prepare a depreciation schedule. This allows you to claim deductions for the wear and tear on the building and its fittings (capital works and plant and equipment), a significant non-cash deduction that boosts your claim.
- Strategic Planning: Consider the long-term view. The goal is for the property's value to appreciate, so that when you eventually sell, the capital gain outweighs the accumulated losses. Holding the asset for more than 12 months also makes you eligible for the 50% Capital Gains Tax (CGT) discount.
2. Capital Gains Tax (CGT) Discount Strategy
Timing the sale of your assets is a powerful tax minimisation strategy in Australia, primarily through the Capital Gains Tax (CGT) discount. This concession allows eligible individuals and trusts to reduce their taxable capital gain by 50% on assets held for more than 12 months. For complying superannuation funds, the discount is 33.33%. This strategy is crucial for anyone selling assets like shares, investment properties, or business interests, as it can halve the tax payable on the profit.
This simple yet effective rule rewards long-term investment. For example, a property investor who sells an asset after 15 months with a $200,000 capital gain would only add $100,000 to their assessable income, thanks to the 50% discount. It's an essential consideration for managing your investment portfolio efficiently. Additionally, understanding specific CGT rules is vital, as there are various capital gains tax exemptions in Australia that could further reduce your liability.
Implementation and Key Considerations
To effectively utilise the CGT discount, strategic planning and precise timing are essential. Here’s how to approach it:
- Monitor Holding Periods: The 12-month clock starts from the date of the contract to acquire the asset, not the settlement date. Always document and track purchase dates meticulously to ensure you meet the minimum holding period before selling.
- Offset Losses First: Before applying the discount, you must first apply any current or prior-year capital losses against your capital gains. The 50% discount is then calculated on the remaining net capital gain, which maximises the benefit of your losses.
- Strategic Asset Sales: If you hold multiple assets, plan sales strategically. Consider selling assets with shorter holding periods in years when you have capital losses to offset them, while reserving the CGT discount for your long-term successful investments.
3. Salary Sacrifice (Concessional Contributions)
Salary sacrificing into your superannuation is a highly effective strategy for reducing your taxable income while simultaneously boosting your retirement savings. This arrangement involves redirecting a portion of your pre-tax salary directly into your super fund. These contributions are taxed at a concessional rate of 15% (or 30% for very high-income earners), which is often significantly lower than your marginal tax rate, leading to immediate tax savings.
For instance, a high-income earner on a 47% marginal tax rate (including Medicare levy) can achieve a substantial tax reduction. By sacrificing funds to super, they pay only 15% tax on that amount, creating an immediate tax saving of 32%. This makes it one of the most powerful tax minimisation strategies Australia has to offer for employees looking to plan for the future.
Implementation and Key Considerations
To make salary sacrificing work for you, a proactive approach with your employer and super fund is essential. Here’s how to implement it correctly:
- Set Up a Formal Agreement: You must have a formal salary sacrifice arrangement in place with your employer before you earn the income. This cannot be applied retrospectively.
- Monitor Contribution Caps: Be mindful of the annual concessional contributions cap. Exceeding this limit can result in extra tax. It's crucial to understand the concessional contributions cap and how both your employer's compulsory contributions and your sacrificed amounts count towards it.
- Calculate Your Benefit: Determine your marginal tax rate to see if the strategy is beneficial. The higher your tax rate, the more you stand to save. Review this annually, especially if your income changes.
4. Small Business Tax Concessions and Deductions
For entrepreneurs and small business owners in Australia, leveraging specific tax concessions is a powerful tax minimisation strategy. The Australian Taxation Office (ATO) provides a suite of benefits for businesses with an aggregated turnover below certain thresholds, designed to simplify tax obligations and encourage investment back into the business. These include advantages like the instant asset write-off, simplified depreciation rules, and other deductions that can significantly lower your taxable income.
This approach allows business owners to immediately reduce their tax liability while acquiring necessary assets to fuel growth. For instance, a tradesperson can instantly write off the full cost of new tools, or a small consulting firm can immediately deduct the purchase of new computer equipment, providing an immediate cash flow benefit and making it a cornerstone of effective tax planning for small enterprises.
Implementation and Key Considerations
To make the most of small business concessions, proactive management and an understanding of eligibility criteria are essential. Here’s what to focus on:
- Confirm Eligibility: Annually check your aggregated turnover to ensure your business qualifies for the concessions you plan to claim. The thresholds can change, so staying updated is crucial.
- Maximise Asset Write-Offs: Strategically time the purchase of assets to align with the instant asset write-off rules. Plan major equipment or vehicle purchases before the end of the financial year to claim the deduction in the current period, rather than depreciating it over several years.
- Meticulous Record-Keeping: Keep detailed records of all business income, expenses, and asset purchases, including tax invoices and dates of acquisition. This documentation is vital to substantiate your claims and ensure you meet all ATO requirements for these valuable tax minimisation strategies in Australia.
5. Trust Structures and Discretionary Distributions
Utilising a trust structure, particularly a discretionary or family trust, is a sophisticated tax minimisation strategy in Australia. It allows income and capital gains generated from assets held within the trust to be distributed among various beneficiaries. The key advantage lies in the trustee's discretion to allocate income to family members on lower marginal tax rates, such as a non-working spouse or adult children at university, thereby reducing the overall tax liability for the family unit.
This strategy is particularly effective for managing investment portfolios or family businesses, providing both asset protection and tax planning flexibility. For instance, instead of a high-income earner receiving all investment income and paying tax at the top marginal rate, a family trust can distribute that same income to a beneficiary in a lower tax bracket, significantly lowering the tax paid.
Implementation and Key Considerations
Effective management of a trust for tax purposes requires careful planning and strict adherence to legal requirements.
- Professional Setup: The trust deed is the foundational document and must be drafted by a legal professional to ensure it meets your specific objectives and complies with Australian law.
- Annual Distributions: Before the end of each financial year, the trustee must decide and document how the trust's income will be distributed among the beneficiaries. This decision is crucial for locking in tax outcomes.
- Beneficiary Analysis: Regularly assess the financial circumstances and marginal tax rates of all potential beneficiaries. A distribution that is tax-effective one year might not be the next due to changes in their income.
- Compliance and Records: Maintain meticulous records of all transactions, trustee resolutions, and distributions. Be mindful of complex rules, such as Division 7A, which can apply if a trust makes loans to beneficiaries.
6. Depreciation and Division 43 Asset Deductions
Claiming depreciation is a powerful, non-cash tax minimisation strategy in Australia available to both property investors and business owners. It allows you to deduct the decline in value of an asset over its effective life. For property investors, this is primarily done through Division 43 capital works deductions (the building's structure), while businesses can claim depreciation on plant and equipment like machinery, vehicles, and office furniture.
This deduction reduces your taxable income without requiring any immediate cash outlay, making it an essential tool for managing your tax obligations. For example, a medical practice can claim depreciation on its expensive diagnostic equipment and fit-out, while a manufacturer can deduct the decline in value of its production machinery, significantly lowering its end-of-year tax bill.
Implementation and Key Considerations
To maximise your depreciation claims accurately and remain compliant, a structured approach is crucial. Here’s what to focus on:
- Engage a Quantity Surveyor: For investment properties, a specialist quantity surveyor is essential. They will prepare a comprehensive depreciation schedule that identifies all claimable assets, including capital works (Division 43) and plant and equipment (Division 40), ensuring you claim the maximum legal amount.
- Maintain a Detailed Asset Register: Businesses must keep a meticulous asset register. This should record the acquisition date, cost, and effective life of each asset, forming the basis for your annual depreciation calculations.
- Understand Capital vs. Repairs: Distinguish between repairs, which are immediately deductible, and capital improvements, which must be depreciated over time. A repair restores an asset to its original condition, while an improvement enhances it. Incorrectly classifying these can lead to ATO scrutiny.
- Plan for CGT Implications: Be aware that when you sell an asset, the depreciation you've claimed may be "recaptured" and added back to your assessable income or factored into the Capital Gains Tax (CGT) calculation. Strategic planning is vital to manage this future liability.
7. Business Loss Carry-Forward and Offsetting
For Australian businesses, particularly startups or those in a growth phase, incurring a loss is a common reality. The Business Loss Carry-Forward and Offsetting provision is a critical tax minimisation strategy that allows businesses to use these losses to reduce their tax liability in future profitable years. Instead of being a sunk cost, a business loss becomes a valuable asset that can be used to offset future profits, smoothing out tax obligations over the business cycle.
This mechanism ensures that tax is paid on the overall profitability of a business over time, rather than on a year-by-year basis in isolation. For instance, a startup with significant initial outlays might suffer a $50,000 loss in its first year but generate a $60,000 profit in its second. The carried-forward loss can reduce the second year's taxable income to just $10,000, providing vital cash flow relief when the business is still establishing itself.
Implementation and Key Considerations
To effectively utilise business losses, you must meet specific tests set by the Australian Taxation Office (ATO) and maintain diligent records.
- Maintain Accurate Records: Keep meticulous financial records that clearly prove the calculation of the loss. The ATO can query these losses years later, so documentation must be precise and easily accessible to substantiate your claims.
- Satisfy Loss Recoupment Tests: To carry forward a loss, a company must satisfy either the continuity of ownership test (maintaining more than 50% of the same ownership) or, if that fails, the same business test (continuing to operate the same type of business).
- Strategic Profit Forecasting: Plan for the future by forecasting your business’s potential profits. This helps you understand when and how you can utilise the carried-forward losses, allowing for better financial planning and management of your tax liabilities.
8. Rental Expense and Investment Deduction Optimisation
For property investors, optimising rental expense deductions is a crucial tax minimisation strategy in Australia. Beyond just negative gearing, the key lies in comprehensively identifying and claiming every legitimate expense associated with holding the investment property. These deductions directly reduce your net rental income, which in turn lowers your overall taxable income and tax liability.
This strategy involves moving beyond major costs like mortgage interest to capture a wide array of smaller, often-overlooked expenses. For instance, an investor might deduct $8,000 in annual mortgage interest, but also claim council rates ($2,000), insurance ($1,500), maintenance ($1,200), and property management fees ($1,500), substantially reducing their assessable income. To explore the full scope of what you can claim, see this detailed guide on investment property tax deductions.
Implementation and Key Considerations
Effective optimisation requires a systematic approach to tracking and categorising every cost. Here’s how to maximise your claims:
- Meticulous Record-Keeping: Keep detailed records and receipts for all property-related outgoings. This includes everything from bank statements and loan documents to invoices for repairs, gardening, and pest control.
- Segregate Finances: Use a separate bank account or credit card exclusively for property income and expenses. This simplifies tracking and ensures no deductible cost is missed during tax preparation.
- Distinguish Repairs from Improvements: Understand the difference between a repair (which is immediately deductible) and a capital improvement (which is depreciated over time). For example, fixing a broken window is a repair, while installing a new kitchen is a capital improvement. Getting this right is critical for compliance.
- Leverage Technology: Use property management software or a dedicated spreadsheet to automate expense tracking throughout the year. This avoids a last-minute scramble and ensures accuracy when lodging your tax return.
9. Superannuation Contributions by Self-Employed and Business Owners
For self-employed individuals and business owners, superannuation offers a powerful dual-purpose tool for tax minimisation and retirement planning. By making personal concessional (before-tax) contributions to your super fund, you can claim a tax deduction for the amount contributed. This directly reduces your assessable business or personal income, lowering your overall tax liability for the financial year.
This strategy effectively allows you to transfer profits from a high-tax environment (your business income) into a low-tax environment (your super fund, where earnings are typically taxed at just 15%). For example, a sole trader earning $120,000 who contributes the maximum concessional amount of $27,500 can reduce their taxable income to $92,500, resulting in a significant and immediate tax saving while simultaneously boosting their retirement nest egg.
Implementation and Key Considerations
To leverage this strategy effectively, careful planning and adherence to contribution rules are essential.
- Understand Contribution Types: Differentiate between concessional contributions (tax-deductible, capped at $27,500 per year) and non-concessional contributions (not tax-deductible, capped at $110,000 per year). Both grow in a low-tax super environment, but only concessional contributions provide an upfront tax deduction.
- Lodge a 'Notice of Intent': To claim a deduction for personal super contributions, you must submit a 'Notice of intent to claim or vary a deduction for personal super contributions' form to your super fund and receive an acknowledgement from them before you lodge your tax return.
- Monitor Contribution Caps: Be vigilant about staying within the annual contribution caps. Exceeding them can result in additional tax and penalties, undermining the benefits. Consider using the 'carry-forward' provisions if you have unused concessional cap amounts from previous years.
10. Entity Structuring (Sole Trader vs. Partnership vs. Company vs. Trust)
Choosing the right business structure is a cornerstone of effective tax minimisation strategies in Australia. Your entity choice-whether a sole trader, partnership, company, or trust-directly dictates your tax rate, liability exposure, and administrative obligations. For example, a company benefits from a fixed corporate tax rate (as low as 25%), while a sole trader pays tax at their individual marginal tax rate, which can be as high as 45% plus levies.
Strategic structuring allows you to legally reduce your tax burden by aligning your business operations with the most tax-effective entity. A discretionary or family trust, for instance, offers the flexibility to distribute profits to family members on lower tax brackets, while a company structure can be used to cap the tax rate on retained profits and provide robust asset protection.
Implementation and Key Considerations
Selecting and implementing the optimal business structure requires careful analysis of your specific circumstances. Here's how to approach it:
- Analyse Profitability: Assess your current and projected income. A high-earning professional might incorporate their practice to move from a top personal tax rate to the lower company tax rate, while a new startup may begin as a sole trader for simplicity and switch later.
- Evaluate Asset Protection: Consider your business risks and liability. Companies and trusts offer a layer of separation between business and personal assets, which is a significant advantage over a sole trader structure where personal assets are at risk.
- Plan for the Future: Think about your long-term goals, such as succession planning or bringing on investors. Trusts are often favoured for family businesses to facilitate inter-generational wealth transfer, while companies are better suited for raising capital.
- Seek Professional Advice: The setup costs and tax implications of restructuring are significant. Always engage a qualified tax advisor to model the outcomes of different structures and ensure compliance with complex regulations.
10-Point Comparison of Australian Tax Minimisation Strategies
| Strategy | 🔄 Implementation Complexity | ⚡ Resource Requirements | 📊 Expected Outcomes | 💡 Ideal Use Cases | ⭐ Key Advantages |
|---|---|---|---|---|---|
| Negative Gearing for Investment Properties | Moderate — ongoing tax reporting and cash‑flow management | High — significant capital/leverage and ability to cover shortfalls | Short‑term tax deductions; potential long‑term capital growth; possible cash‑flow deficit | High‑income investors seeking capital growth and tax offsets | Immediate tax deductions; leverages capital growth |
| Capital Gains Tax (CGT) Discount Strategy | Low — mainly timing and record‑keeping to meet holding periods | Low — minimal resources beyond documentation and planning | Reduces CGT (50% for individuals) on qualifying disposals | Long‑term holders of property, shares, or business assets planning sales | Substantial CGT savings; encourages long‑term investing |
| Salary Sacrifice (Concessional Contributions) | Low — requires employer agreement and cap monitoring | Medium — payroll setup and available pre‑tax income | Lowers taxable income; tax‑effective superannuation growth; funds preserved until retirement | High‑income employees seeking immediate tax savings and retirement build | Immediate tax reduction; disciplined retirement saving |
| Small Business Tax Concessions and Deductions | Moderate — eligibility checks and compliance with thresholds | Medium — bookkeeping, adviser input, and asset purchases | Accelerated deductions and improved cash flow; reduced current tax | Small businesses under turnover thresholds buying equipment or scaling up | Immediate asset write‑offs; simplified depreciation rules |
| Trust Structures and Discretionary Distributions | High — legal setup, trustee duties and complex compliance | High — legal/accounting fees and ongoing administration | Flexible tax outcomes via income‑splitting; asset protection; complex reporting | Families/businesses needing income splitting, asset protection, succession planning | Significant tax flexibility and asset protection |
| Depreciation and Division 7A Asset Deductions | Moderate — requires formal depreciation schedule and reviews | Low–Medium — professional schedule (quantity surveyor) often recommended | Non‑cash deductions that improve tax position, especially early ownership | Property investors and businesses with depreciable buildings, plant or equipment | Substantial non‑cash deductions; improves cash flow without cash outlay |
| Business Loss Carry‑Forward and Offsetting | Moderate — accurate loss tracking and ownership rule compliance | Low — accounting and forecasting; occasional tax advice | Offsets future profits; smooths tax over boom/bust cycles | Startups, growth businesses or firms recovering from downturns | Preserves value of losses; supports recovery and future tax relief |
| Rental Expense and Investment Deduction Optimization | Moderate — detailed substantiation and classification required | Low–Medium — time to track expenses; property management tools helpful | Reduces taxable rental income through broad allowable deductions | Active property investors aiming to maximize legitimate deductions | Extensive deductible items; straightforward to implement with records |
| Superannuation Contributions by Self‑Employed & Business Owners | Moderate — planning, declarations and cap management required | Medium — available cash for contributions and administration | Immediate tax deductions for concessional contributions; retirement accumulation | Self‑employed/business owners with surplus income to allocate to super | Large tax deductions; higher contribution flexibility than employees |
| Entity Structuring (Sole Trader / Partnership / Company / Trust) | High — strategic modelling, legal setup and ongoing compliance | High — professional advice, setup costs and ongoing administration | Varies by structure: potential lower tax rates, liability protection, succession benefits | Growing businesses, high‑income professionals and asset‑heavy enterprises | Ability to optimise tax, protect assets and plan succession |
Putting Your Tax Strategy into Action for a Stronger Financial Future
Navigating the landscape of tax minimisation strategies in Australia can feel complex, but as we've explored, the opportunities to legally reduce your tax liability and build wealth are significant. This is not about finding loopholes; it is about strategically and proactively managing your financial affairs within the framework established by the Australian Taxation Office (ATO). By understanding and implementing the right combination of these strategies, you shift from a reactive, year-end scramble to a forward-thinking, year-round approach to financial optimisation.
The key takeaway is that effective tax planning is deeply personal. A property investor's most powerful tool might be negative gearing and depreciation schedules, while a small business owner will find immense value in instant asset write-offs, concessional super contributions, and choosing the correct business structure. Similarly, a high-income employee can significantly benefit from salary sacrificing into superannuation, and an investor can use the CGT discount to their advantage.
Key Pillars of a Successful Tax Strategy
To transform this knowledge into tangible results, focus on these core principles:
- Proactive Planning, Not Reactive Filing: The most effective tax strategies are planned months, or even years, in advance. Decisions made today about asset purchases, investment timing, and superannuation contributions will directly impact your tax outcome at the end of the financial year.
- Impeccable Record-Keeping: Every deduction and claim, from a small business expense to a rental property repair, must be substantiated. Diligent record-keeping is the non-negotiable foundation of any robust tax minimisation plan. Without it, even the most brilliant strategy is indefensible under ATO scrutiny.
- Alignment with Financial Goals: Your tax strategy should never exist in a vacuum. It must be an integrated component of your broader financial objectives, whether that's saving for retirement, expanding your business, or growing an investment portfolio. The goal is to reduce tax in a way that accelerates your journey toward these larger goals.
- Seeking Professional Guidance: The Australian tax system is dynamic, with legislation, thresholds, and regulations subject to change. Partnering with a qualified tax professional ensures your strategies are not only compliant and current but also tailored precisely to your unique financial situation and risk tolerance.
Ultimately, mastering these tax minimisation strategies for Australia empowers you to retain more of your hard-earned money, redirecting it from tax payments towards investments, debt reduction, or business growth. It's a fundamental shift in mindset that positions you in control of your financial destiny, ensuring your efforts are maximally rewarded.
Yes, if you are under 75 and meet the work test (if aged 67–74). Lodge a notice of intent to claim with your fund before the earlier of the tax return due date or the lodgement date. Once the fund acknowledges the notice, the contribution becomes concessional and is taxed at 15% inside the fund.
The concessional contributions cap for 2025-26 is $30,000. This covers employer SG contributions, salary sacrifice, and personal deductible contributions combined. Contributions above the cap are included in assessable income at your marginal rate, with a 15% tax offset for the tax already paid inside the fund.
The Super Guarantee rate for 2025-26 is 11.5%, rising to 12% from 1 July 2025. Employers must contribute this percentage of each eligible employee's ordinary time earnings to a complying super fund at least quarterly. Late or missing payments trigger the Super Guarantee Charge, which includes interest and is not tax deductible.
Salary sacrifice contributions come from pre-tax income and are taxed at 15% inside super rather than at your marginal rate (up to 47%). The difference is your tax saving. A taxpayer in the 37% bracket saves 22 cents per dollar sacrificed, subject to the $30,000 concessional cap.
Yes, if your total super balance was below $500,000 on 30 June of the prior year. Unused cap amounts from the previous five years can be carried forward and used in a higher-income year. The oldest unused amounts are applied first, allowing catch-up contributions that significantly reduce tax for eligible individuals.
Ready to move from theory to practice? The team at Australia Wide Tax Solutions specialises in crafting personalised tax plans for individuals, investors, and businesses across the country. Let us help you identify and implement the most effective strategies for your circumstances, ensuring full compliance and maximising your financial potential. Visit Australia Wide Tax Solutions to learn how our expert guidance can secure you a stronger financial future.
Here’s the headline: Australia’s dividend tax hinges on where you live and whether your payout is franked or unfranked. If you’re a resident, you’ll apply your marginal rate—up to 47%—but you’ll also use franking credits to offset that tax. Non-residents face a flat 30% withholding tax on all dividends.Quick Snapshot Of Dividend Tax Rates
Summary Of Dividend Tax Rates
| Investor Type | Dividend Type | Tax Rate | Withholding Tax Rate |
|---|---|---|---|
| Resident | Franked | Marginal rate | 0% |
| Resident | Unfranked | Marginal rate | 0% |
| Non-resident | Franked | N/A | 30% |
| Non-resident | Unfranked | N/A | 30% |
- Residents unlock a franking credit to cancel out company tax already paid.
- Unfranked dividends are simply taxed at your personal marginal rate.
- All dividends to non-residents incur a 30% withholding tax.
- Even franked payments to non-residents get taxed on their unfranked portion.
Key takeaway: Franking credits act like a voucher for company tax paid, preventing you from being taxed twice.Before we dive into worked examples, keep these figures front of mind as your quick reference.
Key Rate Highlights
To bring these numbers to life, consider a mid-income Australian resident on a 30% marginal rate. If they receive a $70 fully franked dividend (with a gross-up to $100), their franking credit wipes out any extra tax—leaving them square.- A fully franked dividend carries a 30% credit for company tax already paid.
- Unfranked dividends are added to your assessable income and taxed at your full marginal rate.
- Non-resident investors see 30% withheld before you even touch the cash.
- Double tax agreements can slice that withholding—depending on your home country.
Treaty example: A UK resident might only pay 15% under the Australia–UK Double Tax Agreement.Cross-checking your dividend statement with these highlights makes sure you never miss franking credits or spot under-withholding.
Next Steps
Now that you’ve got the big picture, grab your latest dividend statement and match it line-by-line. If anything feels murky, chat with an AWTS adviser for clear, expert guidance. This overview paves the way for the detailed sections ahead—where we’ll break down gross-up calculations, credit claims and non-resident treaty nuances. Bookmark this guide for your next tax return lodgement.Understanding Dividend Tax Concepts
Dividends are a way companies share profits with investors. It’s your return for owning a slice of the business. When you hold shares, you’ll often see a cash payment labelled a dividend. Sometimes these payments come with a tax offset, depending on how much company tax has already been paid. Imagine handing out sweets from a packet. Each share is like a ticket in the draw. The more tickets you hold, the more sweets you collect. Without a franking credit, it can feel like paying twice for the same treat.- Franked Dividends include a credit for company tax already paid.
- Unfranked Dividends have no tax offsets attached.
- Franking Credits can reduce or even eliminate extra tax bills.
Key Dividend Definition
A franked dividend brings with it a franking credit, matching the tax the company has already paid on that profit. This mechanism stops you from being taxed twice. By contrast, an unfranked dividend carries no credit. You pay tax on the full amount at your personal marginal rate.Franking credits act like coupons for tax already paid, offsetting what you owe at tax time.
How Imputation Works
Australia’s dividend imputation system hands company tax paid straight to shareholders as credits. Picture a company earning $100 in profit, paying $30 in tax, then distributing $70 cash plus a $30 credit. Key steps include:- Company earns profit and pays tax at 30%
- Company issues a dividend with an attached franking credit
- Shareholder reports the grossed-up dividend as income and claims the credit
Why System Matters
By preventing double taxation, the imputation system keeps more money in investors’ pockets. Without it, profits would be taxed at the corporate level and again on your personal return. It also makes Australian shares more appealing by aligning company and shareholder tax outcomes.| Feature | Before | After |
|---|---|---|
| Taxation | Double taxed | Single tax with credit |
- Lower overall tax on dividends
- Simpler reporting at lodgement time
- Better alignment between company profits and investor returns
Case Study
Anna holds 100 shares in XYZ Ltd. She receives an $80 fully franked dividend with a $34.29 credit. At her marginal rate of 34.5%, she owes no extra tax and even sees a small refund.Historical Shift Explained
On 1 July 1987, Australia reformed its dividend tax rules to stamp out double taxation. Before this change, shareholders paid personal income tax on dividends with no credit for company tax already paid. Learn more about the 1987 imputation reform on EndureGo.Key takeaway: Franking credits ensure you aren’t taxed twice on the same profit, supporting fairer and more efficient capital markets.Understanding these fundamentals sets you up to tackle resident versus non-resident dividend rules. Next, we’ll unpack how different tax rates apply depending on where you live.
Resident And Nonresident Dividend Tax Rates
Your residency status can make a huge difference to how dividends are taxed in Australia. If you’re an Australian resident, every dollar of dividend income slides into your marginal tax bracket. Non-residents, by contrast, face a fixed withholding rate on dividends. Each tax year, the ATO applies tests—domicile, physical presence and intention—to determine where you stand. It pays to review your situation annually so you’re not caught off-guard at lodgement time.Resident Rates For Dividends
For Aussie residents, franked dividends come with an attached franking credit representing the 30% company tax already paid. Think of it as a prepaid tax voucher. When you lodge your return, you offset that credit against your personal tax bill. Unfranked dividends, however, land straight into your taxable income and get hit at your marginal rate. If you sit in the 34.5% bracket, there’s no franking credit to soften the blow. Key Points:- Franked Dividends carry a credit equal to the 30% company tax.
- Unfranked Dividends have no credit and attract full personal tax.
- You claim franking credits on lodgement to reduce tax payable.
- If your marginal rate is below 30%, excess credits become a refund.
Nonresident Withholding Rules
Non-residents pay a flat 30% withholding tax on most dividends. But thanks to Australia’s network of double tax agreements, that rate can drop significantly.Under many double tax agreements, withholding rates can drop from 30% to between 0–15% depending on country.A simple example: a UK resident typically sees withholding fall to 15% under the Australia–UK treaty. You simply supply your foreign tax ID and the ATO applies the reduced rate at source.
Side By Side Rate Comparison
Let’s walk through a $100 dividend to see who keeps what:| Profile | Dividend Type | Gross Amount | Tax Outcome |
|---|---|---|---|
| Resident | Fully Franked | $100 | $0 net tax after credits |
| Resident | Unfranked | $100 | $34.50 at 34.5% rate |
| Non-Resident | Any Dividend | $100 | $30 withheld (30%) |
| UK Resident* | Any Dividend | $100 | $15 withheld (15% treaty) |
Tips To Optimise Your Position
Smart planning can trim your tax on dividends:- Confirm your residency each year against ATO guidelines.
- Keep dividend statements and franking credit certificates organised.
- Apply the correct withholding rate under relevant double tax agreements.
- Seek professional advice to ensure compliance and spot savings.
Residency Test Example
Meet Maria, who arrived in Brisbane from Singapore on July 1 and leased a flat for six months. She intended to stay long-term, so the ATO treated her as an Australian resident.- Her dividend portfolio was registered to her Aussie address.
- She provided an Australian bank account for all payouts.
- On her tax return, franking credits wiped out company tax entirely.
How Franking Credits Work
When an Australian company pays you a franked dividend, it’s like receiving a prepaid tax voucher. Because the company has already met its 30% tax obligation on profits, you pick up that tax as a franking credit attached to your dividend. Think of each credit as a $1 store voucher you can use to offset your own tax bill.- The company pays tax at 30% on its profits.
- The dividend is then grossed up by the amount of tax already paid.
- A matching franking credit attaches to your dividend payment.
- https://youtube.com/shorts/EJmk8hRFMy4?feature=share
Gross Up And Offset Example
Let’s break it down with numbers. You receive a $70 franked dividend, but it’s grossed up to $100 because of the attached $30 credit. On your tax return, you declare the full $100 as assessable income. Then you claim back the $30 franking credit to reduce your tax liability. Dividend imputation has made Australia a go-to market for yield hunters. By offsetting personal tax with franking credits valued at the 30% corporate rate, investors across brackets enjoy healthier after-tax payouts. A $70 franked dividend grossed to $100 with a $30 credit not only cushions your tax but fuels stronger dividend policies. Discover more about high-dividend strategies in Australia through this S&P Global research.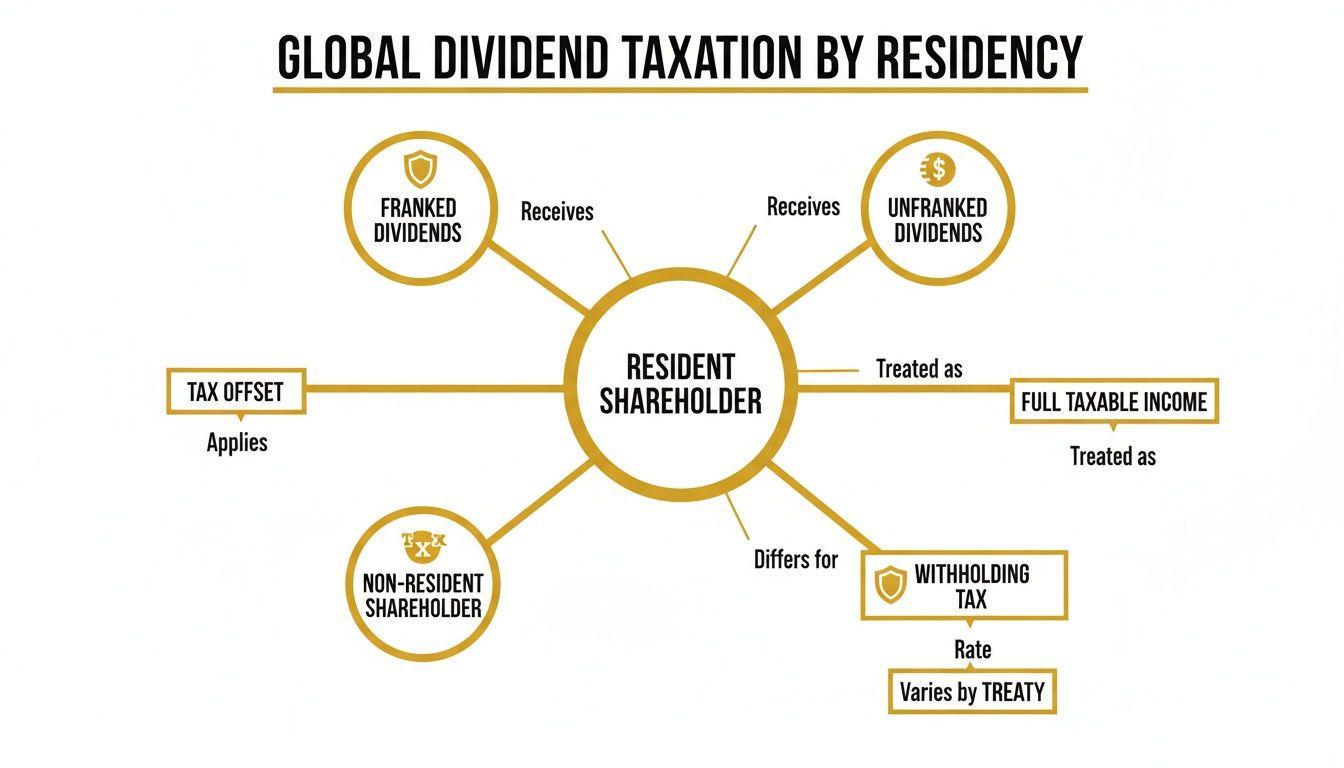
Tax Impact Across Brackets
How much you benefit depends on your marginal rate:| Marginal Rate | Dividend Grossed | Franking Credit | Tax Owing or Refund |
|---|---|---|---|
| 25% | $100 | $30 | $5 refund |
| 30% | $100 | $30 | $0 net tax |
| 45% | $100 | $30 | $15 owing |
“Franking credits are like prepaid tax vouchers that ensure you never pay tax twice.”Learn more about franking credits in our article on How Franking Credits Work
Common Misconceptions And Tips
- Misconception: Lower-rate taxpayers can’t get refunds. In fact, rates under 30% receive cash back.
- Misconception: Non-residents enjoy franking credits. They don’t—non-residents face withholding on unfranked portions.
- Tip: Check your dividend statement for the exact franking percentage.
- Tip: Lodge your return early to claim any refunds sooner.
How To Claim Your Credits
- Gather your dividend statements and note the franking details.
- Report the grossed-up dividend amount under your assessable income (Label 6).
- Enter the franking credits in the credits section of your tax return.
- Lodge online or via a tax agent before the deadline.
Practical Example For Investors
Sarah, a retiree on a 19% marginal rate, collects two fully franked dividends totalling $140. The grossed-up amount is $200 ($140 cash + $60 credit). Her tax on $200 at 19% is $38, but she holds $60 in credits—so she receives a $22 refund. Sarah also has unfranked dividends that flow straight into her assessable income. By blending franked and unfranked streams, she designs a diversified income plan with clear tax outcomes.Key Takeaway
Franking credits transform company tax into your own prepaid tax vouchers. Use the gross-up and credit steps to cut your liability or secure refunds—and boost the net return on your dividend income. Start planning today.Calculation Examples For Dividend Tax
Turning ideas into action is the best way to truly get dividend tax. Below, you’ll find three clear examples: a fully franked dividend for a middle-income resident, an unfranked payout for a high-income earner, and a non-resident withholding tax scenario. Each walk-through shows how to gross up dividends, apply the right rate, and land on your final tax number.Standard Steps For Dividend Tax Calculation
Before you dive into the maths, break the process into bite-sized tasks:- Decide if your dividend is franked or unfranked.
- Confirm your residency status for tax.
- Gross up franked dividends by adding the imputation credit to your assessable income.
- Apply your marginal rate (residents) or withholding rate (non-residents).
- Subtract the franking credit or withheld tax.
- Note your net cash result and any refund or payable amount.
Middle-Income Resident With Fully Franked Dividend
Imagine you’re on a 30% tax rate and you get a $70 fully franked dividend. You add the $30 imputation credit to report $100 of assessable income.- Grossed-up income: $100
- Attached franking credit: $30
- Tax on $100 at 30%: $30
- Credit offsets tax: $30
- Final tax payable: $0
“Franking credits prevent double taxation—and if your rate sits below the company rate, you might even get a refund.”Case Study: Emma picks up four fully franked dividends of $75 each from BlueCo. She ends up with no quarterly tax bill and even spots a small refund at year end, thanks to her 28% effective rate.
High-Earner Resident With Unfranked Dividend
Now picture a top-bracket earner on a 45% rate taking home a $1,000 unfranked dividend. With no franking credit to cushion the blow, the entire amount faces tax.- Dividend: $1,000
- Marginal rate: 45%
- Tax due: $450
| Component | Amount |
|---|---|
| Dividend received | $1,000 |
| Tax at 45% | $450 |
| Net cash after tax | $550 |
Non-Resident Withholding Tax Computation
Non-residents face a flat 30% withholding on dividends. If you’re paid $500, the ATO automatically takes $150, and you pocket $350.- Gross dividend: $500
- Withholding rate: 30%
- Tax withheld: $150
- Net payment: $350
Key takeaway: Always budget for withholding at source and explore any treaty benefits you can claim.If your home country has a 15% treaty rate—say, the UK—you can apply for the lower rate. On a $500 dividend, that saves you $75, leaving $425 in your account. Case Study: Li, studying in Australia, receives a $2,000 dividend and uses her UK tax ID to claim the 15% rate. She saves $300 compared to the standard 30% withholding.
Calculation Template For Your Portfolio
Here’s a template you can copy into your own spreadsheet:| Field | Value |
|---|---|
| Dividend amount | $ |
| Franking percentage | % |
| Gross-up calculation | $ |
| Franking credit | $ |
| Applicable tax rate | % |
| Tax on grossed income | $ |
| Tax withheld (non-resident) | $ |
| Final tax payable or refund | $ |
| Net dividend after tax | $ |
- Fill in your dividend amount and franking percentage.
- Calculate the grossed-up figure and credit.
- Apply your marginal or withholding rate.
- Deduct credits or withheld tax.
- Review your net cash and any refund.
Pro tip: Save a blank version of this table so you can plug in new dividend statements without reformatting.
Advanced Tips And Common Pitfalls
Attention to detail pays off. A small slip in your franking percentage or residency label can throw off the result.- Double-check your residency status if you move mid-year.
- Request a franking credit statement from the payer if it isn’t provided.
Reflection On Tax Opportunities
Looking across these examples reveals clear strategies:- Middle-income taxpayers often pay zero on fully franked dividends.
- High earners can boost after-tax returns by favouring franked shares.
- Non-residents should always verify treaty rates to cut withholding.
Lodgement And Compliance For Dividend Tax
Key Lodgement Steps
The first step is simple: collect all your dividend statements from share registries and franking credit certificates. Treat this as gathering the pieces of a puzzle. Next, log in to myTax or hand over your paperwork to a registered tax agent. Your goal here is to slot each figure into the right label in your tax return.- Step 1 Gather dividend statements and franking certificates to confirm exact amounts.
- Step 2 Report grossed-up dividends under Label 6 as part of your assessable income.
- Step 3 Enter total franking credits in the credits section to reduce your tax bill.
- Step 4 Double-check every figure to catch common data-entry errors.
Expert Insight: “Precise dividend reporting stops unexpected ATO queries in their tracks,” notes a senior AWTS tax adviser.Deadlines are non-negotiable. The standard lodgement date is 31 October, but if you’ve engaged an agent by then, you may qualify for an extended due date.
| Common Error | Fix |
|---|---|
| Missing franking credit | Cross-check your registry statement |
| Incorrect gross-up amount | Use the ATO’s official formula |
| Omitted dividend entry | Reconcile against all registry data |
Correcting Past Lodgement Errors
Under-claiming franking credits is like leaving money on the table. Don’t do it. Amendments delayed beyond two years can attract interest or penalties, so tackle them as soon as they surface.- Keep dividend statements and franking certificates organised for at least five years.
- Match dividend payments against your bank records.
- Archive copies of any correspondence with the ATO.
- For complex corrections, consider professional help from AWTS.
Record Keeping Best Practices
Think of your digital filing system as your safety net during audits and corrections. Create clear folders labelled by year and type, then drop all relevant documents inside.- Save dividend statements, franking certificates and broker confirmations together.
- Log arrival dates of statements and payments for quick cross-checks.
- Back up your files regularly and protect them with passwords.
- Retain records for a minimum of five years, per ATO rules.
Case Study: When John merged his spreadsheets with his broker’s data, he uncovered a missing $500 credit—right before lodgement.Solid record keeping isn’t just about avoiding chaos; it gives you confidence in every number. Start your lodgement process well ahead of deadlines, and you’ll reduce stress come tax time.
Frequently Asked Questions
First off, many investors ask: how exactly do residents claim franking credits on dividends? It all comes down to the gross-up and offset rules when you file your return. For instance, if you receive a $70 franked dividend, you’ll gross it up to $100 and show a $30 franking credit. You report the full $100 as income, then use that $30 credit to shave down your tax bill. Next, what withholding rates apply to non-residents? In most cases, a flat 30% is withheld from dividend payments at source.Common Scenarios
- Non-resident franked dividends face 30% withholding on their unfranked portion.
- Under double tax treaties, you might see that rate cut to 0–15%.
Clarity around dividend statements prevents costly mistakes and ensures you capture every franking credit.So, how do you stay on top of it all? Keep accurate dividend statements, make sure to lodge before the deadlines and consider a professional review for peace of mind. These FAQs should clear up the confusion around Australia’s tax on dividends and give you the confidence to lodge correctly.
- Download your dividend statement.
- Schedule a chat with an AWTS adviser for any questions.
Get clarity on your dividend tax with Australia Wide Tax Solutions
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
The Complete Guide to Australia's Dividend Imputation System
Understanding how franking credits can boost your investment returns and reduce your tax burden
- The Complete Guide to Australia's Dividend Imputation System
- What Are Franking Credits?
- Why Do We Need Franking Credits?
- Why Is Tracking Franking Credits Crucial?
- Who Needs to Deal with Franking Credits?
What Are Franking Credits?
Franking credits, also known as imputation credits, are one of Australia's most valuable yet misunderstood tax benefits. They represent a credit for the company tax already paid by Australian companies on their profits before distributing dividends to shareholders. This system, unique to Australia and a few other countries, prevents the double taxation of company profits and can significantly enhance your investment returns.
At Australia Wide Tax Solutions (AWTS), we help thousands of clients maximise their franking credit benefits each year. With over 26 years of experience in tax compliance and our specialised knowledge across various investment structures, we've seen how proper franking credit management can transform a client's tax position and investment strategy.
Why Do We Need Franking Credits?
Preventing Double Taxation
The primary purpose of franking credits is to eliminate double taxation. Without this system, company profits would be taxed twice:
- First, when the company pays company tax on its profits (currently 25% for small companies, 30% for larger companies)
- Second, when shareholders pay personal income tax on dividends received
Encouraging Investment in Australian Companies
Franking credits make Australian shares more attractive to Australian investors, particularly those in lower tax brackets or retirees. This system encourages domestic investment and facilitates Australian companies' access to capital more easily.
Supporting Retirees and Low-Income Earners
For retirees and low-income earners, franking credits can result in cash refunds from the ATO. This feature makes Australian dividend-paying shares particularly attractive for retirement planning and income generation strategies.
Creating Tax Efficiency
Franking credits can reduce your overall tax liability or even result in refunds, making them a powerful tool for tax-efficient investing and retirement planning.
Why Is Tracking Franking Credits Crucial?
Maximising Tax Benefits
Proper tracking ensures you claim all available franking credits. Missing even small amounts can add up to significant losses over time, especially for investors with substantial share portfolios.
Accurate Tax Return Preparation
The ATO requires precise reporting of franking credits. Inaccurate reporting can trigger audits, penalties, or missed refund opportunities. Your dividend statements show both the cash dividend and the franking credit amount – both must be included in your tax return.
Investment Decision Making
Understanding your franking credit position helps inform investment decisions. For some investors, the after-tax return including franking credits makes Australian shares more attractive than international investments or other asset classes.
Cash Flow Planning
For retirees and low-income earners, franking credit refunds can account for a substantial portion of their annual income. Accurate tracking enables more effective financial planning and improved cash flow management.
Who Needs to Deal with Franking Credits?
Individual Shareholders
Any individual who owns shares in Australian companies that pay franked dividends must report these in their tax return. This includes:
- Direct shareholdings
- Managed fund distributions that include franking credits
- Exchange-traded fund (ETF) distributions
- Shares held in family trusts
Self-Managed Super Fund (SMSF) Trustees
SMSFs that hold Australian shares are required to track and report franking credits. In the pension phase, SMSFs can often claim full refunds of franking credits, making them particularly valuable.
Companies and Trusts
Corporate entities and trusts that receive franked dividends must track these credits and may be able to pass them on to beneficiaries or use them to offset their own tax liabilities.
Retirees and Low-Income Earners
These groups often benefit most from franking credits, as they may receive cash refunds when their marginal tax rate is lower than the company tax rate used to frank the dividends.
Understanding the Franking Credit System
How Franking Credits Work
When an Australian company pays tax on its profits and then distributes those profits as dividends, it can "frank" those dividends by attaching franking credits. The franking credit represents the tax that has already been paid by the company.
Example:
- The company earns $100 profit
- Pays $30 company tax (30% rate)
- Has $70 available for dividends
- Pays $70 dividend with $30 franking credit attached
- Shareholder reports $100 total income ($70 cash + $30 franking credit)
- Shareholder gets $30 credit against their personal tax liability
Fully Franked vs. Partially Franked Dividends
- Fully franked: The entire dividend has franking credits attached
- Partially franked: Only part of the dividend has franking credits attached
- Unfranked: No franking credits attached (often from companies that haven't paid Australian tax)
Franking Credits and Company Tax Returns: Timing and Lodgement
When Are Franking Credits Dealt With?
Franking credits are not "lodged" separately – they're reported as part of your annual tax return. However, the timing depends on your entity type:
Individual Tax Returns: Franking credits are reported when you lodge your annual tax return, typically between July 1 and October 31 each year.
Company Tax Returns: Companies that pay franked dividends must maintain a franking account and report franking credit transactions in their company tax return. This is lodged by the company tax return due date (typically 15 months after the end of the year for companies with tax agents).
SMSF Returns: SMSFs report franking credits in their annual return, due by the SMSF lodgement deadline.
Payment and Refund Timing
Franking credits don't involve separate payments – they're credits that reduce your tax liability or create refunds. The timing aligns with your tax return processing:
- Tax Refunds: If franking credits create a refund, the ATO typically processes these within 12 business days for electronic returns
- Tax Liabilities: If you owe tax after franking credits are applied, payment is due by the tax return due date
Consequences of Late or Incorrect Reporting
Missed Refund Opportunities
Late lodgement means delayed refunds. For retirees relying on franking credit refunds for income, this can have a significant impact on cash flow and financial planning.
Penalties and Interest
While franking credits themselves don't attract penalties, late lodgement of tax returns containing franking credits can result in:
- Failure to lodge penalties
- General interest charges on any outstanding tax liabilities
- Lost opportunity cost on delayed refunds
ATO Scrutiny
Incorrect franking credit reporting can trigger an ATO review or audit. The ATO has sophisticated data matching systems that compare your reported franking credits against company records.
Compounding Errors
Errors in franking credit reporting can compound over multiple years, making corrections more complex and potentially costly.
When Are Franking Credit Benefits Realised?
Annual Tax Return Processing
Franking credits are typically claimed and refunded annually through the tax return process. However, the benefits can be realised at different times:
Immediate Benefits: Some investors adjust their PAYG withholding or instalments based on expected franking credits, providing more immediate cash flow benefits.
Quarterly Benefits: SMSFs in pension phase can sometimes access franking credit refunds quarterly through the BAS system.
Annual Benefits: Most individual taxpayers realise franking credit benefits annually when their tax return is processed.
Who Benefits Most from Franking Credits?
Retirees and Low-Income Earners
These groups often have marginal tax rates below the company tax rate, allowing them to receive cash refunds of excess franking credits. This makes Australian dividend-paying shares particularly attractive for retirement income strategies.
SMSF Members in Pension Phase
SMSFs paying pensions typically pay no tax, allowing them to claim full refunds of franking credits. This can significantly boost retirement income.
Tax-Efficient Investors
Investors who understand how to structure their affairs to maximise franking credit benefits can achieve superior after-tax returns compared to those who ignore these opportunities.
Long-Term Wealth Builders
The compounding effect of franking credit refunds reinvested over time can significantly enhance long-term wealth accumulation.
Common Franking Credit Mistakes to Avoid
Failing to Report Franking Credits
Some taxpayers only report the cash dividend and forget to include the franking credit. This is incorrect – both amounts must be reported as assessable income.
Incorrect Franking Credit Amounts
Using incorrect franking credit amounts, resulting from misreading dividend statements or outdated information, can lead to over- or under-claiming credits.
Missing Managed Fund Franking Credits
Managed funds and ETFs often distribute franking credits, but these can be easy to overlook if you don't carefully review your annual tax statements.
Poor Record Keeping
Inadequate records of dividend statements and franking credit entitlements can lead to missed opportunities or compliance issues.
How AWTS Maximises Your Franking Credit Benefits
Expert Knowledge Across Investment Structures
Our team understands franking credits across all investment structures – individual holdings, family trusts, companies, and SMSFs. We ensure you're maximising benefits regardless of how you hold your investments.
Comprehensive Review Process
We don't just enter the numbers from your dividend statements. Our 15-year-old audit system cross-checks franking credit calculations against multiple sources to ensure accuracy and completeness.
Strategic Tax Planning
We help you understand how franking credits fit into your overall tax strategy, including:
- Optimal investment structures for your circumstances
- Timing strategies for dividend-paying investments
- Integration with other tax planning opportunities
Industry-Specific Expertise
Whether you're a medical professional with significant investments, a tradesperson building wealth through shares, or involved in e-commerce with complex investment structures, we understand how franking credits apply to your specific situation.
Advanced Franking Credit Strategies
Dividend Stripping Rules
The ATO has rules to prevent artificial schemes to claim franking credits. We ensure your investment strategies comply with these rules while maximising legitimate benefits.
45-Day Rule
To claim franking credits on shares, you generally must hold them for at least 45 days (90 days for preference shares). We help ensure your trading strategies don't inadvertently breach these rules.
Franking Credit Trading
Some sophisticated investors consider franking credit in their buy-sell decisions. We can help you understand when this makes sense and when it doesn't.
Red Flags: When Your Current Accountant Isn't Maximising Your Franking Credits
Warning Signs You're Missing Out
If you're experiencing any of these issues, you may not be getting the full benefit of your franking credits:
Generic Investment Advice: If your accountant doesn't discuss how franking credits impact your investment strategy, you're missing out on opportunities.
Delayed Processing: If your tax returns are consistently lodged late, you may be delaying franking credit refunds and potentially missing out on planning opportunities.
No Discussion of Investment Structures: If your accountant hasn't discussed whether your current investment structure optimises franking credit benefits, you may be paying more tax than necessary.
Errors in Previous Returns: If you've had franking credit errors in previous returns, it suggests your accountant may not have the expertise to handle investment taxation properly.
No Proactive Communication: If your accountant only contacts you at tax time and doesn't provide ongoing advice about investment taxation, you're not getting full value.
Take Action: Don't Let Franking Credit Opportunities Slip Away
Why Professional Expertise Matters
Franking credits represent real money – often thousands of dollars annually for investors with substantial Australian share portfolios. Getting this wrong doesn't just cost you current refunds; it can impact your long-term wealth-building strategy.
The AWTS Advantage
Specialised Investment Knowledge: Our team includes specialists in investment taxation who understand the nuances of franking credits across different investment structures.
Comprehensive Service: We don't just prepare your tax return – we provide strategic advice on how to structure your investments to maximise after-tax returns.
Technology Integration: Our systems automatically cross-check franking credit calculations and flag potential issues before they become problems.
Proactive Planning: We provide ongoing advice throughout the year, not just at tax time, helping you make informed investment decisions.
Ready to Maximise Your Franking Credit Benefits?
Don't let another tax year pass without ensuring you're getting the full benefit of your franking credits. Whether you're a retiree looking to maximise income, an investor building long-term wealth, or a business owner with complex investment structures, AWTS has the expertise to help.
Contact Australia Wide Tax Solutions today: Phone: 0488 854 200 Website: awts.net.au
Office: 58/20-40 Meagher St, Chippendale NSW 2008
Our Sydney office is open Monday to Saturday, 2 PM to 11:45 PM, with online consultations available for your convenience.
Remember, with our comprehensive approach to investment taxation and 26+ years of experience, you're not just getting tax compliance – you're getting strategic advice that can enhance your long-term financial position.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.