
Thinking any old accountant can handle your rental property finances? That's a mistake that could be costing you thousands.
- Why a Specialist Property Accountant Is Your Best Investment
- Key Services Your Property Accountant Must Provide
- How To Find And Vet The Best Local Property Accountants
- What To Expect In Your First Meeting and How Much It Costs
- Costly Property Tax Mistakes And How To Avoid Them
Getting the right advice from a specialist investment property accountant near you isn't an expense—it's one of the smartest financial moves you can make. It’s what separates a good investment from a truly great one, maximising your returns while keeping you on the right side of the ATO.
Why a Specialist Property Accountant Is Your Best Investment

It’s a common trap. Many investors assume their regular accountant can manage their property portfolio. Sure, a generalist can lodge a tax return, but they often don’t have the deep, niche knowledge of Australian property tax law. This is where a specialist doesn't just do the work—they create value.
Picture two investors with identical properties. One uses a general accountant who just fills in the boxes. The other works with a property specialist who actively hunts for opportunities to improve their financial position. It’s not just about lodging a tax return; it's about having a strategist in your corner who helps build your portfolio for tax efficiency and long-term growth.
The Real-World Difference
A specialist’s value shines in the details that a generalist might completely miss. They operate with a level of foresight that translates directly into more money in your pocket.
- Repairs vs. Capital Improvements: They know the critical, money-saving difference. A simple repair, like fixing a broken window, can be an immediate tax deduction. But a capital improvement, like a full kitchen renovation, must be depreciated over many years. Getting this wrong can lock up thousands in claims you were entitled to.
- Strategic CGT Planning: When you decide to sell, a specialist doesn't just calculate your Capital Gains Tax (CGT). They work with you before the sale to legally minimise it. This could involve timing the sale perfectly or making sure every single eligible expense has been added to your property's cost base to reduce the final tax bill.
- Maximising Depreciation: This is where specialists really pay for themselves. They know exactly how to manage a tax depreciation schedule, claiming every possible deduction for the wear and tear on the building (capital works) and the assets inside it, like ovens, carpets, and air conditioners (plant and equipment).
A specialist property accountant does more than just report on the past; they help you build a more profitable future. Their advice on structure, depreciation, and tax planning can add tens of thousands of dollars to your net worth over the life of your investment.
Beyond the Tax Return
A true property tax expert becomes your financial partner, guiding you from the day you buy to the day you sell.
Depreciation Schedules and Asset Registers
One of their first jobs is to ensure you have a comprehensive depreciation schedule, usually prepared by a specialist quantity surveyor. Your accountant then uses this powerful document to claim every legitimate deduction, year after year.
An oven might be depreciable over 12 years, while new carpet might have an effective life of 10 years. A specialist tracks this meticulously, unlocking "on-paper" deductions that boost your cash flow without you spending another cent.
Structuring for Growth and Protection
As your portfolio expands, how you own the properties becomes crucial. Should you buy the next one in your personal name? Your spouse's? A trust? Or even a self-managed super fund (SMSF)?
A specialist gives you advice tailored to your exact situation, weighing up key factors like:
- The income levels of everyone involved
- Protecting your assets from creditors
- Your long-term estate planning goals
- Navigating land tax thresholds across different states
Getting the structure right from day one is invaluable. It can save you from huge tax headaches and costly restructuring fees later on. To get a better feel for professional tax help, understanding the benefits of using a tax agent can shed more light on the value they provide. It’s this strategic thinking that sets a specialist apart and makes their fee a high-return investment in your financial success.
Key Services Your Property Accountant Must Provide
Let’s get straight to it. When you’re hunting for an "investment property accountant near me," you need someone who does more than just lodge your tax return. Forget the basic number-crunchers. You’re looking for a sharp strategist who actively puts money back in your pocket.
A true property specialist builds the financial bedrock for your investment. Their work starts with rock-solid, ATO-compliant documents and extends all the way to high-level strategic advice that helps you build serious wealth over time. Here's what you should demand.
ATO-Compliant Rental Property Schedules
The absolute cornerstone of your tax return is the Rental Property Schedule. This isn't just a form; it's a forensic breakdown of every dollar of income you’ve earned and every single deductible expense you've paid. A good accountant lists them. A great one meticulously categorises everything so you can claim every cent you're entitled to and have the evidence to back it up if the ATO ever comes knocking.
With over 2.2 million residential rental properties in Australia reported in the 2021 Census, this is a huge area of focus for the tax office. It's why specialists like our teams at AWTS in Chippendale, Sydney, and Spring Hill, Brisbane are so critical. ATO data for the 2024-25 financial year showed landlords declared a massive $64.5 billion in gross rent. After deductions, however, the sector reported a net rental loss of $11.2 billion—a figure smart investors used to slash their tax on other income.
Capital Gains Tax Minimisation Strategies
Selling your investment property triggers a Capital Gains Tax (CGT) event. Get this wrong, and you could be handing over a huge chunk of your profit to the taxman. A top-tier property accountant doesn't just calculate the damage after you sell; they get involved before you sign anything to legally minimise the hit.
Their game plan will include moves like:
- Timing the Sale: The simplest, most effective strategy. They'll advise you to hold the property for more than 12 months to become eligible for the 50% CGT discount.
- Maximising Your Cost Base: This is where the real detail work happens. They’ll track every cost associated with buying, holding, and selling—from stamp duty and legal fees right down to major renovations—to beef up your cost base and shrink your taxable profit.
- Using Capital Losses: Got any carried-forward capital losses from other investments? A specialist will ensure they are used to offset your current gain, a move that’s often missed by generalists.
Here’s a real-world example: A client is ready to sell in May. A savvy accountant might point out that waiting until after July 1st pushes the CGT into the next financial year. This could drop the investor into a lower tax bracket or simply buy them more time to plan.
A proactive accountant saves you money by thinking ahead. Their advice before you sign a sales contract can be worth tens of thousands of dollars, turning a good sale into a great one.
Unlocking Cash Flow with Depreciation
Depreciation is the property investor's secret weapon. It’s a "non-cash" deduction, which means you get a tax benefit without actually spending any money that year. It’s also one of the most under-claimed deductions out there. A great accountant insists you get a quantity surveyor to prepare a tax depreciation schedule and then they squeeze every last dollar out of it for you.
They will meticulously claim for two key areas:
- Capital Works (Division 43): This is the wear and tear on the building's actual structure—the foundations, walls, and roof. It's generally claimed at 2.5% a year over 40 years.
- Plant and Equipment (Division 40): This covers all the assets inside the property, like ovens, carpets, blinds, and air conditioners. These items have a shorter effective life, so they can be depreciated much faster, giving your cash flow a serious boost.
Essential Structuring Advice
Once you own more than one property, how you own them becomes one of the most important financial decisions you’ll make. Should the next one be in your personal name? A family trust? Or a company? The wrong call can expose your family home to risk and lock you into a much higher tax bill for decades.
A specialist understands the complexities of different structures, including niche areas like real estate fund accounting. They’ll give you advice that lines up with your personal and financial goals, helping you build a fortress around your assets while ensuring your portfolio is set up for maximum tax efficiency. For a deeper dive into the nuts and bolts, check out our guide on how to prepare an investment property tax return.
How To Find And Vet The Best Local Property Accountants
So, you've decided you need a specialist. This is where your hunt for an "investment property accountant near me" gets real. Forget wading through endless, generic search results. Your mission is to find a genuine local expert who lives and breathes property tax.
You need to be precise with your search. Broad terms will get you nowhere fast. Instead, try drilling down with phrases like:
[Your Suburb] + rental property tax specialist[Your City] + accountant for capital gains taxproperty investment accountant Chippendale
This immediately cuts through the noise, filtering out the generalists and putting firms like our AWTS offices in Sydney and Brisbane on your radar—the ones that actively promote property investment as a core service, not just another line item on a long list.
A true property specialist offers more than just lodging your tax return. They become a key part of your investment strategy, from the initial setup to ongoing optimisation.

As you can see, basic tax prep is just the start. The real value lies in strategic advice on structure, cash flow, and long-term growth.
Vet Their Credentials and Experience
Once you’ve got a shortlist, the real work begins. This isn't about finding a friendly face; it's about verifying their expertise and making sure they're legally qualified to give you tax advice.
First, check their qualifications. Are they a Chartered Accountant (CA) or a Certified Practising Accountant (CPA)? More importantly, are they a Registered Tax Agent with the Tax Practitioners Board (TPB)? You can—and should—verify this for free on the TPB register. Only registered agents can legally charge you for tax services.
Next, do some digital digging. Scour their website and LinkedIn profiles. Do they have case studies about property investors? Are there blog posts breaking down CGT, depreciation, or negative gearing? A firm that truly specialises will be shouting it from the rooftops. If that content is missing, it’s a huge red flag.
Questions To Ask Before You Commit
That first phone call or meeting is your interview. It's your one chance to push past the marketing spin and test their real-world knowledge. Don't hold back—ask the tough questions.
Here are a few powerful questions to have ready:
- What percentage of your client base are property investors?
- Can you walk me through a complex property tax issue you've recently solved for a client?
- How do you maximise depreciation claims? Do you work directly with quantity surveyors?
- What strategies do you use to help clients structure their portfolios for better asset protection and tax outcomes?
A generalist will give you textbook answers. A specialist will hit you back with specific scenarios, practical strategies, and follow-up questions about your own portfolio. The depth of their experience will be obvious. While laws differ, the principle of vetting is universal, as even guides on Hiring a Property Tax Consultant in Texas will tell you.
A great accountant welcomes detailed questions. They see it as the beginning of a partnership, not an interrogation. If they get defensive or their answers are vague, walk away. They are not the expert you need.
Accountant Vetting Checklist
To keep your search organised, use this checklist. It will help you compare different accountants objectively and make a decision based on facts, not just a gut feeling.
| Vetting Step | What to Look For | Why It Matters |
|---|---|---|
| Online Presence | A professional website with a dedicated section for property investment services, plus insightful articles or resources. | This shows they’re committed to the niche and are actively thinking about property-specific tax issues. |
| Credentials | Must be a Registered Tax Agent. Preferably also a CPA or CA. Verify their registration number on the TPB website. | This confirms they are legally qualified and meet professional standards, protecting you from rogue advisors. |
| Client Reviews | Look for testimonials on Google or their website that specifically mention help with rental properties, CGT, or tax strategy. | Reviews from other investors are your best source of social proof that they deliver real results in this specific area. |
| Consultation | Do they ask you sharp questions about your goals, portfolio, and financial situation? Are their answers clear and confident? | This shows they’re interested in a strategic partnership, not just a one-off tax job. It’s a key sign of their service quality. |
Choosing the right accountant is one of the most important decisions you'll make as an investor. Taking the time to search methodically and vet properly ensures you find a partner who will actively help build your wealth. This process is crucial for anyone needing specific guidance, a topic we explore further for those searching for a tax return accountant near you.
What To Expect In Your First Meeting and How Much It Costs

Walking into that first meeting with a new accountant shouldn't be a mystery. You need to know what to expect, what it will cost, and how to make that first hour incredibly productive.
Let’s break down the typical fee structures you'll see and what you need to bring to hit the ground running. This is how you turn an initial chat into a partnership that saves you tax and headaches for years to come.
Common Fee Structures
Most specialist property accountants don't hide their fees; their pricing reflects the complexity of your finances and the expertise required. You'll generally come across two models.
- Fixed-Fee Packages: This is the most common approach for annual compliance, like lodging your tax return with its rental property schedule. You get a set price upfront, which gives you total cost certainty. This fee covers preparing the return, the rental schedule, and lodging it all with the ATO.
- Hourly Rates: For anything beyond standard compliance—think strategic planning, advice on structuring a purchase, or representing you in an ATO audit—accountants usually charge an hourly rate. The time involved can be unpredictable, so always ask for a fee estimate before they start the clock.
So, what's the damage? For a standard individual tax return that includes one investment property, you can expect to pay anywhere between $400 and $800+. This price tag varies based on the accountant’s experience, your location, and just how messy your shoebox of receipts is.
And don't forget, the fee you pay your tax agent is 100% tax-deductible on your next return.
The cost isn't just a fee; it's an investment. A great accountant should save you far more in tax and stress than their fee costs you. Their entire job is to find deductions and strategies you didn't know existed.
Preparing for Your First Meeting
To get real value out of that first appointment, you absolutely must come prepared. Walking in organised shows you’re serious and lets the accountant start finding opportunities for you straight away, rather than spending the hour just gathering basic info.
Use this checklist to get your documents in order.
New Client Documentation Checklist
- Proof of Identity: Your driver’s licence or passport will do.
- Previous Tax Returns: Bring at least your most recent one, if it’s handy.
- Property Settlement Statement: This is the critical document from your conveyancer. It’s the foundation for your property's cost base for Capital Gains Tax.
- Depreciation Schedule: If you’ve already got one from a quantity surveyor, bring it. If not, your new accountant will tell you it's the first thing you need to organise.
- Loan Statements: All of them. We need to see the total interest paid on the investment loan for the financial year.
- Summary of Rental Income: Your property manager's end-of-year statement is perfect.
- Summary of All Expenses: This means council rates, water rates, landlord insurance, property management fees, and every single receipt for repairs and maintenance.
This level of preparation is also non-negotiable for Aussies living or working overseas who own property back home. The ATO reported that over 1.1 million non-residents filed tax returns in 2025-26, and our team at AWTS looks after many of them through our offices in Queensland and Greece. For them, accurate records are everything. You can discover more insights about the tax obligations of non-resident property investors and see how our dedicated bookkeeping and tax services keep them compliant.
Having this information ready transforms the meeting from a simple get-to-know-you into a proper strategic session. Your new accountant can start building a clear picture of your finances, ensuring you maximise your investment's potential from day one.
Costly Property Tax Mistakes And How To Avoid Them
Navigating the tax rules for an investment property can feel overwhelming. Get it wrong, and you could be looking at thousands in missed deductions or, worse, a stressful audit from the Australian Taxation Office (ATO).
Many investors learn these lessons the hard way, but you don't have to. Understanding where the common traps lie is the first step to protecting your investment and maximising your returns. Let's look at the most expensive mistakes we see property investors make and how a specialist accountant can help you sidestep them.
Confusing Repairs With Capital Improvements
This is, without a doubt, the most common and financially damaging mistake an investor can make. It’s an easy one to get wrong, and it not only costs you immediate deductions but can also flag your return for an ATO review.
Here's the simple breakdown you need to remember:
- Repairs: These are tasks that fix or restore something to its original condition. Think replacing a few broken palings on a fence or patching a hole in the plaster. Repairs are generally 100% tax-deductible in the financial year you pay for them.
- Capital Improvements: This is any work that improves the property beyond its original state. For instance, replacing an entire fence or installing a brand-new kitchen is an improvement, not a repair. These costs are considered capital works and must be depreciated over many years—you can't claim them all at once.
A savvy investment property accountant will meticulously go through your expenses. They know exactly how to ensure every legitimate repair is claimed immediately to maximise your tax return this year, while correctly classifying improvements to be depreciated over their effective life.
The High Cost Of Disorganised Records
We see this cautionary tale all too often: the investor who loses thousands in legitimate claims simply because their records are a mess of faded, unorganised receipts. If you can't prove an expense to the ATO, you can't claim it. Period.
Imagine you paid for pest control, landlord insurance, a few minor plumbing fixes, and travelled to inspect the property. Without clear records—invoices, bank statements, and a logbook for your car—those deductions simply vanish. A specialist accountant helps you set up a simple but rock-solid system for record-keeping from day one, making sure no dollar is left on the table.
The difference between a profitable investment and a financial drain often comes down to one thing: meticulous record-keeping. Your accountant is your best ally in turning messy paperwork into significant tax savings.
Other Dangerous Tax Landmines
Beyond the big two, several other traps can catch out even experienced investors. Getting these wrong can have serious financial consequences that a specialist accountant is trained to help you avoid.
Miscalculating Your Cost Base for CGT
When you eventually sell your property, your Capital Gains Tax (CGT) is calculated on the profit. That profit is simply your sale price minus your "cost base." Here's the trap: many investors wrongly assume the cost base is just what they paid for the house.
In reality, it also includes buying costs like stamp duty and legal fees, plus the value of any capital improvements made over the years. Forgetting to track and include these expenses inflates your on-paper profit and, as a result, your final tax bill.
Taking Advice from Unqualified Sources
Your real estate agent is great at finding tenants, and online forums can offer general tips. However, neither are qualified or legally permitted to give tax advice. Taking their word on what you can or can't claim is a massive and unnecessary risk.
Only a registered tax agent has the expertise to provide advice that will stand up to ATO scrutiny.
A particularly tricky area is the Business Activity Statement (BAS). Many small to medium-sized enterprises (SMEs) in Australia, including those holding commercial investment properties, face strict BAS obligations. In 2025-26, the ATO noted that over 4.8 million businesses lodged BAS statements, but a staggering 12% of them copped penalties for late lodgement, totalling $450 million.
At Australia Wide Tax Solutions, our Sydney and Brisbane teams provide expert BAS preparation, preventing these exact errors that attract ATO audits. Learn more about how professional real estate accounting keeps you compliant and protects your investment.
Answering Your Top Property Accounting Questions
When you start searching for an “investment property accountant near me,” a heap of questions inevitably pop up. We get them every day from investors. Let's cut through the noise and give you the straight answers you need.
Can I Claim My Travel Costs For Inspecting The Property?
Yes, you can, but the ATO is watching this area like a hawk. You’re allowed to claim the costs of travel to inspect, maintain, or collect rent for your investment property. But your record-keeping has to be bulletproof.
To make a legitimate claim, the ATO expects you to:
- Keep a meticulous logbook showing your kilometres, the dates you travelled, and the exact reason for each trip.
- Hold onto every receipt for related costs. This includes things like flights or accommodation if your property is in another state.
- Prove the trip's main purpose was only for the investment property. A quick 10-minute "inspection" tacked onto a week-long family holiday just won't fly.
What Is The Difference Between A Tax Agent And An Accountant?
This is a really important distinction, and getting it wrong can cause major headaches. While plenty of professionals are both, their legal roles are different.
An accountant can help with your bookkeeping, financial reports, and general business advice. But here’s the key part: they cannot legally charge a fee to prepare and lodge your tax return unless they are also a Registered Tax Agent.
A Registered Tax Agent is a professional recognised by the Tax Practitioners Board (TPB). This registration confirms they have the right qualifications and experience to give tax advice and lodge documents for a fee. If you're paying someone for help with your property tax, they must be a registered agent.
In short, all registered tax agents can handle your tax accounting, but not all accountants are registered tax agents. For an investment property, you absolutely need a professional who is, at a minimum, a Registered Tax Agent with proven property expertise.
How Much Should I Budget For A Property Tax Return?
The cost for a tax return that includes a rental property schedule can vary, but you should expect to budget somewhere between $400 and $800+.
The final fee will depend on a few things: the complexity of your property portfolio, how organised your records are, and the accountant's level of experience. Honestly, you should think of this fee as an investment, not an expense. A sharp property accountant will almost always find more in tax savings and deductions than what their fee costs you. Their knowledge in areas like depreciation is where the real value lies.
Is The Fee I Pay My Accountant Tax-Deductible?
Absolutely. The fee you pay to a registered tax agent for managing your tax affairs—including the preparation and lodgement of your tax return—is 100% tax-deductible.
It’s a simple but powerful benefit. You claim the deduction in the next financial year. So, if you pay your accountant in July 2025 for your 2024-25 tax return, you’ll claim that fee as a deduction on your 2025-26 return.
Declare all rental income received: regular rent, advance rent, rent in kind, insurance payouts for lost rent, and bond money kept for unpaid rent. Gross rent before expenses is included in assessable income. The rental property schedule of the tax return captures income and expenses separately from other income.
Deductible expenses include council rates, water charges, land tax, insurance, property agent fees, repairs and maintenance, loan interest on funds borrowed for the property, advertising for tenants, and depreciation on eligible assets. Capital improvements are depreciated over time; borrowing costs are spread over five years or the loan term, whichever is shorter.
Negative gearing occurs when rental expenses exceed rental income. The net rental loss is deducted from your other assessable income (such as wages), reducing total taxable income and therefore tax payable. It is most beneficial for taxpayers in higher marginal brackets and must be reported accurately on the rental property schedule.
Yes. The sale triggers a CGT event. The gain is proceeds less cost base (purchase price, stamp duty, legal fees, and improvement costs). If owned for more than 12 months, apply the 50% CGT discount before adding the gain to assessable income. Previously claimed capital works deductions reduce the cost base and increase the eventual gain.
Yes, if the property is genuinely available for rent at a market rate. Expenses during a vacancy are deductible while the property is advertised. If the property is not genuinely available — reserved for personal use or listed above market rent — deductions may be denied or apportioned for the vacant period.
Navigating the complexities of property investment is a journey best taken with an expert guide. At Australia Wide Tax Solutions, our teams in Sydney and Brisbane specialise in providing strategic, ATO-compliant advice for property investors. Book your appointment online or in-person and let us help you maximise your returns and secure your financial future.
When you sell an investment property in Australia, getting your head around the selling investment property capital gains tax (CGT) implications is non-negotiable if you want to avoid a nasty surprise from the tax man. It’s important to know that CGT isn't a separate tax. It’s actually a part of your income tax.
- Understanding Capital Gains Tax on Your Investment Property
- How to Accurately Calculate Your Capital Gain or Loss
- Maximising the 50 Percent CGT Discount
- Finding Key CGT Exemptions and Concessions
- Strategic Timing and Smart Record Keeping
Put simply, any profit you make from selling the property gets added to your taxable income for that financial year, which can push you into a higher tax bracket and increase the tax you pay.
Understanding Capital Gains Tax on Your Investment Property
Think of Capital Gains Tax as the Australian Taxation Office's (ATO) share of the profit you've made from an asset's increase in value. For property investors, a capital gain happens when you sell your rental for more than what it cost you to buy and hold onto it. That profit is then tacked onto your income and taxed at your marginal rate.
But here’s the good news: the calculation isn't as blunt as 'sale price minus purchase price'. The ATO allows you to factor in a whole range of expenses to figure out your real profit. This is where a couple of key concepts come into play.
Key Terms You Need to Know
To really get how CGT works, you need to be comfortable with these core ideas:
- Capital Proceeds: This is the money you walk away with from the sale. It’s usually the contract sale price, but crucially, you get to subtract selling costs like real estate agent commissions and legal fees.
- Cost Base: This is probably the most powerful tool you have for minimising your tax bill. It’s not just the original purchase price. It also includes all the associated capital costs like stamp duty, conveyancing fees for the purchase, and the cost of any major improvements or renovations you’ve made over the years.
- Capital Gain or Loss: Your net capital gain is what’s left after you subtract the cost base from your capital proceeds. If you end up with a negative number, you’ve made a capital loss, which can be used to offset capital gains in the future.
The core principle is simple: the higher you can legitimately build your cost base, the lower your taxable capital gain will be. This is exactly why keeping meticulous records of every single expense related to buying and improving your property is so essential.
For a deeper dive, this essential guide to Capital Gains Tax on property is a great resource.
Getting on top of CGT early allows you to make strategic decisions long before you even think about putting the property on the market. One of the biggest strategies involves a powerful concession from the ATO. As you'll see, just holding your property for more than 12 months can slash your final tax bill thanks to the 50% CGT discount. We explore the timing of your sale and other strategic moves in our article on when you pay capital gains tax. A bit of forward planning can make a massive difference to your financial outcome.
How to Accurately Calculate Your Capital Gain or Loss
Working out the capital gains tax on your investment property isn't about getting tangled in complex algebra. At its heart, it's a simple process of addition and subtraction. Getting it right, however, is absolutely critical—both to stay on the right side of the ATO and to make sure you don't hand over a dollar more than you legally have to.
The whole calculation really boils down to three key numbers: your cost base, your capital proceeds, and the final gain or loss.
Think of it like working out the real profit you made from a side hustle. You wouldn't just look at the total sales; you’d carefully subtract all your setup costs and ongoing expenses first. Calculating your capital gain is exactly the same principle.
This diagram shows the straightforward, three-step flow of the calculation.
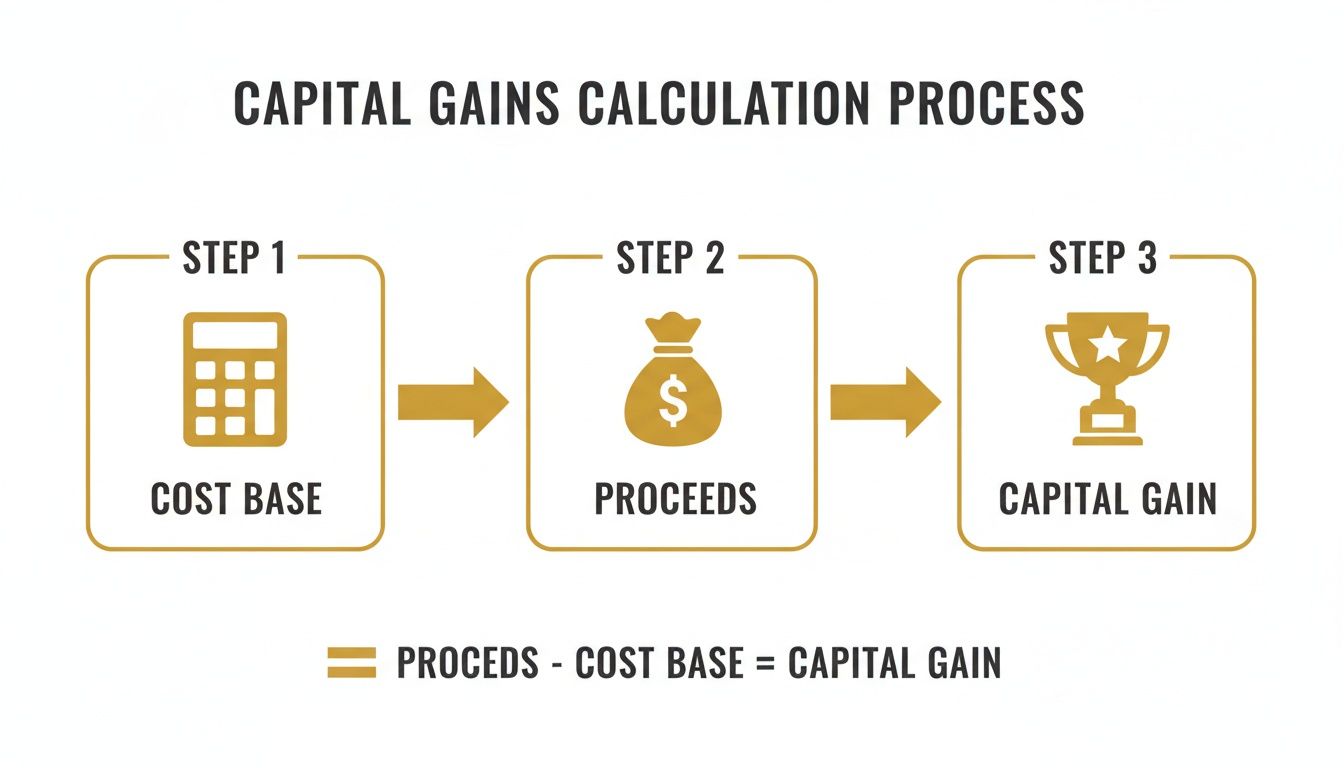
As you can see, the journey starts with locking down your costs, then defining what you walked away with from the sale, before finally arriving at the taxable figure.
Step 1: Build Your Property Cost Base
The cost base is the absolute foundation of your CGT calculation. More than that, it's your single most powerful tool for legally minimising your tax bill. It’s not just the purchase price; it's the grand total of every capital expense you've sunk into buying, holding, and improving the property over the years.
A truly comprehensive cost base is essential. Getting this right means you can significantly reduce your final capital gain, so it pays to be meticulous. Let's break down what goes into it.
The table below outlines the key elements that make up your property's cost base. Tracking these expenses diligently from day one can save you a small fortune when it's time to sell.
Key Components of Your Property's Cost Base
| Cost Element Category | Examples of Includable Expenses | Why It Matters |
|---|---|---|
| Initial Purchase Price | The final contract price you paid for the property. | This is the starting point for your calculation. |
| Acquisition Costs | Stamp duty, legal fees, conveyancing costs, buyer's agent fees, pest and building inspection reports. | These are significant upfront costs that directly increase your cost base. |
| Capital Improvement Costs | Major renovations (new kitchen/bathroom), adding a deck or extension, structural improvements, initial repairs to fix pre-existing defects. | These costs add to the property's value and your cost base, but routine maintenance doesn't count. |
| Title Costs | Legal fees related to preserving or defending your ownership or title of the property. | Any money spent legally protecting your asset can be included. |
| Disposal Costs | Real estate agent commissions, auction costs, advertising fees, legal fees for the sale. | These are the costs of selling, which are subtracted from your proceeds to reduce your final gain. |
By building a detailed and accurate cost base, you ensure that every legitimate expense works to reduce your final tax bill. It's the difference between paying tax on your true profit versus paying tax on an inflated figure.
Crucial point: You can't include any cost you've already claimed as a tax deduction during your ownership. Think things like interest on the investment loan, council rates, or repairs. This rule prevents "double-dipping" on tax benefits. For a deeper dive on what you can claim while you own the property, check out our guide on https://awts.net.au/blog/how-to-calculate-depreciation-on-rental-property/.
Step 2: Determine Your Capital Proceeds
Next up, you need to work out your capital proceeds. This is the total value you receive from selling your property.
For most people, this is simply the contract sale price. However, you don't stop there. You get to subtract the costs you paid to make the sale happen. This includes the real estate agent's commission, advertising fees, and any legal costs associated with the disposal. The figure you're left with is your net capital proceeds—the amount you truly pocketed.
Step 3: Calculate the Final Gain or Loss
Now it’s time to put it all together. The final step is beautifully simple:
Capital Proceeds - Cost Base = Total Capital Gain or Loss
If the result is a positive number, you’ve made a capital gain. If it's negative, you have a capital loss. You can’t claim a capital loss against your regular income, but you can use it to cancel out capital gains from other assets in the same year. If you have no other gains, you can carry it forward to offset future capital gains. To get this right, it's essential to understand how CGT on investment property is calculated in Australia.
For example, let’s say you sell a property for $1.2 million. Your cost base, after adding up the purchase price and all those eligible costs, is $500,000.
Your gross capital gain is $700,000. If you've held the property for more than 12 months, the 50% CGT discount kicks in, effectively halving your taxable gain. This means only $350,000 is added to your taxable income for the year. Assuming a marginal tax rate of 37%, your CGT bill would be around $129,500. Without that discount, you’d be looking at a staggering $259,000. It shows just how powerful the CGT discount can be.
Maximising the 50 Percent CGT Discount
When you wade into the world of selling investment property capital gains tax, the 50% CGT discount is easily the most powerful tool in the average Aussie investor's kit. It’s a major concession from the tax office that directly rewards a long-term, buy-and-hold investment strategy.
Simply put, this discount lets you chop your taxable capital gain clean in half. If you've made a decent profit on your property, applying this discount means only 50% of that gain gets added to your assessable income for the year. The difference this makes to your final tax bill can be monumental.
How to Qualify for the CGT Discount
The rules to get your hands on this discount are straightforward, but they are also incredibly strict. To unlock this massive tax saving, you have to meet two main conditions set by the Australian Taxation Office (ATO).
First up, the property must have been held for at least 12 months before you sign the contract of sale. This clock starts ticking from the date you acquired the asset and stops the moment you dispose of it. Timing is absolutely everything here—selling even one day short of that 12-month mark means you get nothing.
Secondly, the asset has to be owned by the right kind of entity. This includes:
- Individuals
- Trusts (including self-managed super funds)
- Partnerships
A Crucial Distinction: Companies are completely locked out of the 50% CGT discount. This is a vital point for investors who hold property inside a company structure. Understanding the tax implications of your ownership entity from day one is essential for any sensible tax planning.
This discount is a cornerstone of Australia's tax policy on investment. Analysis has shown that since it was introduced, the 50% CGT discount has resulted in forgone tax revenue of $247 billion over 25 years, a figure that highlights its immense value to investors. You can discover more insights into the financial impact of this tax concession on Accounting Times.
The Discount in Action: A Real-World Scenario
To really see the power of the 50% CGT discount, let’s walk through a clear before-and-after example. Imagine an investor named Chloe is getting ready to sell her investment property.
- Gross Capital Gain: Chloe works out her total capital gain is $200,000.
- Holding Period: She’s owned the property for five years.
- Her Marginal Tax Rate: Chloe's income puts her in the 37% tax bracket (plus the Medicare levy).
Now, let's see how the discount completely changes her tax outcome.
Scenario 1: Without the 50% CGT Discount
If Chloe wasn't eligible (let's say she sold after only 11 months), the full $200,000 capital gain would be tacked onto her taxable income. Her tax on this gain would be a painful $74,000 ($200,000 x 37%).
Scenario 2: With the 50% CGT Discount
Because Chloe was patient and held the property for over 12 months, she gets to apply the discount.
- Discount Applied: The $200,000 gain is slashed by 50%, leaving a taxable amount of $100,000.
- Tax Calculation: This $100,000 is added to her income. The tax on this much smaller gain is now only $37,000 ($100,000 x 37%).
Just by meeting that simple holding period rule, Chloe has pocketed an extra $37,000 in tax savings. This example shows exactly why strategic planning around that 12-month mark is so critical. It's a simple rule with a massive financial impact.
Finding Key CGT Exemptions and Concessions
While the 50% discount is a huge help, the Australian tax system has even more powerful tools to slash or completely wipe out your tax bill when you sell a property. Understanding the selling investment property capital gains tax rules becomes far more rewarding once you get your head around these key exemptions.
The biggest one by far is the main residence exemption. Put simply, your family home—the place you actually live—is generally exempt from Capital Gains Tax when you sell it. This rule makes sense; it acknowledges that your home is more than just a financial asset.
For property investors, though, things are rarely that straightforward. What happens if a property has served as both your home and an investment? This is exactly where a strategic understanding of the rules can save you tens of thousands of dollars.
The Main Residence Exemption Explained
At its core, the main residence exemption means you don't pay CGT on the sale of your primary home. To get the full exemption, the property must have been your main residence for the entire time you've owned it.
A couple of other conditions apply: the land around the home must be two hectares or less, and you can't have used the property to generate income. Tick all those boxes, and any capital gain you make is entirely tax-free.
But what if you've run a home business or, more commonly for investors, moved out and rented the place? This is where you might only qualify for a partial exemption. The ATO will need you to calculate the capital gain specifically for the period the property was used to earn an income. To dive deeper, you can learn more about how Australian capital gains tax exemptions work in practice.
The main residence exemption isn't an all-or-nothing rule. It's a flexible provision that can be applied partially, making it crucial for investors who have lived in their rental properties at some stage.
Getting the apportionment right between the exempt and non-exempt periods is absolutely vital for lodging an accurate tax return.
Unpacking the Powerful Six-Year Rule
This leads us to one of the most generous and frequently misunderstood provisions in Australian property tax: the six-year rule. This rule is a complete game-changer for anyone who has needed to move out of their home but wants to hold onto it as an investment.
In short, it allows you to move out of your main residence and rent it out for up to six years without losing the full main residence exemption. During that period, you can still treat the property as your home for tax purposes, meaning any capital gain that builds up during those rental years remains tax-free.
Of course, there are a few critical conditions:
- No Other Main Residence: You can't turn around and nominate another property as your main residence during that same period (with some minor exceptions for when you're moving between homes).
- Income-Producing Period: The six-year clock starts ticking the moment the property is first rented out.
- Multiple Absences: The best part? You can move back in, which resets the clock, and then use the six-year rule all over again for another absence down the track.
This provision offers incredible flexibility for modern life. It lets people take on work placements interstate or overseas, travel, or just try living somewhere new without being forced to sell their home to avoid a massive CGT bill later on.
Applying the Rules in a Real-World Scenario
Let's walk through how this works. Imagine you bought a home in 2018 for $600,000.
- Lived in it: You lived there as your main residence for four years, from 2018 to 2022.
- Rented it out: In 2022, you moved interstate for a new job and started renting the property out. You did this for three years.
- Sold it: In 2025, you decide to sell for $900,000, which gives you a total capital gain of $300,000.
Because your rental period of three years was well under the six-year limit, and you didn't purchase and nominate another main residence, you can apply the full main residence exemption. The entire $300,000 capital gain is completely tax-free.
Just by understanding this one rule, you've saved yourself a potential tax bill that could have easily topped $50,000.
Strategic Timing and Smart Record Keeping
When it comes to the selling investment property capital gains tax, a lot of the heavy lifting happens long before the "For Sale" sign goes up. It really boils down to two things you can actually control: when you sell and how well you’ve kept your records. This is where you move from just calculating tax to actively shaping your financial outcome.
Smart timing can literally shave thousands off your final tax bill. One of the most critical details people miss is that the CGT event is triggered on the date you sign the contract of sale, not the date of settlement. This small distinction opens up a huge window for strategic planning.
For example, if you know your income will be lower this financial year, you might hustle to exchange contracts before June 30. Conversely, if you expect a pay cut next year, delaying the contract signing until July 1 could be a game-changer. The goal is simple: have the capital gain added to your income in a year when your marginal tax rate is as low as possible.
The Power of the Calendar
Timing your sale isn't just about picking the right financial year; it's also about hitting key deadlines. The most famous one, of course, is holding the property for more than 12 months to qualify for that sweet 50% CGT discount. Selling just one day too early could literally double your tax liability. It’s a costly mistake to make.
Broader economic changes, like shifts in income tax brackets, also play a massive role. The Stage 3 tax reforms kicking in from July 2024 are a perfect example. Someone earning $120,000 who sells in the 2025 financial year will have their gain taxed at the new 30% rate, instead of the old 37%. That’s a huge difference, potentially saving thousands, purely by aligning the sale with more favourable tax laws. You can see a great breakdown of how the 2025 tax changes impact property sales with Amplify 11.
Your Non-Negotiable Record-Keeping Checklist
While timing is about strategy, meticulous record-keeping is the foundation everything is built on. Without proof, you can't add an expense to your cost base, and an incomplete cost base means you pay more tax than you need to. The Australian Taxation Office (ATO) can ask for evidence for every single dollar you claim, so keeping organised digital and physical records is simply non-negotiable.
Think of your records as a complete financial diary of the property. Start a folder the moment you even think about buying, and be religious about adding to it.
Your records are your ultimate defence against overpaying tax. Every receipt, invoice, and contract you keep is a tool that directly reduces your taxable capital gain, putting more of your hard-earned profit back in your pocket where it belongs.
Here is the definitive checklist of documents you absolutely must keep for at least five years after you lodge the tax return that includes the sale:
-
Acquisition Records:
- The original purchase contract.
- Conveyancing documents and all related legal fee invoices.
- Proof of stamp duty paid.
- Receipts for building and pest inspections.
-
Improvement Costs:
- Invoices and receipts for all capital works—think renovations, extensions, or any major structural improvements.
- Costs for initial repairs to fix defects that were there when you bought the place.
-
Holding Costs:
- Documents for legal fees if you ever had to defend your title to the property.
- Any loan application and mortgage discharge fees.
-
Disposal Records:
- The final contract of sale.
- Invoices for the real estate agent’s commission and advertising costs.
- Receipts for all legal fees tied to the sale.
This diligent approach ensures your cost base is as high and accurate as legally possible, which directly minimises the profit you’ll ultimately be taxed on.
When Your Former Home Becomes an Investment Property
Many investment properties started life as the owner's home. When you rent out a former main residence, special rules determine how much of any future capital gain is taxable.
Partial Exemption and the Market Value Rule
If a property was your home before becoming a rental, you are generally entitled to a partial main residence exemption for the period you lived there. Under the "home first used to produce income" rule, the property is typically deemed to have been acquired at its market value on the date you first rented it out — so a valuation at that point is essential. The six-year rule may also apply, potentially keeping the gain exempt for up to six years of rental. Getting the dates and valuations right here is where professional advice pays for itself.
Frequently Asked Questions About Selling and CGT
Once you get your head around the formulas for CGT, the real-world questions start popping up. It's one thing to know the principles of calculating tax, but how do they actually play out when you're in the thick of a property sale?
This is where the theory meets reality. Let's tackle some of the most common "what if" scenarios that investors face, so you can plan your sale with a clear head.
When Exactly Do I Pay the Capital Gains Tax?
This is easily one of the biggest points of confusion, especially for first-time sellers. Many people expect a separate tax bill to land in their letterbox shortly after the property settles.
But that’s not how it works. Your net capital gain is simply added to your assessable income for that financial year. You then pay tax on this new, higher total income when you lodge your annual tax return with the Australian Taxation Office (ATO). It’s all rolled into one.
The most important date to remember here is the contract of sale date, not the settlement date. The financial year you sign that contract is the financial year the gain is taxed in.
Can I Claim the Main Residence Exemption if I Rented My Home Out?
Yes, you often can, and this is where you can see the flexibility built into Australia’s tax laws. If the property was your primary home before you started renting it out, you can usually claim a partial exemption from CGT.
The ‘six-year rule’ is your best friend here. It’s a powerful provision that lets you treat the property as your main residence for up to six years after you’ve moved out, provided you’re using it to generate income (like renting it out).
Important Condition: The catch is that you cannot claim another property as your main residence during that same period. Get this right, and you can pocket some significant tax savings, even after the property has been an investment for years.
If you rented it out for more than six years, the exemption gets pro-rated. You’d calculate a partial gain based on the proportion of time it was an investment property versus your home.
What Happens if I Sell My Property at a Loss?
Selling for less than you paid results in a capital loss. While it’s disappointing, this loss is still a valuable asset for tax purposes. You just can’t use it to reduce your regular taxable income, like your salary.
Here’s the process:
- Offset Current Gains: First, you must use the capital loss to cancel out any other capital gains you’ve made in the same financial year. For instance, a loss on your property can wipe out a gain from selling some shares.
- Carry it Forward: If you don't have any other capital gains to offset, or your loss is bigger than your gains, the remaining loss can be carried forward indefinitely. You can then use it against capital gains in future years.
This means a loss today could still help reduce your tax bill on a different, successful investment years from now.
Are Ownership Costs Included in the Cost Base?
This is a crucial point to get right to avoid "double-dipping" on tax deductions. The general rule is you cannot include ongoing ownership costs in your cost base if you have already claimed them as tax deductions against your rental income.
These are your typical running expenses:
- Interest on the investment loan
- Council and water rates
- Land tax
- Insurance premiums
- Property management fees
- Repairs and maintenance
Your cost base is reserved for capital costs—the big-ticket items related to buying, significantly improving, and selling the property. Trying to include expenses you've already claimed is a surefire way to attract unwanted attention from the ATO.
How Does CGT Work for Inherited Properties?
Inheriting a property throws another layer of complexity into the mix. The tax rules depend heavily on when the deceased bought the property and what it was used for.
- Pre-CGT Asset (Acquired before 20 September 1985): If you inherit a property the deceased purchased before this date, you might be completely exempt from CGT when you sell it, as long as it wasn't used to produce income.
- Post-CGT Asset (Acquired on or after 20 September 1985): If the property was the deceased's main home, you’re generally exempt from CGT if you sell it within two years of their passing.
- Investment Property: If you inherit a rental property, you also inherit its cost base. When you sell, your capital gain or loss is calculated from what the deceased originally paid, not its value when you received it.
Given how tricky this can get, getting professional advice for an inherited property is always a smart move to ensure everything is handled correctly.
Depreciation reduces an asset's cost base. When you sell, previously claimed Division 40 depreciation triggers a balancing adjustment. For Division 43 capital works deductions claimed from 1 July 2017, the amount reduces the building's cost base, increasing the eventual capital gain. The interaction between depreciation and CGT requires careful calculation at time of sale.
A quantity surveyor prepares a tax depreciation schedule by physically inspecting the property and identifying all depreciable assets and their values. The ATO accepts these estimates for depreciation claims where original receipts are unavailable. The fee is tax deductible. A schedule maximises your annual depreciation claims based on a comprehensive site assessment.
Division 43 covers the capital works deduction on structural components (walls, floors, roof) at 2.5% per year for buildings constructed after 15 September 1987. Division 40 covers plant and equipment (appliances, carpet, blinds) depreciated over their ATO-determined effective life. Post-May 2017 legislation restricts Division 40 claims on second-hand residential assets for new buyers.
Yes. The May 2017 restrictions on second-hand plant and equipment only apply to residential properties. Commercial property investors can still claim Division 40 depreciation on second-hand assets. Division 43 capital works deductions apply to both property types based on construction date, not acquisition date.
Keep the purchase contract, settlement statement, receipts for capital improvements, and a quantity surveyor's depreciation schedule. The ATO can request these records for five years after the relevant income year. Without records, depreciation claims can be reduced or disallowed on audit, and you may lose the ability to substantiate cost base adjustments at sale.
Navigating the specifics of selling investment property capital gains tax requires careful planning and a clear understanding of the rules. To ensure you maximise your return and meet all your ATO obligations, professional guidance is invaluable. The experts at Australia Wide Tax Solutions specialise in property tax and can help you develop a strategy that minimises your tax liability.
Don't leave your hard-earned profits on the table. Contact us today for personalised advice at https://www.awts.net.au.
When your clients apply for a mortgage, banks don't just take their word for it regarding income and financial position. One of the most critical documents in the approval process is the accountant's letter – but why exactly do banks insist on this requirement?
- The Banking Perspective: Risk Management Above All
- What Banks Want to See in Accountant Letters
- The Value Proposition for Mortgage Brokers
- Common Challenges and Solutions
- Best Practices for Mortgage Brokers
The Banking Perspective: Risk Management Above All
Banks are in the business of lending money, but they're also in the business of getting it back. Every loan represents a calculated risk, and accountant letters serve as independent verification of a borrower's true financial position.
Here's what banks are really looking for:
1. Independent Professional Verification
Banks need assurance that income figures aren't inflated or manipulated. An accountant's professional opinion carries legal weight and provides third-party validation that internal bookkeeping or self-reported figures simply cannot match.
2. Comprehensive Financial Health Assessment
While tax returns show historical performance, accountant letters provide:
- Current year projections
- Cash flow analysis
- Business sustainability insights
- Professional assessment of ongoing viability
3. Regulatory Compliance Requirements
Under APRA guidelines, banks must demonstrate due diligence in their lending decisions. Accountant letters help satisfy these regulatory requirements by showing the bank has obtained professional verification of borrower capacity.
What Banks Want to See in Accountant Letters
Essential Elements Include:
- Confirmation of income figures and their sustainability
- Assessment of business performance trends
- Professional opinion on the borrower's ability to service debt
- Verification of financial statements accuracy
- Commentary on any unusual circumstances or seasonal variations
Red Flags Banks Watch For:
- Declining revenue trends
- Inconsistent cash flow patterns
- High business expenses relative to income
- Lack of business continuity indicators
The Value Proposition for Mortgage Brokers
Understanding why banks require these letters positions you to:
Educate Clients Proactively
Instead of clients being surprised by this requirement, you can prepare them during the initial consultation. This demonstrates your expertise and prevents delays in the application process.
Strengthen Professional Networks
Building relationships with qualified accountants who understand mortgage requirements creates a valuable referral network. Accountants who can write comprehensive, bank-friendly letters become invaluable partners.
Differentiate Your Service
Many brokers simply tell clients, "You need an accountant letter." You can explain the why behind the requirement, helping clients understand the process and feel more confident in your guidance.
Common Challenges and Solutions
Challenge: Clients using basic bookkeepers who can't provide adequate letters.
Solution: Maintain a network of qualified accountants who specialise in mortgage-related documentation
Challenge: Accountant letters that lack sufficient detail.
Solution: Provide accountants with a template or checklist of bank requirements
Challenge: Timing delays when accountants are busy. Solution: Build relationships with multiple accounting firms and plan ahead during peak periods
Best Practices for Mortgage Brokers
- Set Expectations Early: Explain the accountant letter requirement during initial consultations
- Recommend Qualified Professionals: Partner with accountants who understand banking requirements
- Plan for Timing: Factor in 48-72 hours for quality accountant letters
- Review Before Submission: Ensure letters address all bank-specific requirements
The Bottom Line
Banks require accountant letters because they provide independent, professional verification that protects both the lender and the borrower. For mortgage brokers, understanding this requirement – and helping clients navigate it smoothly – demonstrates expertise and adds significant value to your service.
When you can explain not just what banks need, but why they need it, you position yourself as a trusted advisor rather than just another broker processing applications.
Ready to streamline your clients' accountant letter process?
Consider partnering with accounting firms that specialise in mortgage documentation and understand the urgency of your timelines. Call us!
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
Understanding Investment Property Deductions
Before we dive into the specific strategies, it is essential to have a strong foundation of understanding regarding investment property deductions. This section will provide you with the basics of property deductions, as well as introduce you to the key terms and concepts associated with this topic. Investing in property can be a lucrative venture, but it also comes with its fair share of expenses. However, the good news is that many of these expenses can be claimed as deductions, helping you reduce your taxable income and ultimately save on taxes. When it comes to investment property deductions, there are several key expenses that you can claim. These include interest on loans, property management fees, repairs and maintenance costs, insurance premiums, and depreciation. Let's take a closer look at each of these deductions:- Interest on Loans: If you have taken out a loan to finance your investment property, you can deduct the interest paid on that loan. This deduction can be a significant benefit, especially in the early years of your investment when interest payments are typically higher.
- Property Management Fees: If you hire a property management company to handle the day-to-day operations of your investment property, the fees you pay them can be claimed as a deduction. This includes fees for advertising, tenant screening, rent collection, and property maintenance.
- Repairs and Maintenance Costs: Any expenses incurred for repairs and maintenance of your investment property can be deducted. This includes fixing plumbing issues, repainting walls, replacing broken appliances, and other similar expenses. It is important to note that improvements that add value to the property, such as renovations, are not considered repairs and may not be fully deductible.
- Insurance Premiums: The insurance premiums you pay to protect your investment property can also be claimed as a deduction. This includes coverage for property damage, liability, and rental income loss.
- Depreciation: Depreciation refers to the gradual decrease in the value of an asset over time. In the context of property deductions, depreciation can be claimed as an expense, reflecting the wear and tear on your investment property. This deduction can be a significant benefit, as it allows you to account for the declining value of your property and recoup some of the initial investment.
- Depreciation: Depreciation refers to the gradual decrease in the value of an asset over time. In the context of property deductions, depreciation can be claimed as an expense, reflecting the wear and tear on your investment property.
- Taxable Income: This refers to the portion of your income that is subject to taxation after deductions have been applied. Maximising your deductions can reduce your taxable income and potentially lower your tax liability.
- Tax Compliance: Tax compliance refers to adhering to the tax authorities' regulations and laws to report and pay taxes correctly. It is important to stay up to date with the latest tax laws and seek professional advice if needed to ensure you comply with all applicable regulations.
The Role of Depreciation in Maximizing Deductions
Depreciation is a crucial factor in maximising your investment property deductions. By understanding how depreciation works and how it impacts your deductions, you can optimise your financial position.Depreciation Explained
Depreciation refers to the decrease in value of an asset over time due to wear and tear, aging, or obsolescence. In the context of investment property, both the building and the fixtures within it can be depreciated. There are two types of depreciation: capital works and plant and equipment. Capital works depreciation pertains to the building's structure, while plant and equipment depreciation relates to the assets within the building, such as air conditioning units, carpets, and furniture.How Depreciation Impacts Your Deductions
Claiming depreciation as an expense can significantly impact your deductions and ultimately reduce your taxable income. By accurately calculating and claiming depreciation expenses, you can recoup a portion of the property's value over time. It is essential to engage a qualified quantity surveyor or tax depreciation specialist to conduct a depreciation schedule and maximize your deductions. This professional will assess your property and identify all depreciable assets, ensuring that you claim the maximum deduction available to you.Strategies for Maximizing Your Deductions
Now that you have a solid understanding of investment property deductions and the role of depreciation, it's time to explore some strategies that can help you maximize your deductions and ultimately save on taxes.Timing Your Expenses
Timing is key when it comes to maximizing your deductions. By carefully timing when you incur expenses, you can ensure that you receive the maximum benefit from your deductions. For example, if you are planning significant repairs or renovations on your property, strategically scheduling these expenses to span over different financial years can help you optimize your deductions. Additionally, keeping detailed records of all your expenses throughout the year will make it easier to claim deductions when tax time rolls around. Utilizing accounting software or apps specifically designed for property investors can simplify expense tracking and ensure that nothing falls through the cracks.Utilizing Professional Services
When it comes to navigating the complex world of property deductions, professional guidance can be invaluable. Engaging the services of a qualified accountant or tax advisor who specializes in investment properties can provide you with expert advice tailored to your specific circumstances. A knowledgeable professional can help you identify all eligible deductions, ensure that you are complying with tax regulations, and maximize your tax savings. This investment in professional services can yield significant financial benefits and provide peace of mind.Common Mistakes to Avoid
While maximizing your investment property deductions is essential, it is equally important to avoid common pitfalls and mistakes that could undermine your efforts. Let's explore some of the common mistakes and how to avoid them.Overlooking Small Deductions
It's easy to focus on significant expenses when it comes to property deductions but overlooking small expenses can add up over time. Every deductible expense counts, so it's important to meticulously track and document even the smallest costs. Keeping a dedicated folder or digital file for all your expense receipts and invoices will ensure that you have a comprehensive record of all eligible deductions. This attention to detail will help you maximize your savings and reduce the risk of missing out on potential deductions.Misunderstanding the Rules
Another common mistake property investors make is misunderstanding the rules and regulations surrounding investment property deductions. Tax laws can be complex and subject to change, so it's crucial to stay informed and up to date with the latest legislation. Regularly reviewing the relevant tax authorities' websites, attending property investment seminars, or joining investor forums can provide you with valuable insights and help you stay ahead of any changes. Seeking professional advice when needed can also help clarify any confusion or gray areas.Navigating Tax Laws and Regulations
The landscape of tax laws and regulations is ever-evolving. As an investment property owner, it is crucial to stay up to date with any changes that may impact your deductions. Let's explore some strategies for navigating this complex environment.Keeping Up with Changes
Staying informed and proactive is key to navigating the ever-changing tax landscape. Subscribing to newsletters or updates from tax authorities, consulting with professionals, and regularly reviewing the relevant legislation will help ensure that you are aware of any changes that may affect your deductions. Allocating dedicated time each year to review your investment property deductions and staying up to date with any new rules or regulations will set you up for success and prevent any unpleasant surprises at tax time.Seeking Legal Advice
Tax laws can be complex, and seeking legal advice can provide you with the clarity and assurance you need to navigate this terrain successfully. Consulting with a qualified real estate attorney can help you navigate any legal complexities specific to your investment property and ensure that you are fully compliant with all relevant regulations.Conclusion
Maximising your investment property deductions requires a solid understanding of the key strategies and concepts involved. By effectively utilising depreciation, strategically timing your expenses, and seeking professional advice, you can optimise your deductions and save on taxes. It is crucial to avoid common mistakes such as overlooking small deductions and misunderstanding the rules. By staying informed and proactive, you can navigate the ever-changing tax landscape successfully. Remember, maximising your investment property deductions takes time, effort, and attention to detail, but the financial benefits make it well worth the investment. By implementing the strategies outlined in this article, you can make substantial tax savings and maximise the return on your investment property portfolio.Depreciation reduces an asset's cost base. When you sell, previously claimed Division 40 depreciation triggers a balancing adjustment. For Division 43 capital works deductions claimed from 1 July 2017, the amount reduces the building's cost base, increasing the eventual capital gain. The interaction between depreciation and CGT requires careful calculation at time of sale.
A quantity surveyor prepares a tax depreciation schedule by physically inspecting the property and identifying all depreciable assets and their values. The ATO accepts these estimates for depreciation claims where original receipts are unavailable. The fee is tax deductible. A schedule maximises your annual depreciation claims based on a comprehensive site assessment.
Division 43 covers the capital works deduction on structural components (walls, floors, roof) at 2.5% per year for buildings constructed after 15 September 1987. Division 40 covers plant and equipment (appliances, carpet, blinds) depreciated over their ATO-determined effective life. Post-May 2017 legislation restricts Division 40 claims on second-hand residential assets for new buyers.
Yes. The May 2017 restrictions on second-hand plant and equipment only apply to residential properties. Commercial property investors can still claim Division 40 depreciation on second-hand assets. Division 43 capital works deductions apply to both property types based on construction date, not acquisition date.
Keep the purchase contract, settlement statement, receipts for capital improvements, and a quantity surveyor's depreciation schedule. The ATO can request these records for five years after the relevant income year. Without records, depreciation claims can be reduced or disallowed on audit, and you may lose the ability to substantiate cost base adjustments at sale.
How Much Does a House Valuation Cost in Australia?
Buying a house is one of the most significant financial decisions most people will make. Before taking that leap, it's crucial to understand the true value of the property you're considering. That's where a professional house valuation comes into play.
- How Much Does a House Valuation Cost in Australia?
- What is a House Valuation?
- Average Cost of a House Valuation in Australia
- Factors That Influence House Valuation Costs
- How to Get the Best Value for a House Valuation
In Australia, getting an accurate property valuation is an essential step in the home buying or selling process. But how much does a house valuation cost? The answer can vary quite a bit depending on several factors. In this blog post, we'll dive into the typical costs associated with house valuations in Australia and help you understand what to expect.
What is a House Valuation?
A house valuation, also known as a property appraisal, is an assessment of a home's market value conducted by a qualified, independent professional. This assessment considers factors like the home's size, age, condition, location, and recent sales of comparable properties in the area.
A house valuation's main purpose is to determine a property's fair market value. This information is crucial for:
- Home buyers - To ensure they are paying a reasonable price for the property
- Home sellers - To price their home competitively and maximize their return
- Mortgage lenders - To assess the value of the property being used as collateral for a loan
- Property investors - To evaluate the potential return on an investment property
Having an accurate, up-to-date valuation is important throughout the home-buying and selling process. Lenders will require a professional valuation before approving a mortgage, and sellers need to price their homes appropriately to attract buyers.
Average Cost of a House Valuation in Australia
The cost of a house valuation in Australia can vary quite a bit but generally falls somewhere between $300 to $600. The exact price will depend on several key factors:
1. Location
House valuation costs are higher in major cities and metropolitan areas than in regional or rural locations. This is because property values are typically higher in urban centres, requiring more in-depth analysis by the valuer.
For example, a house valuation in Sydney or Melbourne may cost $400-$600, while a similar assessment in a smaller town could be closer to $300-$400.
2. Property Type
The type of property being valued can also impact the cost. Evaluating a standard single-family home is generally less complex than assessing a multi-unit apartment building or a luxury mansion.
Factors like a property's size, age, and unique features will determine how much time and effort the valuer needs to put into the assessment. More complex or high-end properties usually attract a higher valuation fee.
3. Purpose of the Valuation
The reason for needing the property valuation can also affect the cost. Mortgage valuations, for example, are typically less expensive than a detailed market appraisal for selling a home.
Mortgage lenders may only require a "drive-by" valuation, which involves a quick inspection of the exterior and a review of recent comparable sales. This type of valuation usually costs $300-$400.
In contrast, a comprehensive market appraisal for selling a home will involve a more thorough interior and exterior inspection and an in-depth analysis of the local real estate market. This type of detailed valuation often costs $400-$600.
4. Additional Services
Some valuation providers may offer additional services that can increase the overall cost, such as:
- Digital floor plans
- Detailed property reports
- 3D property scans
- Advice on renovations or improvements
While these extra features can provide more value, they will add to the final price of the house valuation.
Factors That Influence House Valuation Costs
Beyond the basic cost range, several other factors can impact the final price of a house valuation in Australia:
Valuation Provider
The specific company or individual conducting the valuation can affect the price. Larger, more established valuation firms may charge higher rates than smaller, independent providers. However, the valuer's expertise and reputation are also important considerations.
Turnaround Time
If you need a quick turnaround on the valuation report, the provider may charge a rush or expedited service fee. Standard turnaround times are typically 5-10 business days but can be as fast as 1-2 days for an additional cost.
Additional Property Inspections
Some valuers may need to conduct more in-depth inspections or research, such as:
- Surveying the land boundaries
- Assessing the condition of the roof, plumbing, or electrical systems
- Reviewing council records or zoning information
These extra steps can increase the overall valuation cost.
Travel Expenses
For properties located in remote or hard-to-access areas, the valuer may need to charge additional travel fees to cover the time and costs of getting to the site.
How to Get the Best Value for a House Valuation
With the wide range of house valuation costs in Australia, it's essential to do your research and find the right provider for your needs. Here are some tips to ensure you get the best value:
- Shop Around: Get quotes from multiple valuation companies and compare their services, expertise, and pricing. Don't just go with the lowest bidder - look for a provider that offers quality work at a fair price.
- Understand the Scope of Services: Make sure you know exactly what's included in the valuation and any additional fees for extra services. This will help you compare apples to apples when evaluating different providers.
- Consider the Valuer's Qualifications: Look for a certified, experienced property valuer familiar with the local real estate market. Their expertise can be worth paying a slightly higher fee.
- Time it Right: If your timeline is flexible, try to schedule the valuation during the provider's slower periods to get a better rate potentially. Avoid peak seasons like the end of the financial year.
- Provide Accurate Property Details: Supplying the valuer with detailed information about your home upfront can help streamline the process and keep costs down. This includes the number of bedrooms/bathrooms, lot size, year built, and recent renovations.
- Consider Package Deals: Some valuation companies offer discounted rates if you bundle their services, such as getting a pre-purchase and market appraisal. This can provide better value than purchasing each service individually.
By following these tips, you can find a qualified house valuation provider in Australia who delivers high-quality work at a fair and reasonable price.
Conclusion
Getting an accurate property valuation is a critical step in the home buying or selling process. While the cost of a house valuation in Australia can vary slightly, most fall within the $300 to $600 range.
The exact price you'll pay depends on factors like the location, property type, purpose of the valuation, and any additional services required. By understanding these cost drivers and shopping around, you can find a qualified valuation provider that offers the best value for your needs.
Investing in a professional house valuation is well worth ensuring you make an informed real estate decision, whether you're a buyer, seller, or investor. Take the time to find the right provider, and you'll have the peace of mind of knowing the property's true market value. If you want us to organise a house valuation with one of our specialists, please send your query about the house valuation when contacting us.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
Is Rental Income Taxable?
Introduction Rental Income
As a property owner in Australia, understanding the tax implications of your rental income is crucial. Whether you're a seasoned investor or a first-time landlord, navigating the complexities of rental income taxation can be daunting. In this comprehensive blog post, we'll explore the key aspects of rental income taxation in Australia, providing you with the information you need to ensure compliance and maximize your returns. Is Rental Income taxable in Australia?
- Is Rental Income Taxable?
- Understanding Rental Income
- Determining Taxable Rental Income
- Reporting Rental Income on Your Tax Return
- Rental Property Deductions
Understanding Rental Income
Rental income in Australia refers to the money you receive from leasing out a property, such as a house, apartment, or investment property. This income is considered assessable income and must be reported on your annual tax return. Rental income includes not only the regular monthly or weekly rent payments but also any other payments related to the rental, such as:
- Bond or security deposit payments
- Fees for early termination of a lease
- Reimbursements for expenses paid by the landlord
- Payments for the use of furnishings or other assets
It's important to note that rental income is taxable regardless of whether the property is your primary residence or an investment property. Is Rental Income taxable in Australia?
Determining Taxable Rental Income
To calculate your taxable rental income, you'll need to consider the following:
- Gross Rental Income: This is the total amount of rent and other payments you receive from your tenants.
- Allowable Deductions: As a landlord, you can claim a range of expenses related to your rental property as tax deductions. These may include:
- Interest on loans used to purchase the property
- Property management fees
- Repairs and maintenance costs
- Insurance premiums
- Council rates and water charges
- Depreciation on the property and its assets
- Net Rental Income: This is the amount of rental income remaining after subtracting your allowable deductions from your gross rental income. This net amount is what you'll need to report on your tax return.
It's important to keep accurate records of all your rental income and expenses, as this will make the tax-filing process much smoother and help you maximize your deductions.
Reporting Rental Income on Your Tax Return
When it comes to reporting your rental income on your tax return, the process is relatively straightforward:
- Include Rental Income in Your Assessable Income: You must report your net rental income as part of your assessable income on your individual tax return (known as a "personal income tax return" or "individual tax return").
- Claim Allowable Deductions: You can claim the various expenses related to your rental property as deductions on your tax return, which will reduce your overall taxable income.
- Consider Capital Gains Tax: If you sell your rental property, any capital gain (the difference between the sale price and your original purchase price, minus any eligible deductions) may be subject to capital gains tax.
- Seek Professional Advice: It's always a good idea to consult with a qualified tax professional, such as a registered tax agent or accountant, to ensure you're properly reporting your rental income and maximizing your tax deductions.
Rental Property Deductions
As mentioned earlier, landlords in Australia can claim a range of deductions related to their rental properties. Some of the most common deductions include:
- Interest on Loans: You can deduct the interest paid on loans used to purchase, renovate, or maintain your rental property.
- Property Management Fees: If you use a property management company to handle the day-to-day operations of your rental property, their fees are tax-deductible.
- Repairs and Maintenance: Expenses incurred for repairing and maintaining your rental property, such as fixing a leaky roof or painting the interior, are generally tax-deductible.
- Insurance Premiums: The cost of insurance policies, such as landlord insurance or building insurance, can be claimed as a deduction.
- Council Rates and Water Charges: The local council rates and water charges you pay for your rental property are also tax-deductible.
- Depreciation: You can claim deductions for the gradual wear and tear of your rental property and its assets, such as appliances, furniture, and fixtures.
- Travel Expenses: If you need to travel to your rental property for inspections, repairs, or other management-related activities, you may be able to claim a deduction for your travel expenses.
It's important to note that the deductibility of certain expenses may depend on the specific circumstances of your rental property and your personal tax situation. Consulting with a tax professional can help you identify all the eligible deductions and ensure you're claiming them correctly.
Rental Property Tax Obligations
As a landlord in Australia, you have several tax obligations to fulfill:
- Reporting Rental Income: You must report your net rental income on your individual tax return each year.
- Paying Income Tax: The net rental income you report will be subject to your marginal income tax rate, which can range from 0% to 45%, depending on your total taxable income.
- Capital Gains Tax: If you sell your rental property, any capital gain (the difference between the sale price and your original purchase price, minus any eligible deductions) may be subject to capital gains tax.
- Goods and Services Tax (GST): If your rental property is considered a commercial or investment property, you may need to register for and pay GST on the rent you receive.
- Pay-As-You-Go (PAYG) Withholding: If you have tenants who are employees, you may be required to withhold and remit PAYG tax on their behalf.
Staying up-to-date with your rental property tax obligations and seeking professional advice can help you avoid penalties and ensure you're complying with all relevant tax laws.
Tax Planning Strategies for Rental Properties
To maximize your returns and minimize your tax obligations, consider the following tax planning strategies for your rental property:
- Depreciation Deductions: Claim deductions for the gradual wear and tear of your rental property and its assets, such as appliances, furniture, and fixtures.
- Negative Gearing: If your rental expenses, including interest on loans, exceed your rental income, you may be able to claim the difference as a tax deduction, reducing your overall taxable income.
- Timing of Repairs and Maintenance: Schedule repairs and maintenance work to coincide with the end of the financial year, as these expenses can be claimed as deductions in the current year.
- Property Improvements: Distinguish between repairs (which are immediately deductible) and improvements (which are generally deductible over time through depreciation).
- Rental Property Ownership Structure: Consider the most appropriate ownership structure for your rental property, such as individual ownership, joint ownership, or a trust, to optimize your tax outcomes.
- Rental Property Insurance: Review your insurance policies to ensure you're claiming all eligible deductions, such as landlord insurance premiums.
- Maximizing Deductions: Keep detailed records of all your rental income and expenses, and work closely with a tax professional to identify and claim all eligible deductions.
By implementing these tax planning strategies, you can potentially reduce your overall tax liability and improve the financial performance of your rental property investment.
Conclusion
Rental income in Australia is a significant part of many individuals' and investors' financial portfolios. Understanding the tax implications and obligations associated with rental properties is crucial to ensure compliance and maximize your returns.
By familiarizing yourself with the concepts of taxable rental income, allowable deductions, and tax planning strategies, you can navigate the rental property tax landscape with confidence. Remember to keep meticulous records, consult with tax professionals, and stay up-to-date with the latest tax laws and regulations.
Investing in rental properties can be a rewarding endeavor, and by proactively managing your tax obligations, you can optimize the financial benefits and enjoy the long-term growth potential of your real estate investments.
Declare all rental income received: regular rent, advance rent, rent in kind, insurance payouts for lost rent, and bond money kept for unpaid rent. Gross rent before expenses is included in assessable income. The rental property schedule of the tax return captures income and expenses separately from other income.
Deductible expenses include council rates, water charges, land tax, insurance, property agent fees, repairs and maintenance, loan interest on funds borrowed for the property, advertising for tenants, and depreciation on eligible assets. Capital improvements are depreciated over time; borrowing costs are spread over five years or the loan term, whichever is shorter.
Negative gearing occurs when rental expenses exceed rental income. The net rental loss is deducted from your other assessable income (such as wages), reducing total taxable income and therefore tax payable. It is most beneficial for taxpayers in higher marginal brackets and must be reported accurately on the rental property schedule.
Yes. The sale triggers a CGT event. The gain is proceeds less cost base (purchase price, stamp duty, legal fees, and improvement costs). If owned for more than 12 months, apply the 50% CGT discount before adding the gain to assessable income. Previously claimed capital works deductions reduce the cost base and increase the eventual gain.
Yes, if the property is genuinely available for rent at a market rate. Expenses during a vacancy are deductible while the property is advertised. If the property is not genuinely available — reserved for personal use or listed above market rent — deductions may be denied or apportioned for the vacant period.
Outsourcing Strategies for Accountants in Australia: Boosting Profitability and Efficiency
Introduction
As an accountant in Australia, you're faced with the constant challenge of balancing your workload, meeting client demands, and maintaining profitability. In today's fast-paced business landscape, one strategy that is gaining significant traction among forward-thinking accounting firms is the strategic use of outsourcing. By leveraging the power of outsourcing, accountants in Australia can not only streamline their operations and reduce costs, but also unlock new opportunities for growth and revenue generation.
- Outsourcing Strategies for Accountants in Australia: Boosting Profitability and Efficiency
- Introduction
- The Rise of Outsourcing in the Accounting Profession
- Key Areas of Outsourcing for Accountants in Australia
- Strategies for Successful Outsourcing in the Accounting Profession
In this comprehensive blog post, we'll explore the numerous ways in which accountants in Australia can leverage outsourcing to enhance their bottom line and deliver exceptional service to their clients. From streamlining administrative tasks to tapping into specialized expertise, we'll dive into the key benefits of outsourcing and provide practical insights on how to implement these strategies effectively within your accounting practice.
When you receive a price from us, we never outsource any of your work and none of your personal details leave our office, we have never in the past and never in the future, outsource any of our client's work, as we are a boutique firm that works with the right client, not every client for just money.
You always have to ask why other accounting firms are so cheap?
The Rise of Outsourcing in the Accounting Profession
The accounting industry in Australia has witnessed a significant shift in recent years, with the increasing adoption of outsourcing as a strategic business tool. Several factors have contributed to the growing popularity of outsourcing among accountants:
- Cost Savings: Outsourcing certain tasks and functions to third-party providers can lead to substantial cost savings for accounting firms. By leveraging the economies of scale and specialized expertise of outsourcing partners, accountants can reduce their overhead expenses, such as employee salaries, office space, and equipment costs.
- Access to Specialized Expertise: Outsourcing allows accounting firms to tap into a pool of specialized expertise that may not be readily available within their in-house team. This can be particularly beneficial for tasks that require specialized skills, such as tax planning, auditing, or forensic accounting.
- Improved Efficiency and Productivity: By outsourcing repetitive, time-consuming tasks, accountants can free up their in-house team to focus on more strategic and value-adding activities. This can lead to increased productivity, faster turnaround times, and enhanced client satisfaction.
- Scalability and Flexibility: Outsourcing provides accounting firms with the ability to scale their operations up or down as needed, allowing them to adapt to fluctuations in workload and client demands. This flexibility can be particularly beneficial during peak seasons or when handling large-scale projects.
- Compliance and Risk Management: Outsourcing certain functions, such as payroll processing or regulatory reporting, can help accounting firms ensure compliance with relevant laws and regulations, reducing the risk of penalties or legal issues.
Key Areas of Outsourcing for Accountants in Australia
Accountants in Australia have a wide range of outsourcing opportunities to explore, each with its own set of benefits and considerations. Let's take a closer look at some of the most popular areas of outsourcing for the accounting profession:
1. Bookkeeping and Accounting Services
One of the most common areas of outsourcing for accountants is the outsourcing of bookkeeping and accounting services. This can include tasks such as:
- Data entry and record-keeping
- Accounts payable and receivable management
- Bank reconciliations
- Payroll processing
- Financial reporting and analysis
By outsourcing these routines, high-volume tasks, accounting firms can free up their in-house team to focus on more strategic and advisory services, ultimately enhancing their profitability and client value.
2. Tax Preparation and Compliance
Tax preparation and compliance can be a complex and time-consuming process, especially with the ever-changing tax laws and regulations in Australia. Outsourcing these services to specialized providers can offer several benefits, including:
- Ensuring accurate and timely tax filings
- Accessing expertise in complex tax planning and optimization
- Reducing the administrative burden on the accounting firm
- Staying up-to-date with the latest tax laws and regulations
This can be particularly beneficial for accounting firms that serve a diverse client base or specialize in specific industries with unique tax requirements.
3. Audit and Assurance Services
Conducting audits and providing assurance services can be resource-intensive for accounting firms, especially when dealing with complex or specialized audits. Outsourcing these services to external providers can help accounting firms:
- Tap into specialized expertise and industry-specific knowledge
- Improve audit quality and consistency
- Enhance the efficiency and timeliness of the audit process
- Reduce the need for in-house audit team expansion
By outsourcing audit and assurance services, accounting firms can focus on their core competencies and deliver high-quality services to their clients.
4. Advisory and Consulting Services
As the accounting profession evolves, many firms are expanding their service offerings to include advisory and consulting services. These may include:
- Strategic planning and business advisory
- Financial modeling and forecasting
- Mergers and acquisitions support
- Forensic accounting and litigation support
Outsourcing these specialized services can provide accounting firms with access to subject matter experts, industry-specific knowledge, and the latest tools and technologies, enabling them to offer a broader range of value-added services to their clients.
5. Practice Management and Administrative Support
Accounting firms often face the challenge of managing various administrative tasks, such as:
- Human resources and payroll
- IT support and infrastructure management
- Marketing and business development
- Client relationship management
Outsourcing these non-core functions can help accounting firms streamline their operations, reduce overhead costs, and ensure that their in-house team can focus on delivering exceptional client service.
Strategies for Successful Outsourcing in the Accounting Profession
To maximize the benefits of outsourcing and ensure a seamless integration within your accounting practice, it's essential to develop a well-structured outsourcing strategy. Here are some key strategies to consider:
1. Identify and Prioritize Outsourcing Opportunities
Start by conducting a thorough analysis of your accounting firm's operations and identifying the tasks, functions, or services that can be effectively outsourced. Consider factors such as workload, expertise requirements, and the potential for cost savings or efficiency gains.
2. Evaluate and Select Outsourcing Partners Carefully
Research and evaluate potential outsourcing providers to ensure they align with your firm's values, capabilities, and quality standards. Look for providers with industry-specific expertise, a proven track record, and a commitment to data security and compliance.
3. Establish Clear Communication and Collaboration Processes
Effective communication and collaboration are crucial for the success of any outsourcing arrangement. Develop clear protocols for information sharing, task management, and performance monitoring to ensure seamless integration between your in-house team and the outsourcing provider.
4. Implement Robust Quality Assurance and Control Measures
Establish comprehensive quality assurance and control measures to ensure the accuracy, timeliness, and consistency of the outsourced work. This may include regular audits, performance reviews, and feedback mechanisms to identify and address any issues.
5. Continuously Evaluate and Optimize the Outsourcing Arrangement
Regularly review the performance and effectiveness of your outsourcing arrangement, and make adjustments as needed. This may involve renegotiating contracts, expanding or reducing the scope of services, or exploring new outsourcing opportunities to drive continuous improvement.
The Financial Benefits of Outsourcing for Accountants in Australia
The financial benefits of outsourcing for accountants in Australia are substantial and can have a significant impact on the overall profitability and growth of an accounting firm. Let's explore some of the key financial advantages:
1. Cost Savings
As mentioned earlier, outsourcing can lead to significant cost savings for accounting firms. By outsourcing tasks and functions to providers with economies of scale and specialized expertise, firms can reduce their overhead expenses, such as employee salaries, office space, and equipment costs.
2. Improved Productivity and Efficiency
By outsourcing repetitive, time-consuming tasks, accounting firms can free up their in-house team to focus on more strategic and value-adding activities. This can lead to increased productivity, faster turnaround times, and enhanced client satisfaction, ultimately driving higher revenues and profitability.
3. Scalability and Flexibility
Outsourcing provides accounting firms with the ability to scale their operations up or down as needed, allowing them to adapt to fluctuations in workload and client demands. This flexibility can be particularly beneficial during peak seasons or when handling large-scale projects, ensuring that the firm can meet client needs without incurring the costs of permanent staffing increases.
4. Access to Specialized Expertise
Outsourcing allows accounting firms to tap into a pool of specialized expertise that may not be readily available within their in-house team. This can be particularly beneficial for tasks that require specialized skills, such as tax planning, auditing, or forensic accounting, enabling the firm to offer a broader range of services and command higher fees.
5. Improved Cash Flow Management
By outsourcing certain functions, such as accounts payable and receivable management, accounting firms can improve their cash flow and working capital management. This can provide them with the financial flexibility to invest in growth initiatives, such as technology upgrades or business expansion.
Case Study: How an Accounting Firm in Australia Leveraged Outsourcing to Boost Profitability
To illustrate the real-world impact of outsourcing in the accounting profession, let's consider the case of a mid-sized accounting firm based in Melbourne, Australia.
The firm, which specializes in serving small and medium-sized businesses, was facing increasing workloads and challenges in keeping up with client demands. The partners recognized that they needed to find a way to streamline their operations and free up their in-house team to focus on more strategic and value-adding services.
After carefully evaluating their options, the firm decided to outsource their bookkeeping and accounting services to a specialized provider based in the Philippines. The outsourcing arrangement allowed the firm to:
- Reduce Overhead Costs: By outsourcing the bookkeeping and accounting functions, the firm was able to reduce its employee headcount and office space requirements, resulting in significant cost savings.
- Improve Efficiency and Productivity: The outsourcing provider's specialized expertise and process-driven approach enabled the firm to streamline its workflows and reduce the time spent on routine tasks. This allowed the in-house team to focus on higher-value services, such as tax planning, business advisory, and client relationship management.
- Enhance Service Quality: The outsourcing provider's robust quality assurance measures and commitment to compliance ensured that the firm's clients received accurate and timely financial reporting, leading to increased client satisfaction and retention.
- Increase Profitability: The combination of cost savings, improved efficiency, and enhanced service quality enabled the firm to increase its profit margins and invest in growth initiatives, such as technology upgrades and the expansion of its advisory services.
Within the first year of implementing the outsourcing strategy, the firm experienced a 20% increase in profitability, and the partners were able to reinvest a portion of these gains into the firm's development and the expansion of its service offerings.
Conclusion: Embracing Outsourcing for Sustainable Growth
As the accounting profession in Australia continues to evolve, the strategic use of outsourcing has emerged as a powerful tool for accounting firms to enhance their profitability, improve efficiency, and deliver exceptional service to their clients.
By leveraging the expertise and resources of specialized providers, accountants can streamline their operations, reduce costs, and free up their in-house team to focus on higher-value, revenue-generating activities. Whether it's outsourcing bookkeeping and accounting services, tax preparation, audit and assurance, or practice management functions, the financial benefits of outsourcing can be significant and transformative for accounting firms of all sizes.
As you embark on your own outsourcing journey, remember to approach it with a well-structured strategy, carefully evaluate potential partners, and continuously optimize your outsourcing arrangement to ensure long-term success. By embracing the power of outsourcing, you can position your accounting firm for sustainable growth and profitability in the years to come.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
10 Effective Strategies to Accelerate Business Growth
- Goal 1: Define Your Vision and Set Clear Goals
- Goal 2: Know Your Target Audience
- Goal 3: Develop a Strong Brand Identity
- Goal 4: Leverage the Power of Digital Marketing
- Goal 5: Nurture Customer Relationships
Growing a business is a challenging endeavor that requires careful planning, strategic thinking, and relentless execution. Whether you are a startup or an established company, finding ways to expand your business is crucial for long-term success. In this blog post, we will explore top ten proven strategies that can help you accelerate and create a successful business.
Goal 1: Define Your Vision and Set Clear Goals
To grow your business successfully, it's essential to have a clear vision of what you want to achieve and set specific goals. Start by defining your long-term vision and then break it down into smaller, actionable goals. Make sure these goals are measurable, realistic, and aligned with your overall business strategy. By having a clear roadmap, you can focus your efforts and track your progress along the way.
Goal 2: Know Your Target Audience
Understanding your target audience is key to growing your business effectively. Conduct market research to identify who your ideal customers are, what their needs and pain points are, and how your product or service can solve their problems. By knowing your target audience, you can tailor your marketing messages, develop products that meet their needs, and build stronger relationships with your customers.
Goal 3: Develop a Strong Brand Identity
Building a strong brand identity is crucial for business growth. Your brand represents the essence of your business and what it stands for. Invest time and effort in creating a compelling brand story, logo, tagline, and visual assets that resonate with your target audience. Consistently communicate your brand values and unique selling propositions across all marketing channels to establish brand loyalty and differentiate yourself from competitors.
Goal 4: Leverage the Power of Digital Marketing
In today's digital age, having a strong online presence is vital for business growth. Implement a comprehensive digital marketing strategy that includes search engine optimization (SEO), content marketing, social media marketing, email marketing, and paid advertising. These channels allow you to reach a wider audience, generate leads, increase brand awareness, and drive conversions.
Goal 5: Nurture Customer Relationships
Building strong relationships with your customers is crucial for sustainable business growth. Focus on providing exceptional customer service, personalized experiences, and ongoing communication. Implement customer relationship management (CRM) systems to track customer interactions, gather feedback, and identify opportunities for upselling or cross-selling. By nurturing customer relationships, you can increase customer satisfaction, loyalty, and advocacy.
10 ways to make a successful business
Goal 6: Expand Your Product or Service Offerings
To fuel business growth, consider expanding your product or service offerings. Analyze market trends and customer demands to identify new opportunities. Conduct market research to validate potential new offerings before investing resources into development. By diversifying your offerings, you can attract new customers, increase revenue streams, and stay ahead of competitors.
Goal 7: Build Strategic Partnerships
Collaborating with other businesses can be mutually beneficial and accelerate your business growth. Seek out strategic partnerships with complementary companies in your industry. Look for opportunities to co-create products or services, share resources, cross-promote each other's offerings, or tap into new markets together. Strategic partnerships can help you reach new audiences, gain industry expertise, and expand your customer base.
Goal 8: Invest in Employee Development
Your employees are the backbone of your business. Investing in their development not only improves their skills but also contributes to overall business growth. Provide training programs, mentorship opportunities, and ongoing professional development to empower your employees. Encourage a culture of innovation and continuous learning within your organization to drive creativity and productivity.
Goal 9: Optimize Operational Efficiency
10 ways to make a successful business
Streamlining your operations can significantly impact your business growth. Identify areas where you can improve efficiency and reduce costs. Automate repetitive tasks, implement scalable systems and processes, and leverage technology solutions to increase productivity. By optimizing operational efficiency, you can free up resources to invest in growth initiatives and enhance the overall customer experience.
Goal 10: Monitor Key Performance Indicators (KPIs)
To track the progress of your business growth strategies, it's crucial to monitor key performance indicators (KPIs). Identify the metrics that align with your goals and regularly analyze them to gain insights into your business performance. This data-driven approach allows you to make informed decisions, identify areas for improvement, and make necessary adjustments to stay on track towards achieving your growth objectives.
Conclusion:
Growing a business requires a strategic approach and a commitment to continuous improvement. By implementing these ten effective strategies - defining your vision and goals, understanding your target audience, building a strong brand identity, leveraging digital marketing, nurturing customer relationships, expanding product offerings, building strategic partnerships, investing in employee development, optimizing operational efficiency, and monitoring KPIs - you can accelerate your business growth and pave the way for long-term success. Remember that growth takes time and persistence, so stay focused on your goals and adapt as needed along the way. If you need assistance please call us.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
Maximizing Your Financial Potential in Australia
The start of a new year is the perfect time to reflect on our financial goals and make resolutions to improve our financial situation. For Australians, understanding and optimizing their tax obligations is an essential aspect of maximizing their financial potential. In this blog post, we will explore some key tax resolutions that can help Australians navigate the tax landscape more effectively, minimize their tax liabilities, and ultimately achieve financial success with our tax tips and tricks.
- Maximizing Your Financial Potential in Australia
- Understanding Australian Tax System
- Track Your Expenses and Receipts
- Maximize Your Superannuation Contributions
- Take Advantage of Tax Deductions
Understanding Australian Tax System
Before diving into specific tax resolutions, it is crucial to have a solid understanding of the Australian tax system. Australia operates on a self-assessment tax system, where individuals are responsible for reporting their income and claiming deductions accurately. The Australian Taxation Office (ATO) is the governing body that oversees tax compliance and administers various tax laws. Familiarizing yourself with the different types of taxes in Australia, such as income tax, goods and services tax (GST), and capital gains tax (CGT), will set the foundation for effective tax planning.
Track Your Expenses and Receipts
One of the most effective ways to minimize your tax liabilities is by tracking your expenses and keeping receipts throughout the year. By maintaining detailed records of your deductible expenses, you can claim them when filing your tax return. Deductible expenses may include work-related expenses, self-education expenses, medical expenses, and charitable donations. Utilize technology tools like expense tracking apps or spreadsheets to simplify this process. Starting this habit early in the year will save you time and stress when tax season arrives.
Maximize Your Superannuation Contributions
Superannuation is a retirement savings scheme in Australia, and contributing to it can provide significant tax advantages. As part of your new year's tax resolutions, consider maximizing your superannuation contributions. Contribute up to the annual concessional contribution limit, which is currently $25,000 for individuals under the age of 67 (subject to change). By doing so, you can reduce your taxable income while simultaneously building your retirement nest egg.
Take Advantage of Tax Deductions
To optimize your tax position, it is vital to be aware of the various tax deductions you may be eligible for. Common deductions include work-related expenses (e.g., uniforms, home office expenses), investment property expenses (e.g., mortgage interest, repairs), and self-education expenses (e.g., courses, workshops). Ensure you keep accurate records and consult with a tax professional or refer to the ATO website to determine which deductions apply to your specific situation. By claiming all eligible deductions, you can reduce your taxable income and potentially receive a higher tax refund.
Stay Updated with Tax Law Changes
Tax laws and regulations are subject to change frequently. As part of your commitment to enhancing your financial knowledge, make it a resolution to stay updated with any tax law changes throughout the year. Subscribing to newsletters or following reputable financial news sources will keep you informed about any legislative updates or new tax benefits introduced by the government. Being proactive in understanding these changes will allow you to adapt your tax strategies accordingly.
Seek Professional Help When Needed
While it's essential to educate yourself about taxes, seeking professional help from a qualified accountant or tax advisor can be incredibly valuable. Tax professionals have in-depth knowledge of the Australian tax system and can provide personalized advice based on your unique circumstances. They can help you identify potential savings opportunities, ensure compliance with tax laws, and navigate complex tax matters. Consider engaging a trusted professional to assist you in achieving your financial goals in the coming year.
Plan for Capital Gains Tax (CGT)
Capital gains tax (CGT) is a tax levied on the profit made from selling assets such as real estate, shares, or collectibles. As part of your New Year's resolutions, take the time to review your investment portfolio and assess any potential CGT implications. By strategically planning asset sales or considering options like holding assets for more than 12 months (which may provide discounts on CGT), you can minimize the impact of this tax on your overall financial position.
Consider Income Splitting Strategies
For families or couples with multiple income earners, exploring income-splitting strategies can be beneficial from a tax perspective. By redistributing income earned between family members who fall into different tax brackets, you can potentially reduce the overall family tax liability. However, it is crucial to note that income splitting should be done within the boundaries of Australian tax laws. Consult with a taxation professional to understand the rules and limitations surrounding this strategy.
Review Your Salary Packaging Options
Salary packaging refers to an arrangement between an employer and an employee, allowing them to receive certain benefits or allowances as part of their remuneration package. These benefits can include items like cars, laptops, or even childcare subsidies. As part of your New Year's resolutions, review your salary packaging options and assess whether there are any additional benefits you can take advantage of that align with your lifestyle and financial goals. Salary packaging can result in significant tax savings if structured correctly.
Stay Organized for the Next Tax Season
Lastly, as you embark on a new year with fresh financial goals, commit to staying organized throughout the year for the next tax season. Maintain a dedicated folder or digital file where you store all relevant financial documents, receipts, and statements as they become available. Regularly update this folder to ensure all records are easily accessible when it is time to file your tax return. By adopting this habit, you will streamline the process and reduce stress when dealing with taxes.
Conclusion
As we welcome another year, let us embrace the opportunity to improve our financial well-being through strategic tax planning. By understanding the Australian tax system, tracking expenses diligently, maximizing superannuation contributions, leveraging deductions, staying informed about tax law changes, seeking professional help when needed, planning for CGT, considering income splitting strategies, reviewing salary packaging options, and staying organized throughout the year – we can all work towards maximizing our financial potential in Australia. Remember that each individual's financial situation is unique; therefore, consult with a qualified professional before implementing any specific strategies mentioned in this blog post. Here's to a successful year of achieving our financial goals!
Yes, if you are under 75 and meet the work test (if aged 67–74). Lodge a notice of intent to claim with your fund before the earlier of the tax return due date or the lodgement date. Once the fund acknowledges the notice, the contribution becomes concessional and is taxed at 15% inside the fund.
The concessional contributions cap for 2025-26 is $30,000. This covers employer SG contributions, salary sacrifice, and personal deductible contributions combined. Contributions above the cap are included in assessable income at your marginal rate, with a 15% tax offset for the tax already paid inside the fund.
The Super Guarantee rate for 2025-26 is 11.5%, rising to 12% from 1 July 2025. Employers must contribute this percentage of each eligible employee's ordinary time earnings to a complying super fund at least quarterly. Late or missing payments trigger the Super Guarantee Charge, which includes interest and is not tax deductible.
Salary sacrifice contributions come from pre-tax income and are taxed at 15% inside super rather than at your marginal rate (up to 47%). The difference is your tax saving. A taxpayer in the 37% bracket saves 22 cents per dollar sacrificed, subject to the $30,000 concessional cap.
Yes, if your total super balance was below $500,000 on 30 June of the prior year. Unused cap amounts from the previous five years can be carried forward and used in a higher-income year. The oldest unused amounts are applied first, allowing catch-up contributions that significantly reduce tax for eligible individuals.
Starting a business can be an exciting and rewarding venture, but it also comes with its fair share of challenges. To increase your chances of success, it is crucial to have a solid strategy in place. In this blog post, we will discuss various strategies for creating a successful business. From defining your target audience to developing a strong marketing plan, we will cover all the essential aspects of building a thriving business. the following are business tips for success.
- Section 1: Identify Your Niche and Target Audience
- Section 2: Develop a Comprehensive Business Plan
- Section 3: Secure Adequate Funding
- Section 4: Build a Strong Online Presence
- Section 5: Focus on Exceptional Customer Service
Section 1: Identify Your Niche and Target Audience
One of the key components of creating a successful business is identifying your niche market and target audience. This involves conducting thorough market research to understand the needs and preferences of your potential customers. By understanding your target audience, you can tailor your products or services to meet their specific needs, giving you a competitive edge in the market.
To identify your niche, consider the following steps:
- Research the market: Study the existing businesses in your industry and identify any gaps or opportunities that you can fill.
- Define your unique selling proposition (USP): Determine what sets your business apart from competitors and why customers should choose your products or services.
- Conduct customer surveys: Engage with potential customers to gather feedback and gain insights about their preferences and pain points.
- Create buyer personas: Develop detailed profiles of your ideal customers, including demographics, interests, and motivations.
Once you have identified your niche and target audience, you can create customized marketing strategies to effectively reach and engage with them.
Section 2: Develop a Comprehensive Business Plan
A well-crafted business plan serves as a roadmap for success. It outlines your goals, strategies, financial projections, and operational details. Here are some essential elements to include in your business plan:
- Executive summary: Provide an overview of your business, including its mission, vision, and objectives.
- Market analysis: Describe the industry landscape, competition, and target market.
- Company description: Detail the structure of your business, management team, and legal structure.
- Products or services: Explain what you offer and how it addresses the needs of your target audience.
- Marketing and sales strategy: Outline your marketing approach, pricing strategy, and distribution channels.
- Financial projections: Include projected revenue, expenses, and cash flow statements.
- Operations plan: Detail the day-to-day operations of your business, including production, logistics, and customer service.
By developing a comprehensive business plan, you will have a clear roadmap to guide your decision-making process and secure funding if needed.
Section 3: Secure Adequate Funding
Finances play a crucial role in launching and growing a business. Securing adequate funding ensures that you have the necessary resources to cover startup costs, operational expenses, and future growth. Here are some strategies to consider:
- Self-funding: Use personal savings or assets to finance your business.
- Friends and family: Seek investments or loans from friends and family who believe in your vision.
- Business loans: Explore options for small business loans from banks or financial institutions.
- Crowdfunding: Leverage online platforms to raise funds from a large pool of individual investors.
- Investors: Pitch your business idea to potential investors who may be interested in supporting your venture in exchange for equity.
Remember to prepare a detailed financial plan that clearly outlines how the funds will be utilized and how you plan to generate revenue to repay any loans or investments.
Section 4: Build a Strong Online Presence
In today's digital age, having a strong online presence is essential for any business. This allows you to reach a wider audience, build brand awareness, and drive sales. Here are some strategies to build a strong online presence:
- Create a professional website: Design an attractive and user-friendly website that showcases your products or services.
- Search engine optimization (SEO): Optimize your website with relevant keywords to improve its visibility on search engines.
- Content marketing: Produce high-quality content (blogs, articles, videos) that provides value to your target audience.
- Social media marketing: Utilize popular social media platforms to engage with potential customers and promote your brand.
- Email marketing: Build an email list and send regular newsletters or promotional offers to stay connected with your audience.
By implementing these online marketing strategies, you can effectively reach your target audience and establish a strong brand presence in the digital landscape.
Section 5: Focus on Exceptional Customer Service
Customer satisfaction plays a vital role in the success of any business. By providing exceptional customer service, you can build trust, loyalty, and positive word-of-mouth referrals. Here are some tips for delivering outstanding customer service:
- Train your employees: Equip your staff with the necessary skills and knowledge to provide excellent customer service.
- Respond promptly: Address customer inquiries or concerns promptly to show that you value their feedback.
- Personalize interactions: Make customers feel valued by addressing them by name and providing personalized recommendations based on their preferences.
- Go above and beyond: Exceed customer expectations by offering additional assistance or surprises to enhance their experience.
- Gather feedback: Regularly collect feedback from customers through surveys or reviews to identify areas for improvement.
Remember that happy customers are more likely to become repeat customers and refer others to your business.
Section 6: Continuously Innovate and Adapt
The business landscape is constantly evolving, so it is essential to stay ahead of the curve by continuously innovating and adapting to changing market trends. Here are some strategies to foster innovation:
- Stay updated with industry trends: Keep abreast of the latest developments in your industry through industry publications, conferences, and networking events.
- Encourage creativity within your team: Foster an environment that encourages employees to share innovative ideas and reward them for their contributions.
- Embrace technology: Explore new technologies that can streamline operations, improve efficiency, or enhance customer experiences.
- Monitor competition: Keep an eye on competitors' strategies and identify areas where you can differentiate yourself or improve upon existing offerings.
- Seek customer feedback: Actively listen to customer feedback and incorporate their suggestions into product or service improvements.
By embracing innovation and adapting to changing market dynamics, you can position your business for long-term success.
Conclusion
Creating a successful business requires careful planning, strategic thinking, and continuous effort. By following the strategies outlined in this blog post - identifying your niche market, developing a comprehensive business plan, securing adequate funding, building a strong online presence, prioritizing exceptional customer service, and fostering innovation - you can increase your chances of building a thriving business. Remember that success doesn't happen overnight; it requires dedication, perseverance, and a willingness to learn from both successes and failures along the way.
If you want us to check your business plan please contact us here
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.