
1. Xero: The All-in-One for Small Business
For many Australian small businesses already using Xero for their accounting, its integrated payroll solution is the most logical and efficient choice. It eliminates the need for third-party software and complex data syncing, creating a single source of truth for your finances. This unified approach is where Xero truly shines, making it a standout option in the crowded market for the best payroll software Australia offers. The platform handles all critical compliance tasks with ease. It is fully compliant with Single Touch Payroll (STP) Phase 2 reporting and automates superannuation payments through its Auto Super feature, which significantly reduces the risk of non-compliance and saves administrative time. Employees gain autonomy through the Xero Me mobile app, where they can independently access payslips, manage timesheets, and request leave, freeing up managers for more strategic work.Pricing and Plans
Xero Payroll is not a standalone product; it's included in Xero's business subscription plans.- Starter Plan: Payroll for up to 2 people.
- Standard Plan: Payroll for up to 5 people.
- Premium Plan: Payroll for up to 10 people.
- Ultimate Plan: Payroll for up to 200 people.
Key Considerations
| Pros | Cons |
|---|---|
| ✅ Seamless integration with Xero accounting | ❌ Not available as a standalone product |
| ✅ Excellent employee self-service via Xero Me app | ❌ Can become expensive as you add employees |
| ✅ Strong compliance features (STP & Auto Super) | ❌ Advanced award interpretation can be limited |
2. MYOB Business – Payroll (including Payroll Only)
As one of Australia's most established accounting software providers, MYOB offers a robust and reliable payroll solution tailored for local businesses. Its standout feature is the affordable "Payroll Only" plan, making it an excellent entry point for very small businesses that don't need a full accounting suite but still require compliant, professional payroll processing. This flexibility makes MYOB a strong contender for the title of best payroll software Australia can offer, especially for those just starting out.
Pricing and Plans
MYOB offers a dedicated payroll plan and includes payroll in its broader business accounting plans.- Payroll Only: For up to 4 employees.
- Business Lite: Includes payroll for 1 employee (add-ons available).
- Business Pro: Includes payroll for 1 employee (add-ons available).
- Business AccountRight Plus: Includes payroll for unlimited employees.
Key Considerations
| Pros | Cons |
|---|---|
| ✅ Affordable entry option (Payroll Only) for up to 4 employees | ❌ Employee limits on lower-tier plans can be restrictive |
| ✅ Deep Australian compliance knowledge and support | ❌ Broader HR and award automation may require add-ons |
| ✅ Scales into a full accounting solution as you grow | ❌ The interface can feel less modern than some rivals |
3. QuickBooks Online Australia + Payroll
For businesses committed to the Intuit ecosystem, QuickBooks Online Payroll offers a tightly integrated and familiar solution. Similar to its main rival, its strength lies in creating a unified financial management system where accounting and payroll data coexist seamlessly. This integration streamlines processes like bank reconciliation and simplifies understanding the financial impact of your payroll, making it a strong contender for the best payroll software Australia can offer its small businesses.
Pricing and Plans
QuickBooks Payroll is an add-on to a QuickBooks Online subscription, with pricing based on the number of employees.- Payroll Core: For up to 10 employees.
- Payroll Premium: For an unlimited number of employees.
Key Considerations
| Pros | Cons |
|---|---|
| ✅ Seamless integration with QBO accounting | ❌ Not a standalone product; requires a QBO subscription |
| ✅ Simple per-employee pricing model | ❌ Per-employee cost can escalate as headcount grows |
| ✅ Easy to set up for existing QuickBooks users | ❌ Feature set can depend on the selected payroll tier |
4. Employment Hero Payroll (formerly KeyPay)
For Australian businesses grappling with complex Modern Awards, Employment Hero Payroll offers a powerful, purpose-built solution. Built on the robust KeyPay engine, it excels at automating complex calculations, interpreting award conditions, and managing rostering and timesheets in one unified system. This focus on industrial relations compliance makes it a top contender for the best payroll software Australia has for industries like hospitality, retail, and healthcare.
Pricing and Plans
Employment Hero Payroll is available as a standalone product or as part of a broader HR platform. Plans are typically priced per employee, per month, often with a monthly minimum spend.- Standard Payroll: Core payroll features, STP reporting, and employee self-service.
- Premium Payroll: Includes advanced features like rostering, timesheets, and award interpretation.
- Platinum HR: A full suite combining HR management with Premium payroll functionalities.
- Implementation packages are also available for an additional cost to assist with setup.
Key Considerations
| Pros | Cons |
|---|---|
| ✅ Powerful Australian award rules editor and automation | ❌ Per-employee pricing and monthly minimums apply |
| ✅ End-to-end people platform (HR + payroll) | ❌ Implementation help may be advisable for complex awards (extra cost) |
| ✅ Strong partner program for accountants and bookkeepers | ❌ Can be more complex than basic payroll-only systems |
5. Reckon Payroll: Accessible and Mobile-First
Reckon Payroll offers a streamlined and highly accessible solution aimed squarely at Australian small businesses, particularly those who value flexibility. Its key differentiator is the ability to manage and run payroll entirely from a mobile app, providing unparalleled convenience for business owners on the go. This mobile-first approach, combined with competitive entry-level pricing, makes it a strong contender for micro-businesses looking for one of the best payroll software Australia has to offer without a hefty price tag.
Pricing and Plans
Reckon's payroll pricing is simple and tiered based on employee numbers, with separate app and web-based products.- Payroll App: Free for 1 employee. Paid tiers for up to 4 employees, and another for up to 10 employees.
- Reckon One (Web): Payroll is an optional module within their accounting software. A base subscription is required, with payroll costing an additional monthly fee per employee.
Key Considerations
| Pros | Cons |
|---|---|
| ✅ Very competitive pricing for micro-businesses | ❌ Feature depth is less than comprehensive HR suites |
| ✅ Excellent mobile app for running payroll anywhere | ❌ Pricing can be confusing between web and app versions |
| ✅ Strong local support and Australian data hosting | ❌ Less suited for complex award interpretation needs |
6. Payroller: The Simple Choice for Micro Businesses
Payroller is designed specifically for sole traders and small teams who need a no-fuss, compliant payroll solution without a steep learning curve. As an ATO-registered and STP-enabled platform, it focuses on making the setup process incredibly fast, which is a major advantage for business owners handling payroll for the first time. Its core appeal lies in its simplicity and accessibility, offering a streamlined experience through both web and mobile apps. For micro-businesses seeking one of the most straightforward options for the best payroll software Australia has to offer, Payroller strips away complexity. It handles essential tasks like STP Phase 2 reporting, superannuation calculations, leave management, and payslip generation. Employees can also access their own information through a dedicated app, reducing administrative queries. While its core offering is lean, optional add-ons for timesheets and rosters provide a pathway for growth.
Pricing and Plans
Payroller uses a simple, pay-per-employee model, often with a free option for a single employee, making it highly accessible.- Payroller Free: A free plan is typically available for businesses with just one employee.
- Payroller Subscription: A low per-employee, per-month fee applies for businesses with more than one employee. Optional add-ons for features like timesheets and rostering are available for an additional cost. A minimum monthly spend often applies to the paid subscription.
Key Considerations
| Pros | Cons |
|---|---|
| ✅ Very low per-employee entry price | ❌ Minimum monthly spend can apply |
| ✅ Quick setup, ideal for first-time payroll users | ❌ Less suited to complex awards without add-ons |
| ✅ Mobile app for employers and employees | ❌ May be too basic for rapidly scaling businesses |
7. CloudPayroll: Flexible Service and Transparent Pricing
CloudPayroll carves out a unique space in the Australian market with its highly flexible service model and transparent, pay-run-based pricing. Instead of forcing businesses into a one-size-fits-all software subscription, it allows companies to choose their level of involvement, from complete do-it-yourself (DIY) payroll processing to fully outsourced data entry and superannuation management. This makes it a compelling option for businesses that want more control over their service level.
Pricing and Plans
CloudPayroll uses a pay-as-you-go model based on the number of employees per pay run, with a public calculator on its website for precise quotes.- Pricing: A base fee applies per pay run, plus a small additional fee for each employee included in that run.
- Add-ons: Optional services like outsourced data entry or managed superannuation come with their own clear, additional costs.
- Fees: Note that setup fees may apply, and GST and bank transaction fees are excluded from initial quotes.
Key Considerations
| Pros | Cons |
|---|---|
| ✅ Transparent per-pay-run pricing model | ❌ May not be cost-effective for very frequent pay runs |
| ✅ Flexible service options (DIY or outsourced) | ❌ Setup fees can apply, adding to initial cost |
| ✅ Strong Australian compliance and reporting features | ❌ Interface is more functional than modern |
8. ADP Australia (ADP Payline): Scalable Solutions for Growing Businesses
ADP is a global powerhouse in payroll and HR, and its Australian offering, ADP Payline, brings that extensive experience to businesses managing between 1 and 199 employees. It stands out by offering a clear growth pathway, allowing a company to start with a robust software solution and later transition to a fully managed or outsourced payroll service as its complexity increases. This scalability makes it a strategic choice for businesses planning for future expansion.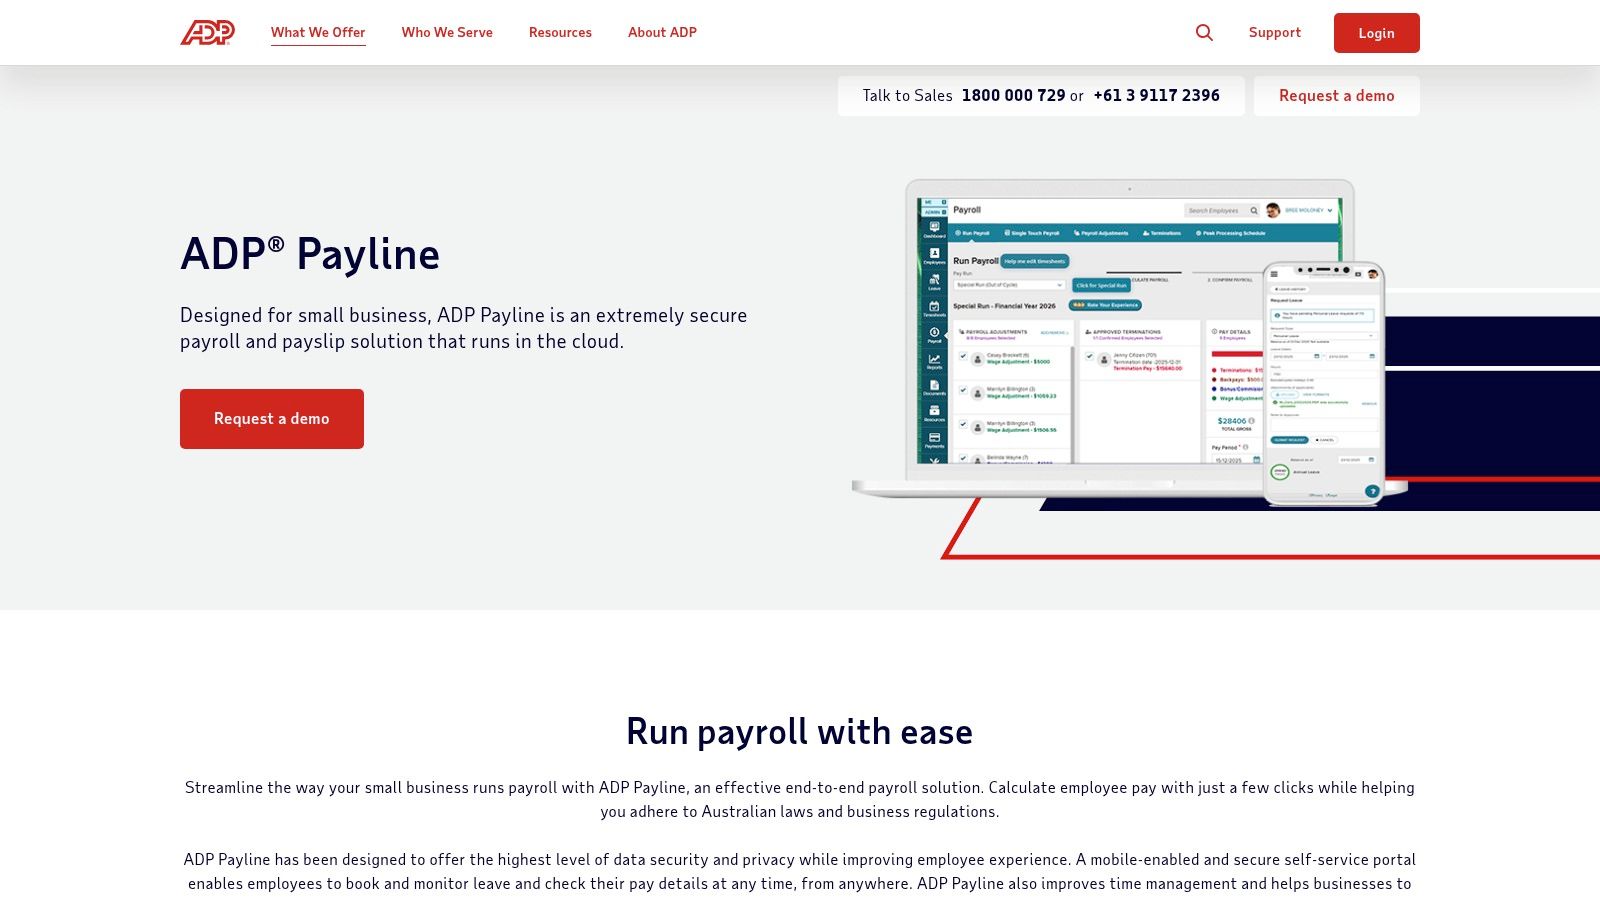
Pricing and Plans
ADP Payline does not offer standardised public pricing. Each plan is tailored to the specific needs of the business, requiring a direct quote.- ADP Payline: Customised pricing based on employee numbers and required service levels.
- Managed Payroll & HR Services: Broader, fully outsourced solutions are also available via custom quote for larger or more complex organisations.
Key Considerations
| Pros | Cons |
|---|---|
| ✅ Scales from software-only to fully outsourced payroll | ❌ Pricing is only available via a custom quote |
| ✅ Strong global expertise and local Australian support | ❌ Can be more expensive than off-the-shelf small business apps |
| ✅ High-level security and compliance framework | ❌ May have more features than necessary for very small teams |
9. Dayforce (Ceridian): Enterprise-Grade Human Capital Management
Dayforce, by Ceridian, is an enterprise-level Human Capital Management (HCM) platform designed for large, complex Australian organisations. It moves beyond standard payroll processing by offering a single, unified system for payroll, HR, time and attendance, scheduling, and talent management. Its key differentiator is a continuous pay calculation engine, which processes payroll data in real-time throughout the pay period, eliminating the need for traditional batch processing and providing greater accuracy.
Pricing and Plans
Dayforce operates on a bespoke, sales-led pricing model. Pricing is not publicly available and is tailored to the specific needs, size, and complexity of the organisation. This typically involves a detailed consultation, custom quote, and a structured implementation process.Key Considerations
| Pros | Cons |
|---|---|
| ✅ Single, fully integrated HCM & payroll platform | ❌ Best suited for larger or more complex organisations |
| ✅ Strong for complex, multi-award & multi-site needs | ❌ Sales-led quoting & longer implementation timelines |
| ✅ Real-time, continuous pay calculation engine | ❌ Can be overly complex for small-to-medium businesses |
10. Frontier Software (ichris HR & Payroll): The Enterprise-Grade Solution
For medium to large organisations requiring a powerful, highly configurable payroll and HR system, Frontier Software’s ichris platform is a formidable contender. Unlike many cloud-native solutions aimed at small businesses, ichris is built for complexity, capable of managing payroll for businesses with hundreds or even thousands of employees, including those with multi-country operations. This makes it a leading choice when considering the best payroll software Australia has for enterprise-level needs. The key differentiator for Frontier Software is its flexibility in service delivery. Organisations can choose to manage payroll in-house using the ichris software or fully outsource the entire function to Frontier's managed services team. This provides a crucial pathway for businesses to scale or adapt their operational models without changing their core system. The platform offers a deeply integrated suite covering HR, talent management, and workforce management, ensuring a single, authoritative source for all employee data.Pricing and Plans
Frontier Software does not offer standardised public pricing. Costs are customised based on the organisation's size, required modules (HR, payroll, etc.), and whether an in-house or outsourced model is chosen. A formal demonstration and scoping session is required to receive a detailed quote.Key Considerations
| Pros | Cons |
|---|---|
| ✅ Proven solution for large, complex organisations | ❌ Pricing is not transparent and requires a demo |
| ✅ Flexible delivery: in-house software or outsourced | ❌ Less suited for small businesses or start-ups |
| ✅ Integrated HR and workforce management suite | ❌ Implementation can be more complex than SMB tools |
11. The Access Group (MicrOpay / WageEasy / Attaché Payroll)
The Access Group caters to established Australian businesses with complex requirements or a preference for on-premise solutions. Its portfolio, which includes longstanding names like MicrOpay, WageEasy, and Attaché, offers robust payroll systems that can be deployed on-site or hosted, providing flexibility that many pure cloud providers lack. This makes it a key player for organisations with specific security protocols, legacy system integrations, or those transitioning to the cloud at their own pace.
Pricing and Plans
Pricing for The Access Group's payroll solutions is customised based on the specific product (MicrOpay, WageEasy, Attaché), deployment model (on-premise or hosted), and the scale of business operations. Businesses must contact their sales team directly for a tailored quote that reflects their unique requirements.Key Considerations
| Pros | Cons |
|---|---|
| ✅ Flexible on-premise or hosted deployment | ❌ Pricing is not transparent and requires a sales quote |
| ✅ Broad services including EOY consulting and training | ❌ Some modules have legacy UIs compared to newer cloud rivals |
| ✅ Strong choice for businesses with complex legacy needs | ❌ Navigating the product families on the website can be complex |
12. Capterra Australia – Payroll Software Category
Rather than a single software, Capterra Australia offers a powerful research tool: a comprehensive directory of payroll solutions. It serves as an essential starting point for businesses wanting to survey the market, compare features, and read user reviews before committing to a provider. This platform helps you validate your shortlist and discover new contenders you may have missed, making it an invaluable resource in the search for the best payroll software Australia has to offer. Capterra allows users to filter hundreds of listings by specific features, business size, and industry, which helps to narrow down the vast number of options. You can quickly compare pricing models and see aggregated user ratings at a glance. The platform aggregates reviews from real-world users, providing honest insights into the pros and cons of each system beyond the marketing material. It's a free and efficient way to conduct initial due diligence and ensure you're making an informed choice.Pricing and Plans
Capterra is a free-to-use directory for buyers. Software vendors may pay for premium placement in the listings.Key Considerations
| Pros | Cons |
|---|---|
| ✅ Broad overview of the Australian market | ❌ Sponsored listings can influence visibility |
| ✅ User reviews provide genuine insights | ❌ Some listed software may lack local compliance |
| ✅ Time-saving discovery and comparison tool | ❌ Information relies on vendor-provided data |
Top 12 Australian Payroll Software Comparison
| Product | Core features ✨ | Best for 👥 | Pricing / Value 💰 | Quality / USP ★🏆 |
|---|---|---|---|---|
| Xero | STP payroll, auto‑super, timesheets, broad add‑ons ✨ | Small–mid businesses & Xero users 👥 | Subscription; payroll in some plans — watch plan changes 💰 | ★★★★ 🏆 Integrated ledger + mature AU compliance |
| MYOB Business – Payroll | STP2, leave, super, employee portal ✨ | Very small teams → growing businesses 👥 | Payroll‑Only low‑cost for ≤4 staff; per‑employee fees by plan 💰 | ★★★★ Deep AU support & affordable entry |
| QuickBooks Online + Payroll | STP, employee self‑service, timesheets; QBO integration ✨ | QBO customers / small businesses 👥 | QBO + per‑employee payroll add‑on (can scale cost) 💰 | ★★★★ Easy migration for QuickBooks users |
| Employment Hero (KeyPay) | Advanced award interpretation, rostering, onboarding ✨ | SMEs & mid‑market with complex awards 👥 | Per‑employee pricing + monthly mins; implementation extra 💰 | ★★★★ 🏆 Powerful award automation & end‑to‑end HR |
| Reckon Payroll | STP, mobile pay‑runs, simple tiers, AU hosting ✨ | Micro & small businesses 👥 | Competitive entry tiers (up to 4/10 emp) — value for micro firms 💰 | ★★★ Affordable + mobile flexibility |
| Payroller | STP2, web/mobile app, Xero integration, quick setup ✨ | Sole traders & micro teams / first‑time payroll 👥 | Very low per‑employee price; free trial; min spend applies 💰 | ★★★ Fast setup and low entry cost |
| CloudPayroll (Australia) | STP, SuperChoice auto‑super, employee kiosk, pay‑run pricing ✨ | Businesses preferring per‑pay‑run or managed options 👥 | Transparent per‑pay‑run fees; setup fees may apply 💰 | ★★★★ Flexible DIY/outsourced options |
| ADP Australia (Payline) | STP, PAYG, super, secure cloud, local support ✨ | 1–199 emp and organisations needing scale/outsourcing 👥 | Quote‑based; can be costlier than SME apps 💰 | ★★★★ 🏆 Scales from software to fully outsourced payroll |
| Dayforce (Ceridian) | Continuous payroll calc, time & attendance, scheduling ✨ | Mid → large employers & multi‑site organisations 👥 | Sales‑led quoting; longer implementation timelines 💰 | ★★★★ Integrated HCM + payroll for complex needs |
| Frontier Software (ichris) | Multi‑country payroll, outsourcing, HR integration ✨ | Mid‑enterprise to large organisations 👥 | Demo/quote pricing; enterprise costing 💰 | ★★★★ Proven vendor for large‑scale payroll |
| The Access Group (MicrOpay/WageEasy) | STP, hosted/on‑prem options, EOY services ✨ | Firms needing hybrid/legacy or deep consulting 👥 | Product‑family pricing; sales‑led quotes 💰 | ★★★ Broad portfolio & consulting/training services |
| Capterra Australia – Payroll | Vendor listings, reviews, filters, trial links ✨ | Buyers shortlisting payroll solutions 👥 | Free to use; sponsored listings exist 💰 | ★★★ Market view & user reviews for validation |
Making Your Final Decision and Seeking Expert Advice
Navigating the landscape of Australian payroll software can feel overwhelming. We've explored a dozen powerful platforms, from all-in-one accounting suites like Xero and QuickBooks to dedicated payroll powerhouses like Employment Hero and enterprise-grade solutions such as Dayforce and ADP. The key takeaway is clear: there is no single "best" solution for every business. The right choice is deeply personal to your organisation's unique circumstances. A sole trader with no employees has vastly different needs than a manufacturing firm with 200 staff covered by multiple complex modern awards. Similarly, a high-growth tech startup prioritising scalability and API integrations will value different features than a family-run property investment company focused on straightforward compliance and ease of use. Your journey to finding the best payroll software Australia has to offer begins with a clear understanding of your own requirements.Creating Your Shortlist: A Practical Framework
To move from this comprehensive list to a confident decision, you need a structured evaluation process. Don't get distracted by flashy features you'll never use. Instead, focus on the core elements that will directly impact your day-to-day operations and long-term compliance. Use the detailed reviews in this article to create a shortlist of two to three top contenders. Filter your options based on these critical factors:- Business Size and Scalability: Are you a small business that fits perfectly with Payroller or MYOB's Payroll Only plan, or do you anticipate rapid growth and need a platform like Employment Hero that can scale with you?
- Industry Complexity: Does your business operate under complex modern awards or enterprise bargaining agreements (EBAs)? If so, the award interpretation engines in platforms like Employment Hero or dedicated solutions from The Access Group become non-negotiable.
- Integration Ecosystem: How critical is it for your payroll to communicate seamlessly with your accounting software, rostering tools, or HR platform? Xero and QuickBooks excel here with their extensive app marketplaces, while specialised systems may require more complex integrations.
- Budget and Total Cost of Ownership: Look beyond the initial subscription fee. Consider implementation costs, training requirements, and charges for additional support or features. A "cheaper" solution can quickly become expensive if it requires significant manual workarounds.
- User Experience and Support: Who will be using the software? The platform must be intuitive for your team. Furthermore, evaluate the quality and accessibility of Australian-based customer support, as this can be a lifesaver during critical pay runs.
The Critical Next Steps: From Shortlist to Selection
Once you have your shortlist, it's time to get hands-on. Reading reviews is one thing; experiencing the software is another.- Utilise Free Trials: Most providers targeting small to medium businesses offer a free trial period. Use this time to process a mock pay run with your actual employee data and scenarios. Test the features that matter most to you.
- Request Personalised Demos: For more complex, enterprise-level systems like ADP or Dayforce, a personalised demo is essential. Prepare a list of specific questions and scenarios relevant to your business to see exactly how the platform handles them.
- Validate Compliance and Support: Ask direct questions about their Single Touch Payroll (STP) Phase 2 reporting capabilities, superannuation clearing house (SuperStream) compliance, and their roadmap for future legislative changes in Australia.
Selecting the right software is a crucial first step, but ensuring it's implemented correctly and managed for ongoing compliance is what truly matters. The experts at Australia Wide Tax Solutions can guide you through this entire process, from software selection and setup to ongoing bookkeeping and BAS lodgement. Ensure your payroll system is a powerful asset, not a compliance risk, by partnering with a team that understands the intricate details of Australian business. Visit Australia Wide Tax Solutions to learn how professional guidance can secure your peace of mind.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
What Is Salary Sacrificing and How Does It Work?
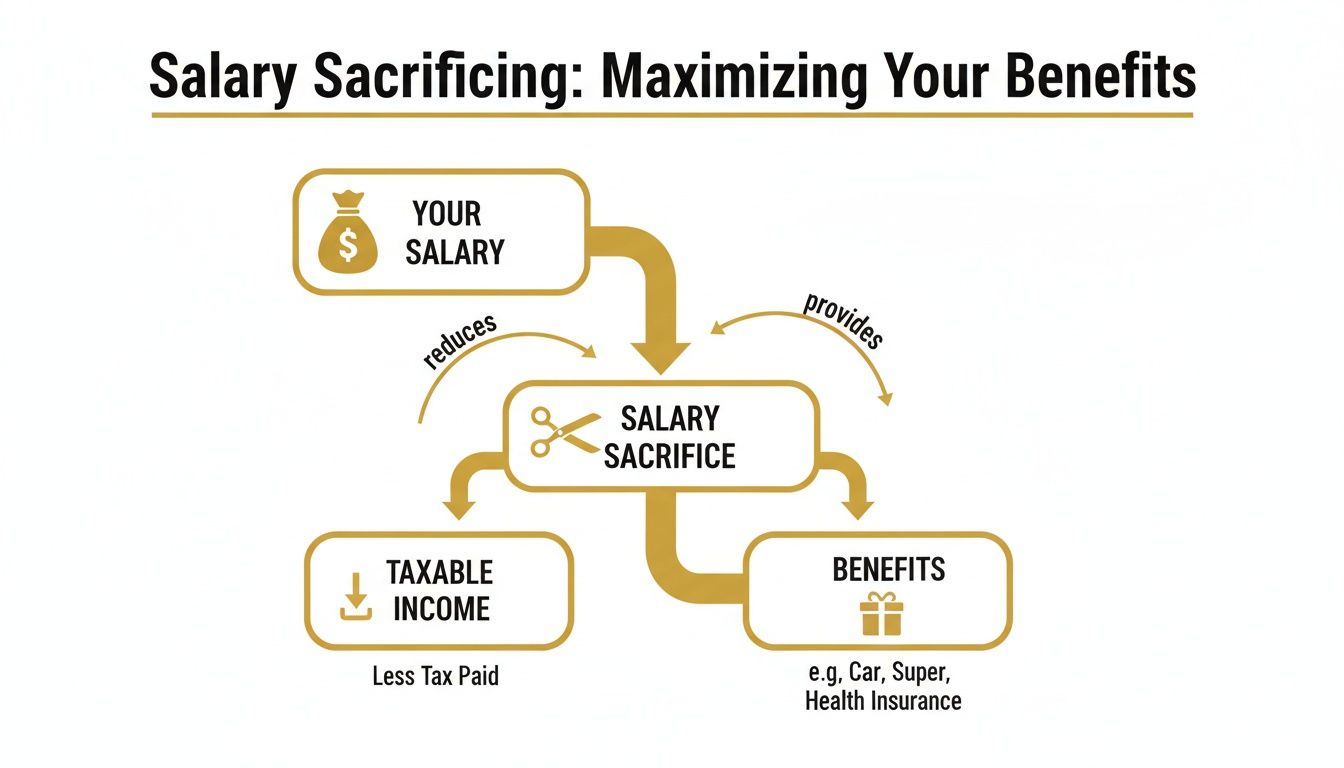
Let's break it down. Picture your total salary as a pie. Normally, the Australian Taxation Office (ATO) comes along and takes its slice before you get what's left. Salary sacrificing—sometimes called salary packaging—lets you earmark a piece of that pie for specific, approved benefits before the ATO figures out your tax. Because you’ve set that piece aside, the pie the ATO looks at is now smaller. A smaller pie means a smaller tax slice. You still get the full value of what you earned, but part of it shows up as a benefit—like extra superannuation contributions or a novated car lease—instead of just cash in the bank. At its core, it’s a simple idea: you're turning taxable cash into a tax-effective benefit. By reducing your income on paper, you could drop into a lower tax bracket, keeping more of your hard-earned money in your pocket.A Simple Before-and-After Example
Say you earn an annual salary of $90,000. Without any arrangements, you’d be taxed on that full amount. Now, imagine you decide to salary sacrifice $10,000 directly into your super fund. Just like that, your taxable income drops to $80,000. You'll only pay income tax on this lower figure, leading to some serious savings over the financial year, all while giving your retirement nest egg a healthy boost.Key Takeaway: This isn't something you can do on a whim. The arrangement has to be locked in with your employer before you've actually earned the income. You can't sacrifice money that's already landed in your bank account.This flowchart gives you a quick visual of how it all works.
Supercharge Your Retirement with Superannuation Contributions
Staying Within The Limits
To get the most out of this strategy, you need to play by the rules. The government sets annual limits on how much you can contribute this way. Your salary sacrificed contributions, along with your employer’s mandatory Superannuation Guarantee payments, all count towards your concessional contributions cap. Go over this cap, and you could face extra tax, completely wiping out the benefits you were aiming for. It’s a simple but absolutely vital rule to follow. For a deeper dive on how these caps work, you can check out our detailed guide on the Concessional Contributions Cap.A Critical Check To Make
Before you jump in, there’s one crucial conversation you must have with your employer.Your employer must continue to pay their Superannuation Guarantee (SG) contributions based on your ordinary salary before the sacrificed amount is deducted. An arrangement should not reduce the SG you’re entitled to.Make sure this is crystal clear in your salary sacrifice agreement. Get into the habit of checking your payslips and super statements to confirm you’re still receiving your full, legally required super payments on top of your own voluntary contributions. For our friends across the ditch in New Zealand looking to boost their own retirement funds, understanding things like KiwiSaver employer contributions can offer some valuable parallels.
Driving Down Your Tax with a Novated Car Lease
How a Novated Lease Simplifies Car Ownership
One of the biggest draws of a novated lease is just how simple it makes everything. All your major car expenses are bundled into one single, predictable deduction from your payroll. The big win? Because it’s coming from your pre-tax salary, you often end up paying less overall. Your bundled payments can cover a whole range of costs:- The lease payments for the car itself
- Fuel or electricity costs
- Comprehensive insurance
- Registration and CTP (Compulsory Third Party)
- Scheduled servicing and maintenance
- Even tyre replacements
This "all-in-one" approach makes budgeting a breeze and gets rid of the headache of juggling multiple bills. On top of that, you get the benefit of GST savings on the car’s purchase price and on its running costs.Managing these expenses is often made even easier with a fuel card, which usually comes as part of the package. It's worth understanding what a fuel card is and how it helps you track all your vehicle-related spending without fuss. Essentially, you get access to fleet discounts when buying the car and get to pay for almost everything else with untaxed money. If you're weighing up your options, taking a look at which motor vehicle expenses the ATO allows can give you a much clearer picture of the potential savings.
Exploring Other Common Fringe Benefits
Common Items You Can Package
So, what else is on the menu? Many employers allow you to package items that are essential for your job, like laptops and mobile phones, particularly if they are used primarily for work. This is a fantastic way to fund necessary tech upgrades without feeling the full pinch in your post-tax paycheque. Beyond the tools of the trade, some policies extend to your personal and family life. You might find you can salary sacrifice expenses such as:- Self-education fees that are directly related to your current role.
- Professional memberships and industry journal subscriptions.
- Financial advice from a qualified professional.
- Childcare centre fees (this is a big one for eligible employees).
It’s crucial to know that providing these benefits can trigger Fringe Benefits Tax (FBT) for your employer. Understanding what FBT is and how it works is essential, as it heavily influences which benefits a company is willing to put on the table for its staff.To give you a clearer picture, the table below breaks down some of the most common fringe benefits you might come across.
Common Salary Sacrifice Items at a Glance
This table offers a quick summary of the items you can often package, how they work, and who they’re best suited for.| Benefit Item | How It Works (Pre-tax) | Key Tax Consideration | Best Suited For |
|---|---|---|---|
| Laptop/Portable Device | The cost of a work-related laptop is deducted from your pre-tax salary. | Generally FBT-exempt if the device is primarily used for work. Limit of one per FBT year. | Professionals who need up-to-date technology for their job. |
| Mobile Phone | Your phone plan or the cost of the handset can be paid from pre-tax income. | Also typically FBT-exempt if used mainly for work purposes. | Anyone who relies on their mobile for work calls and communication. |
| Professional Memberships | Annual fees for industry associations are paid directly from your salary. | Usually deductible and FBT-exempt as a work-related expense. | Individuals in industries requiring professional accreditation. |
What You Need to Know Before You Start
Jumping into a salary sacrifice arrangement can be a fantastic financial move, but it really pays to understand the rules of the road first. The single most important rule is all about timing: the arrangement must be formally documented with your employer before you’ve earned the income you intend to sacrifice. You simply can't package money that has already been paid to you. Beyond this golden rule, it's vital to see the bigger picture. Lowering your taxable income might sound great on the surface, but it can have flow-on effects on other parts of your financial life.This is because many government calculations don't just look at your taxable income. Instead, they use your 'adjusted taxable income', which adds back any sacrificed amounts.This adjusted figure is the one that really counts when assessing things like:
- Your HELP debt repayment obligations
- Child support payments
- Eligibility for certain Centrelink or family assistance benefits
Understanding the Full Financial Impact
Even with economic pressures, salary sacrifice plans are holding strong. Recent survey data shows a massive 81% of Australian employees would consider salary sacrificing if offered, with the top priorities being mortgage help (37%) and boosting their super contributions (24%). You can explore more about these trends and what drives employee decisions in this insightful report from Computershare. This popularity highlights just how important it is to make an informed choice. Before you commit, take the time to dig into your employment contract to get clear on your company's specific policies. Because everyone's situation is unique, getting professional financial advice is one of the smartest steps you can take. A good financial advisor can help you properly weigh the tax benefits against any potential impacts, making sure your salary sacrifice strategy truly works for you and supports your long-term goals—without any unwelcome surprises down the line.Common Questions About Salary Sacrificing
Getting into the nitty-gritty of salary sacrificing often brings up a few common questions. Let's tackle some of the most frequent queries to give you a clearer picture of how it all works in practice and what it means for your finances.Can Salary Sacrificing Lower My Employer's Super Payments?
This is a big one. Legally, your employer has to pay the Superannuation Guarantee (SG) on your ordinary time earnings (OTE). The catch? Some employers might calculate this on your reduced cash salary after you've sacrificed a portion. It's absolutely vital to get this clarified in your agreement to make sure your mandatory super contributions aren't accidentally cut.What Happens If I Change Jobs?
Think of your salary sacrifice arrangement as being tied directly to your current employer. The moment you leave, that agreement ends. You'll need to start from scratch and negotiate a brand new arrangement with your new employer, and there's no guarantee their policies or the benefits on offer will be the same.Salary sacrificing really shines thanks to Australia's progressive tax rates, which is why higher earners often see the biggest benefits. For someone on $90,000 a year, sacrificing $5,000 into super means they avoid a 37% tax hit on that amount, saving them a cool $1,100. Compare that to someone earning $50,000 with a 32.5% marginal rate, who would only save $875. You can find more detail on how income levels affect super contribution tax savings on moneymanagement.com.au.
Are There Limits on How Much I Can Salary Sacrifice?
While there isn't a single, overarching limit on the total amount you can package, there are definitely caps on specific benefits. The most common one is the annual limit on concessional superannuation contributions. If you go over these caps, you can get hit with extra tax, so it's crucial to keep a running tally of your contributions throughout the financial year.Can I Package My Mortgage or Rent Payments?
For most people, the answer is no. Mortgage and rent are considered private expenses and can't be salary sacrificed. However, there’s a major exception for people working for certain tax-exempt organisations, like public benevolent institutions (PBIs) and public hospitals. Thanks to special Fringe Benefits Tax (FBT) concessions, eligible employees in these sectors can often package these living costs, which is a massive financial advantage. Always double-check your eligibility based on where you work.Ready to make your salary work smarter for you and lock in every possible deduction? The expert team at Australia Wide Tax Solutions can give you personalised advice to structure your finances for the best possible outcome. Contact us today to maximise your tax position.
Yes, if you are under 75 and meet the work test (if aged 67–74). Lodge a notice of intent to claim with your fund before the earlier of the tax return due date or the lodgement date. Once the fund acknowledges the notice, the contribution becomes concessional and is taxed at 15% inside the fund.
The concessional contributions cap for 2025-26 is $30,000. This covers employer SG contributions, salary sacrifice, and personal deductible contributions combined. Contributions above the cap are included in assessable income at your marginal rate, with a 15% tax offset for the tax already paid inside the fund.
The Super Guarantee rate for 2025-26 is 11.5%, rising to 12% from 1 July 2025. Employers must contribute this percentage of each eligible employee's ordinary time earnings to a complying super fund at least quarterly. Late or missing payments trigger the Super Guarantee Charge, which includes interest and is not tax deductible.
Salary sacrifice contributions come from pre-tax income and are taxed at 15% inside super rather than at your marginal rate (up to 47%). The difference is your tax saving. A taxpayer in the 37% bracket saves 22 cents per dollar sacrificed, subject to the $30,000 concessional cap.
Yes, if your total super balance was below $500,000 on 30 June of the prior year. Unused cap amounts from the previous five years can be carried forward and used in a higher-income year. The oldest unused amounts are applied first, allowing catch-up contributions that significantly reduce tax for eligible individuals.