
So, when do you actually have to register for GST? Let's cut through the jargon.
- The 21-Day Countdown After You Hit the Threshold
- When the $75k Threshold Does Not Apply
- Voluntary GST Registration: Is It Right for You?
- How to Get Your GST Registration Sorted
- Life After Registration: Your Ongoing Responsibilities
The magic number you need to remember is $75,000. If your business's GST turnover hits this amount—or you expect it to—within any 12-month period, it’s time to register.
Crucially, this isn't about your annual profit. It’s the total sales your business makes before you subtract any expenses.
Decoding The GST Registration Threshold
The $75,000 GST turnover threshold is the key trigger. Think of it less like a fixed finish line at the end of the financial year and more like a moving window that’s always looking at your revenue.
This rule has been a cornerstone of Australian business tax since GST was introduced way back in 2000. It applies to any rolling 12-month period, which means you need to look at both your sales from the last 12 months and what you reasonably expect to make in the next 12 months.
Your Business Revenue Radar
Imagine your business has a 'revenue radar' constantly scanning your income. This radar looks backwards at the last 12 months of sales and forwards at your projected income for the upcoming year.
The second that radar shows your turnover hitting (or being very likely to hit) $75,000, your obligation to register is triggered. This proactive mindset is what keeps you off the ATO's naughty list and prevents nasty surprises down the track.
Of course, for your radar to work, you need a solid grip on your small business bookkeeping basics. Without clean records, you’re flying blind.
What Counts as GST Turnover?
This is where people often get tripped up. What exactly does the ATO include in "GST turnover"?
It’s your gross business income, which is a lot more than just the cash from your main product or service. It generally includes:
- Total income from the sales of your goods or services.
- The value of any goods you take from the business for your own personal use.
- Income from selling business assets, like that old office printer or company ute.
However, some things are left out. You don't need to count sales that aren't for payment, aren't connected to your business activities (like a personal hobby), or involve selling your entire business as a going concern.
It’s also vital to separate your genuine business activities from personal projects. If you're unsure where the line is, our guide on https://awts.net.au/blog/is-it-a-business-or-a-hobby/ can help clear things up.
The most common mistake business owners make is forgetting that GST turnover is a rolling measure. A quiet January doesn't reset the clock if the previous eleven months were strong. You must always be looking at the bigger picture.
This flowchart gives you a simple visual for making the call.
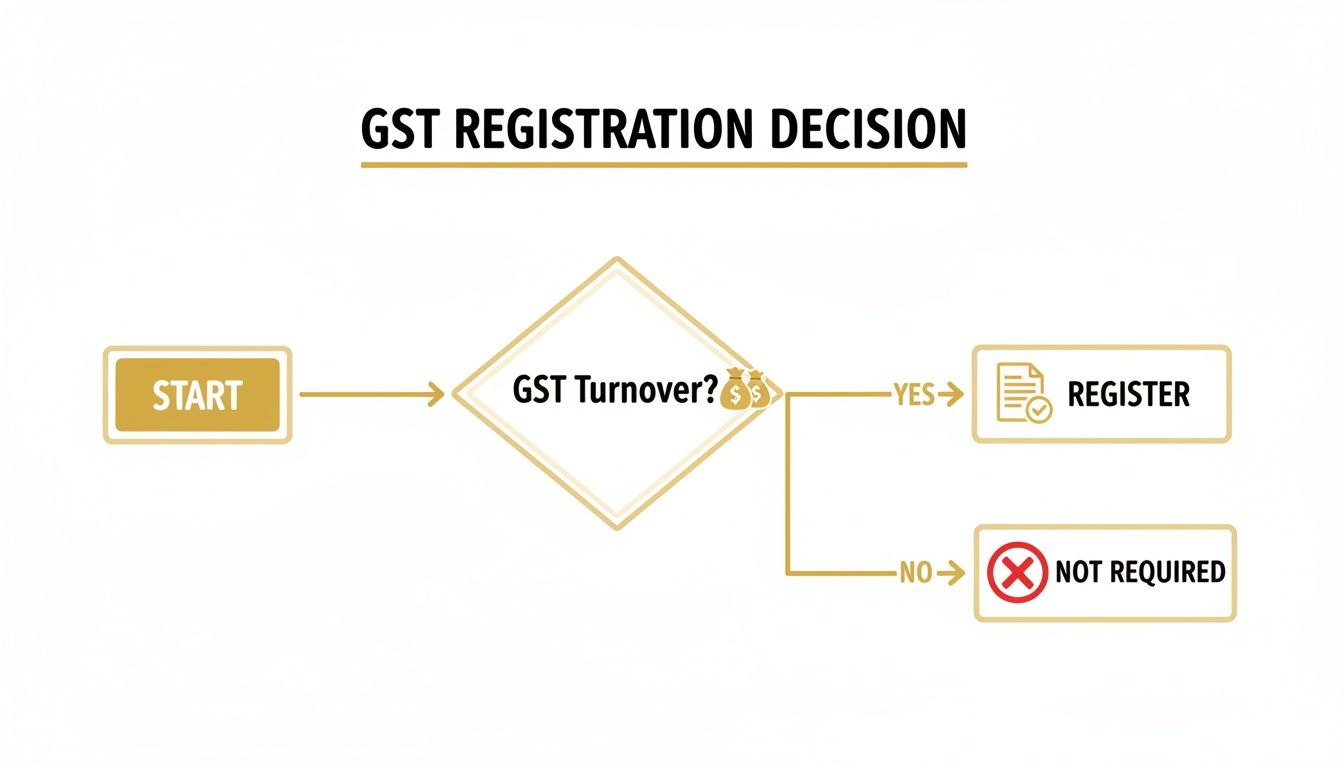
As the infographic shows, it’s a straightforward rule: if your turnover is over the threshold, registration isn’t optional—it’s mandatory.
Calculating Your GST Turnover: What to Include and Exclude
To make it even clearer, here’s a quick reference table to help you figure out what counts towards that $75,000 figure.
| Revenue Type | Include in GST Turnover? | Example |
|---|---|---|
| Sales of Goods & Services | Yes | A bakery selling $80,000 worth of cakes and bread in a year. |
| Export Sales | No | An artist selling paintings to a gallery in New York. |
| Sales of Business Assets | Yes | A courier selling their old delivery van for $10,000. |
| Input-Taxed Sales | No | A landlord receiving residential rent (this is financial supply). |
| Personal Use of Stock | Yes | A cafe owner taking home $100 worth of coffee beans each month. |
| Sale of a Business | No | Selling your entire business as a 'going concern' to a new owner. |
Keeping this table in mind will help you stay on top of your numbers and avoid accidentally crossing the threshold without realising it.
The 21-Day Countdown After You Hit the Threshold
Knowing your turnover is one thing; acting on it is the real test. The moment your business's 'revenue radar' pings to confirm you've crossed the $75,000 threshold—or you can see it's about to happen—a critical timer starts. The Australian Taxation Office (ATO) gives you exactly 21 days to get registered for GST.
Make no mistake, this isn't a friendly suggestion. It’s a hard legal deadline. That 21-day window kicks off the second your GST turnover officially passes the threshold, and ignoring it can lead to some serious financial headaches. We’re talking back-dated GST liabilities and ATO penalties that can chew a hole straight through your profits.
A Real-World Scenario
Let's put this into perspective. Imagine you're a freelance marketing consultant. For months, things have been ticking along nicely at around $6,000 per month. Then, a huge opportunity lands in your lap: two big retainer clients sign on in the same month. Suddenly, your projected annual turnover skyrockets to well over $80,000.
Your 21-day countdown starts from the day you sign those contracts—the point where you can reasonably expect to exceed the threshold. If you put it off and wait a couple of months to register, the ATO will simply backdate your registration to when you should have done it.
This is where the pain starts. It means you owe GST on every single taxable invoice you've sent since that backdated registration date, even if you never actually charged your clients for it. Trying to circle back to a client weeks later to ask for an extra 10% is an awkward, unprofessional conversation nobody wants to have.
The biggest risk of registering late is having to pay the GST out of your own pocket. For a business running on tight margins, an unexpected tax bill for 1/11th of two months' revenue can cause a serious cash flow crisis.
Proactive Strategies to Stay Ahead
Instead of letting the threshold sneak up on you, get out in front of it. Modern accounting software is your best friend here. You can set up custom reports and alerts that act as an early warning system, keeping a close eye on your rolling 12-month turnover.
Here are a few simple, actionable steps to avoid a last-minute scramble:
- Set Revenue Alerts: Jump into your accounting software (Xero or MYOB, for example) and configure an email notification to ping you when your turnover hits a certain point, say, $65,000.
- Monthly Check-ins: Carve out just 15 minutes at the start of each month to review your turnover for the previous 12 months. It's a simple habit that keeps you fully informed and in control.
- Forecast Your Pipeline: If you have a solid sales pipeline with several large projects on the horizon, don't ignore it. Factor this projected income into your calculations to see what's coming.
By understanding the deadline and actively monitoring your revenue, you can turn a potential compliance disaster into a straightforward admin task. You’ll know exactly when the time is right to register for GST and can manage your obligations with complete confidence.
When the $75k Threshold Does Not Apply
While the $75,000 turnover rule is a reliable guide for most businesses, it’s definitely not a one-size-fits-all situation. Certain industries operate under a completely different set of rules, and assuming the standard threshold applies can land you in hot water with the Australian Taxation Office (ATO).
Understanding these exceptions is absolutely critical if you operate in one of these specific sectors. For these businesses, the question of when to register for GST has a completely different answer—often requiring registration from the very first dollar earned.
Rules for Taxi and Ride-Sourcing Services
If your business involves providing taxi, limousine, or ride-sourcing services, the GST rules are strict and immediate. The $75,000 threshold simply does not apply to you. Full stop.
You must register for GST from the moment you start your business, no matter how much you expect to earn. This means if you sign up to drive for a ride-sourcing platform like Uber or DiDi and complete your very first trip, you are legally required to be registered for GST.
For taxi and ride-sourcing drivers, GST registration is not a milestone to be reached; it is a Day One requirement. Failing to register immediately means you are operating outside of tax law from your very first fare.
This special rule exists to ensure a level playing field in the passenger transport industry. You'll also need to issue proper tax invoices and start lodging Business Activity Statements (BAS) to report your GST obligations right away.
Special Threshold for Non-Profit Organisations
Non-profit organisations also play by a different set of rules, but in their case, the threshold is higher, offering a bit more breathing room.
A non-profit is only required to register for GST if its annual turnover hits $150,000 or more. That’s double the standard threshold for for-profit businesses. This higher limit acknowledges the unique community focus of these entities and helps reduce their administrative load.
This higher threshold applies to specific types of organisations:
- Charitable Institutions: This includes any organisation endorsed by the ATO as a charity.
- Trustee of a Charitable Fund: This applies to funds set up purely for charitable purposes.
- Gift Deductible Entities: Any organisation that can receive tax-deductible donations.
- Government Schools: Public primary and secondary schools also fall under this category.
If your non-profit’s turnover stays below $150,000, you don't have to register. However, you can still choose to register voluntarily if it makes financial sense for your organisation—for instance, to claim back the GST credits on significant purchases or expenses.
Voluntary GST Registration: Is It Right for You?
Just because your business turnover is safely below the $75,000 threshold doesn’t mean the GST system is off-limits. For many ambitious businesses, choosing to register for GST voluntarily is a powerful strategic move, not just another tax chore.
Making this call is about more than just compliance; it can seriously impact your cash flow and how other businesses see you in the market. It’s a trade-off, weighing immediate financial perks against new administrative duties. Thinking about this before you’re legally required to is a sign you’re on top of your finances.
The Power of Claiming GST Credits
The single biggest drawcard for voluntary registration is the ability to claim back the GST you pay on business expenses. These are known as GST credits or input tax credits.
Without being registered, that 10% GST you pay on supplies, equipment, and services is just a dead cost that eats into your profit. Once you register, that 10% becomes reclaimable from the ATO.
Let’s say you’re launching a new cafe. The initial fit-out is a huge expense, with big-ticket items like a coffee machine, fridges, and furniture.
- Commercial Espresso Machine: $11,000 (which includes $1,000 in GST)
- Refrigeration Units: $8,800 (including $800 in GST)
- Cafe Furniture & Decor: $5,500 (including $500 in GST)
In this scenario, you've shelled out $2,300 just on the GST component of these essential items. By registering for GST voluntarily from day one, you can claim this entire amount back on your first Business Activity Statement (BAS). That’s a massive cash injection right when a new business needs it the most.
Weighing the Pros and Cons
Voluntary registration isn’t a one-way street. While claiming back GST is a huge win, it comes with extra responsibilities. The main hurdle is the admin workload of tracking GST, reporting it accurately, and lodging your BAS on time. You’ll also need to add 10% GST to your own prices, which could make you less competitive if your customers are mainly individuals who can't claim it back.
Choosing to register for GST is about more than just tax; it’s about positioning your business for growth. It signals to suppliers and larger clients that you're established and operate within the formal tax system, which can seriously boost your credibility.
To help you figure out if it's the right move for you, here’s a straightforward breakdown of the pros and cons.
Voluntary GST Registration Pros vs Cons
| Consideration | Pros (Advantages of Registering) | Cons (Disadvantages of Registering) |
|---|---|---|
| Business Expenses | You can claim back the GST paid on your purchases and operating costs, improving cash flow. | You must track all GST paid and collected, increasing your bookkeeping workload. |
| Pricing & Competition | May not impact B2B sales, as your business clients can claim back the GST you charge. | You must add 10% GST to your prices, potentially making you more expensive for retail customers. |
| Administration | Encourages better financial record-keeping habits from the start. | You are legally required to lodge a Business Activity Statement (BAS) regularly (monthly or quarterly). |
| Business Credibility | An ABN registered for GST can make your business appear more established and professional to larger clients. | Missing BAS lodgement deadlines can result in penalties and interest charges from the ATO. |
Ultimately, the right choice comes down to your specific business model, your customer base, and your plans for the future. If you’re a B2B business or have high startup costs, the benefits of registering early often far outweigh the administrative headaches.
How to Get Your GST Registration Sorted
Alright, so you’ve worked out that you need to register for GST. The next part is mostly admin—think of it as officially putting your hand up and telling the Australian Taxation Office (ATO) that your business is now in the GST club.
To make this painless, it’s a smart move to get all your business details lined up before you start. A bit of prep work here saves a lot of headaches and back-and-forth later.
What You'll Need to Have Ready
Before you jump into the application, pull together these key details. It'll make the whole thing much smoother.
- Your Australian Business Number (ABN): This is non-negotiable. If you don't have an ABN yet, you'll need to sort that out first. Our guide on how to register a business in Australia walks you through it.
- Proof of Identity: You’ll need some basic details to confirm you are who you say you are.
- Business Contact Details: This means your registered business address, phone number, and a good email contact.
- What Your Business Does: Just a straightforward description of your main business activities.
- Projected GST Turnover: Your best estimate of the business's annual income.
- The Start Date: You need to pick the date your GST registration officially kicks in. The good news is this can be backdated if you’ve already shot past the threshold.
The Different Ways to Register
Once you have your info packet ready, you’ve got a few different paths you can take to get registered. Each one is designed for different needs, so you can pick the one that feels right for you.
- Do It Yourself Online: The quickest and most popular route is using the ATO’s online services. You'll use your myGovID linked to the Relationship Authorisation Manager (RAM) to get into the Business Registration Service. It’s a self-service portal that guides you through each step.
- Get a Pro to Handle It: If you're feeling a bit lost or just want to be 100% sure it's done right, using a registered tax or BAS agent is your best bet. They’ll take care of the whole process for you, giving you total peace of mind that it's all correct.
- Give Them a Call: You can also register by phoning the ATO. This is a solid option if you have some specific questions and would rather talk it through with an actual person.
Choosing how to register really comes down to convenience versus confidence. While going online is fast, having a tax professional handle it takes all the guesswork out of the equation. They make sure you’re set up correctly from day one, which can save you from a world of compliance pain down the track.
Life After Registration: Your Ongoing Responsibilities
Flipping the switch to 'GST registered' isn't the finish line; it’s really just the beginning. It introduces a new rhythm into your business operations, where your main job is to balance the GST you collect on sales against the GST you pay on your business buys.
This whole process is managed through your Business Activity Statement (BAS). The simplest way to think about the BAS is as your regular financial check-in with the Australian Taxation Office (ATO). It’s where you report the GST you’ve collected, claim back GST credits on your expenses, and then settle the difference. Getting your head around how to prepare a business activity statement is a core skill for any registered business owner in Australia.
Your Reporting Cycle
Once you're in the system, the ATO will pop you onto a reporting cycle, which just dictates how often you need to lodge your BAS. For most new businesses, this will be a quarterly schedule.
- Quarterly: This is the default setting for most small businesses. You'll lodge your BAS every three months, keeping your compliance manageable without being overwhelming.
- Monthly: If your business has a GST turnover of $20 million or more, the ATO will generally require you to report on a monthly basis.
- Annually: This is much less common and is typically reserved for very small businesses that have registered voluntarily and have a low turnover.
The key here is consistency. Lodging and paying on time, every single time, is non-negotiable. Missing those deadlines can lead to penalties and interest charges that can snowball surprisingly quickly.
A crucial point to remember: once you're registered, you have to lodge a BAS for every single reporting period. This applies even if you had zero business activity. A 'nil' BAS still needs to be filed to let the ATO know what’s going on.
Invoicing and Record Keeping
Your invoicing process will need an immediate upgrade. Every invoice you send to another business must now be a proper tax invoice. This isn't just a suggestion; it's a legal requirement. It means including specific details like your ABN, clearly stating "Tax Invoice," and showing the exact amount of GST charged.
Finally, meticulous record-keeping becomes your new best friend. The law mandates that you hold onto all business records related to your tax obligations for at least five years. This includes every tax invoice and receipt. Think of this documentation as your proof; it’s what you’ll rely on if the ATO ever has questions about your BAS lodgements. Building these habits from day one makes compliance a simple, stress-free part of your business routine.
Common Questions About GST Registration
Even with the clearest roadmap, you're bound to have questions when figuring out your GST obligations. This final section tackles some of the most common queries we hear from business owners, helping you tie up any loose ends.
What Happens if I Register Late?
This is a scenario you want to avoid. If you register for GST late, the Australian Taxation Office (ATO) will backdate your registration to the day you were first required to do so.
What does that mean for you? You’ll be liable for GST on every taxable sale you've made since that backdated start date, even if you never included GST in your prices. On top of that, you could be hit with penalties and interest charges for the delay. The best move is to act fast and get a tax professional involved to help manage the fallout and minimise any financial pain.
Can I Cancel My GST Registration?
Yes, you can, but only in specific situations. Usually, this happens if your business has shut down, been sold, or if your GST turnover has dropped below the $75,000 threshold and you expect it to stay there.
To cancel because of low turnover, you generally need to have been registered for at least 12 months. Be aware that you'll have to lodge a final BAS, and you might have to repay any GST credits you claimed on business assets you still own.
Should I Have a Separate Bank Account for GST?
While it’s not legally required, it’s one of the smartest financial habits you can build.
Opening a separate bank account just for the GST you collect is a game-changer. Think of it as parking the ATO's money somewhere safe. It prevents that money from being accidentally swallowed up by business expenses, making sure it's ready to go when your BAS payment is due.
Putting the GST portion of every sale into a dedicated account makes managing your tax obligations so much less stressful. It stops cash flow surprises dead in their tracks.
Navigating GST registration and staying compliant can feel like a minefield, but you don't have to walk it alone. The team at Australia Wide Tax Solutions offers expert accounting and BAS services to make sure you meet every obligation, accurately and on time. Let us handle the details so you can get back to what you do best: growing your business with complete confidence. https://www.awts.net.au
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
A Clear Guide to Penalties and Compliance
- The Real Cost of a Tax Mistake
- Decoding The Main Types Of ATO Penalties
- How Interest Charges Can Amplify Your Tax Debt
- Common Mistakes That Trigger ATO Penalties
- Proactive Strategies For Avoiding Tax Fines
That sinking feeling you get when an unexpected notice from the Australian Taxation Office (ATO) lands in your inbox? It’s something no one wants to experience. An ATO penalty isn't just a simple fee; it's a financial consequence for not meeting your tax obligations, whether you meant to or not.
These penalties are part of a structured system the ATO uses to keep Australia’s tax framework fair and functional. But what many people don’t realise is just how easy it is to trigger one. A late Business Activity Statement (BAS), forgetting to declare income from that side hustle, or claiming a deduction you weren't entitled to can all lead to a fine.
The Real Cost of a Tax Mistake
Getting hit with a penalty is often just the first step. The true cost of falling behind on your tax obligations can snowball, creating a ripple effect that puts a serious strain on your finances.
Think of it less like a one-off parking ticket and more like a high-interest credit card debt that just keeps growing if you ignore it. That’s because the ATO doesn’t just issue a fine; it also charges interest on any unpaid tax and penalties. What starts as a manageable amount can quickly become a significant financial headache.
The True Impact of Non-Compliance
For individuals and businesses, the fallout can be pretty serious. An overlooked tax return or a miscalculation can lead to:
- Financial Strain: Penalties and compounding interest can escalate fast, turning a small oversight into a major debt that’s hard to get out from under.
- Increased Scrutiny: Once you have a record of non-compliance, you can bet the ATO will be paying closer attention to you in the future. This means a higher chance of being audited.
- Stress and Uncertainty: Dealing with penalties, trying to communicate with the ATO, and fixing mistakes is incredibly time-consuming and stressful. It’s a distraction you just don’t need.
It’s important to remember that the point of these fines isn’t just to punish people. It’s about reinforcing why timely, accurate tax reporting is so crucial for everyone. Seeing it this way helps shift your mindset from fear to proactive compliance.
This guide is here to pull back the curtain on Australian tax fines. We’ll break down exactly how penalties are calculated, walk through the most common mistakes that lead to them, and give you practical, real-world advice to manage your tax obligations with confidence.
By understanding the rules of the game, you can avoid preventable financial pain and keep your relationship with the ATO on solid ground. That way, you can focus on what really matters—your personal and business goals, not chasing down tax problems.
Decoding The Main Types Of ATO Penalties
To stay out of trouble with Australian tax fines, you first have to know what you’re up against. The Australian Taxation Office (ATO) doesn’t just hand out one generic "fine" for every mistake. Instead, they have a structured system of penalties designed to tackle specific issues, from being a bit late with your paperwork to deliberately misleading them.
Think of it this way: the ATO cares about both the action and the intention. It’s not just about what you did wrong, but why you did it. Getting your head around this difference is the first step to building solid compliance habits and avoiding a whole lot of financial stress.
Let's break down the two main penalty categories you’re most likely to come across.
The Cost of Missing a Deadline
One of the easiest ways to get a penalty is by simply failing to lodge a document on time. This is called a Failure to Lodge (FTL) penalty. Whether it’s your personal tax return, a Business Activity Statement (BAS), or another report the ATO is expecting, those deadlines are there for a reason.
The ATO calculates these penalties using a system of penalty units. For the 2023–24 financial year, one penalty unit is worth $313. How many units you cop depends on the size of your business and just how late you are. A small business lodging something 1 to 28 days late will get hit with one penalty unit, but that can jump to five units if you’re over 112 days overdue.
The easiest way to picture it is like an overdue library book. The longer you take to bring it back, the bigger the fine gets. The ATO works on the same logic, with penalties ramping up over time to encourage everyone to get their documents in promptly.
This diagram shows how the ATO’s financial consequences are structured, with penalties and interest being their main tools.
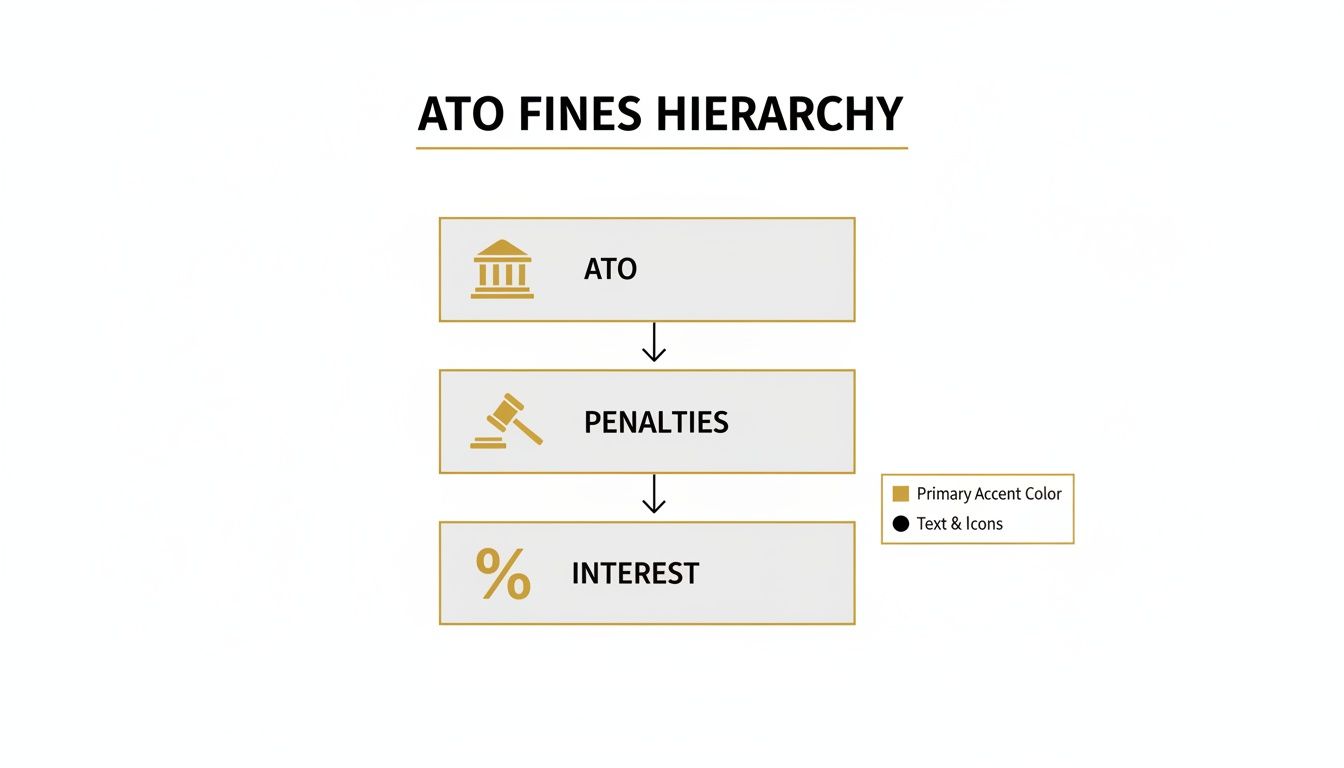
This hierarchy makes it crystal clear that penalties and interest are the two key levers the ATO pulls to enforce compliance and claw back revenue.
Penalties for Incorrect Information
The second big category of penalties is for making a false or misleading statement. This is what happens when you provide dodgy information that leads to you paying less tax than you should have, creating what’s known as a tax shortfall. When this happens, the ATO gets very interested in your behaviour and how much care you took.
The penalties are tiered, based on your conduct. They range from an honest mistake all the way up to outright deception.
- Failure to Take Reasonable Care: This is the lowest level of blame. It’s like making a typo on a crucial exam—an unintentional error, but one that still has consequences. Maybe you misread the instructions or just messed up a calculation, even though you were trying to do the right thing.
- Recklessness: This is a big step up. It's like guessing an answer on that exam when you knew you should have studied. You were aware of a risk that your statement was wrong but decided to push on anyway, ignoring that risk completely.
- Intentional Disregard: This is the most serious offence and is treated as such. It’s the equivalent of knowingly cheating on the exam. You were fully aware of your tax obligations but deliberately chose to ignore them to get a better financial outcome for yourself.
The key takeaway here is that your attitude towards your tax obligations matters—a lot. The ATO draws a very thick line between a taxpayer who makes a genuine mistake and one who knowingly breaks the law.
The penalty is worked out as a percentage of the tax shortfall. This is where it gets interesting, as your behaviour directly impacts the penalty rate.
ATO Penalty Rates For False Or Misleading Statements
Here’s a quick rundown of the base penalty rates the ATO applies based on a taxpayer's behaviour, before any reductions for coming forward voluntarily.
| Type Of Behaviour | Base Penalty Rate | Common Example |
|---|---|---|
| Failure to take reasonable care | 25% of the shortfall | Accidentally claiming a deduction you weren't entitled to after misinterpreting the rules. |
| Recklessness | 50% of the shortfall | Claiming large work expenses without any receipts, knowing you couldn't prove them if asked. |
| Intentional disregard | 75% of the shortfall | Deliberately hiding cash income to reduce your reported profit and pay less tax. |
This sliding scale shows the powerful incentive the ATO gives taxpayers to be proactive and honest. Owning up to a mistake is always treated far more favourably than waiting for them to find it.
For example, the 25% penalty for failing to take reasonable care can be significantly reduced if you voluntarily tell the ATO about the mistake before they start an audit. To get a better sense of how the numbers work, you can find out more about how these penalty tax rates apply.
How Interest Charges Can Amplify Your Tax Debt
Penalties for late lodgements or incorrect statements are just one part of the financial pressure the Australian Taxation Office (ATO) can apply. Often, the bigger threat to your finances comes from interest charges, which can quietly transform a manageable tax debt into an overwhelming one.
When you're dealing with the ATO, time truly is money.
Ignoring a tax shortfall is like leaving a small leak in your plumbing unchecked. At first, it’s a minor nuisance, but over time, the compounding damage can become incredibly expensive. The ATO applies two main types of interest to unpaid tax liabilities, each designed for a different scenario but both serving the same purpose: to compensate the government for the delay in receiving what it's owed.
These charges aren’t designed to be punitive in the same way a penalty is. Instead, they function more like interest on a loan, making sure the value of the tax debt isn't eroded by the time it takes for you to finally pay it.
Understanding the General Interest Charge
The most common interest you’re likely to encounter is the General Interest Charge (GIC). This gets slapped on pretty much any unpaid tax amount, including income tax, Business Activity Statement (BAS) debts, and even penalties themselves. The GIC rate is updated quarterly and is set deliberately higher than typical savings accounts to discourage you from delaying payment.
Think of the GIC as the ATO’s version of a high-interest credit card. The moment your tax payment is overdue, the GIC starts ticking. Critically, it compounds daily. This means every single day, interest is calculated not just on the original debt, but on all the interest that has already piled up. This daily compounding is what allows a tax debt to spiral out of control so quickly.
For instance, a $5,000 tax shortfall left unpaid for a year can balloon significantly, adding hundreds or even thousands of dollars to what you originally owed, depending on the GIC rate at the time. It’s a harsh lesson in how procrastination can be the most expensive decision a taxpayer can make.
What Is the Shortfall Interest Charge
The second type of interest is the Shortfall Interest Charge (SIC). This one is more specific. It applies when your tax bill goes up because of an amendment to a previous assessment. For example, if the ATO audits your tax return from two years ago and finds you under-reported your income, SIC is applied to that difference.
The goal of SIC is to compensate the government for the time it was without the funds you should have paid in the first place. The clock starts ticking from the due date of the original tax return and stops the day before the notice of your amended assessment is issued.
The key difference is that the SIC rate is lower than the GIC rate. It’s also calculated on a simple interest basis, not compounding. This reflects the fact that you may not have even known about the shortfall until the ATO pointed it out.
Despite the lower rate, SIC still drives home the importance of getting your tax returns right the first time. It’s a financial reminder that even honest mistakes have a cost, reinforcing the need for careful record-keeping and due diligence.
A common question we get is whether these charges can be claimed as a deduction. Understanding whether interest charged by the ATO is deductible is vital for managing the full financial impact. Ultimately, both GIC and SIC are powerful tools that highlight a core principle of the Australian tax system: timely and accurate payment is non-negotiable.
Common Mistakes That Trigger ATO Penalties
It’s one thing to understand the theory behind tax fines, but it’s another to see just how easily everyday slip-ups can land you with a penalty notice from the Australian Taxation Office (ATO). These aren't just for complex evasion schemes; they're for relatable, common errors that can catch even the most diligent person or business off guard.
Think of your tax obligations like regular car maintenance. You can ignore the small, routine checks—like lodging on time or keeping good records—but eventually, you're heading for a major, expensive breakdown. The ATO's penalty system works the same way, penalising oversights that might seem minor at first but which undermine the integrity of the whole system.
And these fines aren't just arbitrary punishments. They are a critical part of how the government collects Australia’s staggering $801.7 billion in tax revenue for the 2023-24 financial year. That figure is up 6.1% from the previous year and represents a massive 30.0% of Australia's GDP, which is why the ATO takes compliance so seriously. You can dive deeper into the numbers on the Australian Bureau of Statistics website.
Forgetting Key Lodgement Deadlines
This is probably the most common—and most avoidable—mistake of all. Life gets busy, and it's all too easy to let tax paperwork slide to the bottom of the to-do list. But in the eyes of the ATO, deadlines for individual tax returns and Business Activity Statements (BAS) are non-negotiable.
A classic example we see is the sole trader swamped with work who misses their quarterly BAS deadline. They figure they'll just catch up next quarter. But by then, a Failure to Lodge (FTL) penalty has already been automatically applied. A simple act of procrastination has turned into a direct financial cost, with interest charges sure to follow.
Under-Reporting Your Income
With the rise of the gig economy and side hustles, tracking every single dollar you earn has become a lot more complicated. A lot of people mistakenly believe that small amounts of cash-in-hand work or income from a hobby-turned-business don’t need to be declared. That’s a dangerous assumption.
Take a graphic designer who picks up a few small cash jobs to supplement her main salary. She doesn't declare the extra $5,000 on her tax return, thinking it's too minor to matter. A couple of years down the track, an ATO data-matching audit flags a discrepancy. This leads directly to a penalty for making a false or misleading statement, plus a bill for the unpaid tax with interest.
Common sources of forgotten income include:
- Freelance or side-gig earnings
- Cash payments for goods or services
- Rental income from an investment property
- Interest earned from bank accounts
- Dividends from shares
The ATO’s data-matching technology is incredibly sophisticated. It cross-references information from banks, employers, and other agencies. The chances of undeclared income going unnoticed are slimmer than ever.
Over-Claiming Deductions Without Proof
Claiming every legitimate deduction you're entitled to is just smart tax management. But every single claim must be backed up by evidence. The "I'll just estimate it" approach is a surefire way to get a penalty. You need records to prove you spent the money and to show how the expense directly relates to earning your income.
Picture a sales rep who claims the maximum 5,000 kilometres for work-related car travel using the cents-per-kilometre method but keeps no logbook or diary to justify it. When the ATO reviews the claim, they disallow the whole thing because there's no proof it was business-related. The result? A tax shortfall, a penalty for failing to take reasonable care, and a nasty bill for the outstanding amount plus interest.
Failing to Report Capital Gains
Another frequent misstep is forgetting about Capital Gains Tax (CGT). This tax applies whenever you sell an asset—like shares, an investment property, or even cryptocurrency—for a profit. Many people either don’t realise CGT is a factor or simply fail to keep the records needed to calculate it correctly.
For instance, an investor sells a parcel of shares they bought years ago for a tidy profit but completely omits the capital gain from their tax return. Maybe they just forgot, or perhaps they didn't understand their obligation. As soon as the ATO gets data from the share registry, the omission sticks out like a sore thumb, triggering an amended assessment and a shortfall penalty. It’s absolutely essential to keep detailed records of purchase and sale prices and dates for all your assets.
Proactive Strategies For Avoiding Tax Fines
Knowing the risks tied to Australian tax fines is one thing, but the real power comes from building a system that stops them from ever happening in the first place. The best way to handle the Australian Taxation Office (ATO) is to be so well-organised that you sidestep any potential issues from the get-go.
Think of it as preventative maintenance for your financial health. A few key habits can build a strong defence against penalties and interest, saving you a world of stress and money down the line. It's about shifting from a reactive mindset of fixing problems to a proactive one of preventing them.
Cultivate Excellent Record-Keeping Habits
Meticulous record-keeping is the absolute bedrock of tax compliance. Without accurate, organised records, it’s nearly impossible to prepare a correct tax return or defend your position if the ATO comes knocking. This is your primary evidence against any claim of negligence.
These days, that means going digital. That old shoebox overflowing with faded receipts is a recipe for disaster. Instead, get on board with accounting software or even simple cloud storage to keep digital copies of absolutely everything.
Key records you must maintain include:
- Proof of Income: All your invoices, bank statements, and summaries from platforms like Uber or Airbnb.
- Proof of Expenses: Digital receipts, invoices, and bank transaction details for every single deduction you claim.
- Asset Records: Paperwork showing the purchase and sale price of assets like property, shares, or crypto. This is crucial for calculating capital gains correctly.
Master Your Deadlines
Missing a lodgement deadline is one of the quickest ways to cop an automatic Failure to Lodge (FTL) penalty. The fix is simple but incredibly effective: get organised with a calendar.
Set multiple reminders for key dates, like your income tax return and quarterly Business Activity Statement (BAS) lodgements. If you use a tax agent, they’ll often manage these for you, but it’s still on you to get them the right info on time. Building a solid routine can help you avoid overdue tax fines in 3 easy steps.
The Power of Voluntary Disclosure
So, what happens if you find a mistake? The single best thing you can do is tell the ATO before they find out themselves. This is called making a voluntary disclosure, and it’s a powerful tool for slashing penalties.
Coming forward about an error shows the ATO you’re making a genuine effort to get things right. In many cases, especially for mistakes involving a 'failure to take reasonable care', penalties can be cut by up to 80% or even waived entirely.
Think of it like owning up to a mistake to get a second chance. It’s far better to control the narrative and prove your honesty than to wait for an audit to uncover the problem, which almost guarantees a much harsher penalty.
View Professional Advice as an Investment
Hiring a tax professional shouldn't be seen as just another cost. It’s a strategic investment in managing your risk. A qualified tax agent or accountant does more than just lodge your return; they provide a vital layer of protection against much bigger losses from fines and interest. They are always up-to-date on complex tax laws and can spot red flags you’d easily miss.
This proactive approach is crucial. It’s not just about saving yourself money, but about respecting the system. The ATO’s enforcement has evolved to protect the tax revenue that has averaged 21.9% of Australia’s GDP since 1972. By exploring the various ways to minimize your tax liability, you’re not only protecting your bottom line but also playing your part in maintaining the system's integrity.
What To Do If You Receive An ATO Penalty Notice
That official-looking envelope from the Australian Taxation Office (ATO) or a notification in your myGov inbox can make your heart skip a beat. Your first instinct might be to panic—or worse, shove it in a drawer and forget about it. But trust me, the best approach is a calm, methodical one.
Taking smart, immediate action can completely change the outcome. The single biggest mistake you can make is putting that notice aside. It won't go away on its own; in fact, ignoring it just means accumulating interest and inviting more serious compliance action from the ATO.
Your First Steps After Receiving A Notice
Before you do anything else, you need to understand exactly what the ATO is telling you. Don't just look at the dollar figure and despair. Read every single line. An ATO penalty notice is a formal document explaining why the penalty was applied, the exact amount, and the deadline for you to either pay or respond.
Once you’ve got a clear picture, your next job is to pull together all your relevant documents. This isn’t just about finding receipts; you’ll need a complete file, which could include:
- Bank statements and transaction records for the period in question.
- Receipts and invoices that relate to that tax year.
- Any previous letters or communication you’ve had with the ATO.
- Your own business ledgers or data from your accounting software.
Having all this information organised and at your fingertips is absolutely crucial. It allows you to properly assess the situation and build your case if you decide the penalty is unfair.
Understanding Your Options For A Response
After you’ve reviewed the notice and cross-checked it with your own records, you have a few ways forward. If the penalty is legitimate and you agree with the ATO's assessment, the simplest path is to pay the amount by the due date. This stops any further interest from being tacked on.
But an ATO penalty isn't always the final word. You absolutely have the right to object or ask the ATO to cancel or reduce it. This formal process is called requesting a remission. Getting an overdue tax return penalty is a very common reason people find themselves in this spot, but knowing your rights is key. You can learn more about how to manage these specific penalties and what your options for remission look like.
A request for remission isn't just about disagreeing with a fine. It’s about presenting a fair and reasonable case, supported by evidence, that explains why the penalty should be reconsidered.
The ATO can grant a full or partial remission, especially if you can show there were extenuating circumstances. These are situations that were genuinely outside your control, like a serious illness, a natural disaster that wiped out your records, or even relying on incorrect advice you received directly from the ATO.
Your compliance history also plays a huge role here. If you have a solid track record of lodging and paying on time, the ATO is often much more willing to show some leniency for a one-off mistake. If you present your case clearly and respectfully, you can turn a moment of high stress into a manageable process where you actually have a say in the outcome.
Common Questions About Tax Fines
Let's tackle some of the most common and practical questions taxpayers have when they’re facing a penalty from the ATO. These quick answers should give you the clarity you need to handle your obligations with confidence.
Can The ATO Completely Cancel a Fine?
Yes, absolutely. The Australian Taxation Office (ATO) has the power to completely cancel, or ‘remit’, a penalty. This isn't something they do lightly, but it often happens if you can show there were extenuating circumstances that stopped you from complying. Think major life events like a natural disaster or a serious illness.
Your track record with the ATO really matters here. Having a strong compliance history—meaning you’ve consistently lodged and paid on time in the past—massively improves your chances. It’s always worth putting forward a well-argued case for remission.
What Happens If I Can't Afford to Pay?
If you can't afford to pay a fine upfront, burying your head in the sand is the worst thing you can do. The ATO is actually quite willing to work with taxpayers who are genuinely experiencing financial hardship.
The key is to be proactive. You can contact them to discuss setting up a payment plan, which breaks the debt down into smaller, more manageable instalments over an agreed period. Reaching out shows you’re taking the debt seriously, which goes a long way.
Does My Tax Agent Take Responsibility?
This is a common point of confusion, but the answer is clear: you are ultimately legally responsible for the accuracy of your own tax return. That holds true even if a registered tax agent prepared and lodged it for you. While your agent has a professional duty of care, the liability for any tax shortfall or penalty rests squarely with you.
If a penalty was slapped on because your agent was reckless or failed to take reasonable care, you might have grounds to seek compensation from them. However, you still have to settle your debt with the ATO first.
What Are The Consequences of Ignoring a Fine?
Ignoring an ATO fine is a fast track to bigger problems. The situation escalates quickly. First, the debt will start growing every single day due to the General Interest Charge (GIC). Then, the ATO will begin firm recovery action.
This isn't just a threatening letter. We're talking about serious measures that can include:
- Garnisheeing your wages or taking money directly from your bank account.
- Issuing a Director Penalty Notice to a company director, making them personally liable.
- Kicking off legal proceedings to recover the debt through the courts.
Navigating the complexities of ATO penalties can be stressful, but you don't have to do it alone. The experts at Australia Wide Tax Solutions are here to provide clear guidance and help you manage your tax obligations effectively. If you've received a penalty notice or need help with overdue returns, get in touch with our team today.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
Introduction
Managing your tax obligations can be complex and sometimes daunting as a business owner. One area that often catches businesses off-guard is the failure to lodge on-time penalties. This penalty can have significant financial consequences if not handled properly, making it crucial for businesses to understand the ins and outs of this regulation.
- Introduction
- What is the Failure to Lodge on Time Penalty?
- Who is Subject to the Failure to Lodge on Time Penalty?
- How Much is the Failure to Lodge on Time Penalty?
- Consequences of the Failure to Lodge on Time Penalty
In this comprehensive blog post, we'll dive deep into the failure to lodge on-time penalty, avoid late tax lodgements, exploring what it is, how it works, and the potential implications for your business. We'll also provide practical tips and strategies to help you stay on top of your tax lodgment requirements and avoid this penalty altogether.
What is the Failure to Lodge on Time Penalty?
Avoid Late Tax Lodgments, the failure to lodge on time penalty, is a financial penalty imposed by the Australian Taxation Office (ATO) on businesses that fail to submit their tax returns or other required lodgments by the due date. This penalty is designed to encourage businesses to fulfill their tax obligations promptly, as late or missing lodgments can significantly impact the government's ability to collect revenue and maintain the integrity of the tax system.
The penalty amount can vary depending on several factors, including the type of lodgment, the delay length, and the business size. Generally, the penalty starts at a base amount and then increases the longer the lodgment is overdue.
Who is Subject to the Failure to Lodge on Time Penalty?
The failure to lodge on time penalty applies to a wide range of businesses and tax obligations, including:
- Income Tax Returns: Businesses, including sole traders, partnerships, and companies, are required to lodge their income tax returns by the due date, which is typically the 15th of October for most businesses.
- Business Activity Statements (BAS): Businesses that are registered for Goods and Services Tax (GST) must lodge their BAS forms on a regular basis, typically monthly or quarterly, depending on their turnover.
- Fringe Benefits Tax (FBT) Returns: Businesses that provide fringe benefits to their employees must lodge an FBT return by the due date, which is usually the 21st of May.
- Other Lodgments: The penalty may also apply to other tax-related lodgments, such as the Taxable Payments Annual Report, PAYG Withholding Annual Report, and Superannuation Guarantee Charge Statement.
It's important to note that the failure to lodge on time penalty applies to both large and small businesses, so all businesses must be aware of their tax lodgment obligations and deadlines.
How Much is the Failure to Lodge on Time Penalty?
The exact amount of the failure to lodge on time penalty can vary depending on several factors, but it generally follows these guidelines:
- Base Penalty Amount: The base penalty amount for a failure to lodge on time is $222 for individuals and $1,110 for entities (such as companies, trusts, and partnerships).
- Penalty Increase: The penalty increases the longer the lodgment is overdue. For each 28-day period (or part thereof) that the lodgment is late, the penalty increases by the base amount. For example, if a business is 35 days late in lodging a return, the penalty would be 2 x the base amount ($2,220 for an entity).
- Penalty Cap: The penalty is capped at 5 times the base amount, which equates to $5,550 for individuals and $27,750 for entities.
It's important to note that the failure to lodge on time penalty is in addition to any other penalties or interest charges that may apply, such as the general interest charge on any outstanding tax debt.
Consequences of the Failure to Lodge on Time Penalty
The failure to lodge on time penalty can have significant consequences for businesses, including:
- Financial Impact: The penalty can be a substantial financial burden, especially for smaller businesses. This can put a strain on cash flow and profitability, making it even more difficult to meet other tax and financial obligations.
- Damage to Reputation: The failure to lodge on time can be seen as a sign of poor business management or a lack of attention to compliance. This can damage a business's reputation, making it harder to secure financing, attract new customers, or maintain positive relationships with suppliers and other stakeholders.
- Increased Scrutiny from the ATO: Businesses that repeatedly fail to lodge on time may face increased scrutiny from the ATO, which could lead to more frequent audits, additional penalties, or even criminal charges in severe cases.
- Inability to Claim Tax Deductions: Businesses that fail to lodge their tax returns on time may be unable to claim certain tax deductions or offsets, further increasing their tax liability.
- Potential Legal Consequences: In extreme cases, failing to lodge on time can lead to legal consequences, such as a company's directors being held personally liable for the business's tax debts.
Strategies to Avoid the Failure to Lodge on Time Penalty
To avoid the failure to lodge on time penalty, businesses should implement the following strategies:
- Understand Your Tax Obligations: Familiarize yourself with the various tax lodgment requirements and deadlines that apply to your business. This includes income tax returns, BAS forms, FBT returns, and any other relevant lodgments.
- Develop a Tax Lodgment Calendar: Create a comprehensive calendar outlining your business's tax lodgment deadlines. This will help you stay organized and ensure you don't miss any important due dates.
- Prioritize Tax Lodgments: Make tax lodgments a top priority in your business operations. Set reminders, allocate resources, and ensure your team knows the importance of meeting these deadlines.
- Leverage Technology and Automation: Utilize accounting software, tax preparation tools, and other digital solutions to streamline your tax lodgment process. Automation can help reduce the risk of human error and ensure that your lodgments are submitted on time.
- Communicate with Your Tax Advisor: Maintain open communication with your accountant, tax agent, or other tax professionals. They can provide valuable guidance on your tax obligations, help you navigate any changes or updates, and assist in the lodgment process.
- Request Extensions if Necessary: If you anticipate that you cannot lodge a return or other document by the due date, consider requesting an extension from the ATO. This can help you avoid the failure to lodge on time penalty, but it's essential to ensure that you meet the extension requirements.
- Address Lodgment Issues Promptly: Act quickly to rectify the situation if you miss a deadline. Contact the ATO, explain the circumstances, and work to lodge the outstanding documents as soon as possible. This can help mitigate the potential penalties and other consequences.
Conclusion
Failing to lodge on time penalty is a serious issue that businesses cannot overlook. By understanding the penalty and its consequences and implementing effective strategies, businesses can remain compliant with their tax obligations and avoid the financial and reputational damage resulting from late or missing lodgments.
Remember, staying on top of your tax lodgment requirements is not only a legal requirement but also a crucial aspect of sound financial management and business success. By taking a proactive approach and prioritizing tax compliance, you can protect your business and focus on achieving your long-term goals.
If you have any further questions or need assistance navigating the complexities of the failure to lodge on-time penalty, don't hesitate to contact a tax professional or the ATO for guidance.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
Foreign residents who purchase or sell Australian property face a different CGT regime than Australian residents — including the Foreign Resident Capital Gains Withholding (FRCGW) regime, which requires purchasers to withhold 15% of the sale price at settlement unless a clearance certificate is obtained. In 2026, these rules apply to all Australian property sales regardless of the vendor's tax residency for Australian purposes. Here is what foreign purchasers and vendors need to know about CGT in 2026.
Foreign Resident Capital Gains Withholding (FRCGW)
From 1 January 2025, the FRCGW withholding rate increased to 15% of the gross sale price and the $750,000 threshold was removed — meaning withholding now applies to ALL Australian property sales where the vendor cannot produce a valid ATO clearance certificate, regardless of the value of the property.
- Australian resident vendors: Must obtain an ATO clearance certificate (free, applied for online) to avoid the 15% withholding. Without it, the purchaser is required by law to withhold 15% and remit it to the ATO.
- Foreign resident vendors: The 15% withholding is generally required. Vendors may apply to the ATO for a variation if their actual CGT liability is less than 15% of the sale price.
- Purchasers: Are required to check vendor residency status and withhold if no clearance certificate is provided. Failure to withhold creates a liability for the purchaser.
CGT Rules for Foreign Residents Selling Australian Property
Foreign residents of Australia are subject to Australian CGT on "taxable Australian property" — which includes:
- Direct interests in Australian real property (residential or commercial)
- Indirect interests where more than 50% of the value of an entity is attributable to Australian real property
- Business assets of an Australian permanent establishment
Unlike Australian residents, foreign residents cannot access the 50% CGT discount on gains accrued after 8 May 2012. If a property was held before that date, there may be a partial discount available for gains accrued in the pre-2012 period.
Foreign Investment Surcharges on Purchase
Foreign persons (as defined by the Foreign Acquisitions and Takeovers Act) must obtain FIRB approval before purchasing Australian residential real estate. Additional state-level surcharges apply on top of standard stamp duty:
- NSW: 8% surcharge purchaser duty + 4% land tax surcharge
- VIC: 8% foreign purchaser additional duty + 2% absentee owner surcharge
- QLD: 7% additional foreign acquirer duty
- WA: 7% foreign buyers duty
Frequently Asked Questions
What is the ATO clearance certificate and how do I get one?
An ATO clearance certificate confirms to the purchaser that the vendor is an Australian resident for tax purposes and that withholding is not required. Australian resident vendors should apply online through the ATO's website as soon as a sale is imminent — processing takes up to 28 days. The certificate is valid for 12 months. If you do not have a clearance certificate at settlement, the purchaser must withhold 15% of the sale price.
Can foreign residents access the CGT main residence exemption?
No. From 9 May 2017, foreign residents are no longer entitled to the main residence CGT exemption when selling Australian property — even if they lived in the property as their home while an Australian resident. There is a transitional rule for properties held before 9 May 2017 that were sold before 30 June 2020. After that date, no exemption applies.
Selling Australian property as a foreign resident or purchasing from a foreign vendor? Contact AWTS for specialist CGT and withholding tax advice.