

What a Double Tax Agreement Is and Why Australia Has Them
The Core Purpose of Tax Treaties
At their heart, these treaties solve one key problem: figuring out which country gets the first bite of the tax cherry for different types of income. A DTA will lay out clear rules for common situations, like:- Employment Income: Clarifying where your salary should be taxed if you’re working temporarily in another country.
- Business Profits: Defining how a multinational company's profits are split and taxed between the nations it operates in.
- Dividends and Royalties: Setting caps on the "withholding tax" a country can charge on payments sent to a resident of the other treaty country.
A double tax agreement doesn't mean you pay no tax. It just makes sure you don’t pay it twice on the same income. It provides a clear pathway for either claiming a credit for foreign tax you’ve already paid or, in some cases, making certain income exempt from Australian tax altogether.
Fostering Certainty and Cooperation
This framework is essential for everyone, from an Australian expat working in London to a local business importing goods from the United States. It's why Australia has worked to establish Double Tax Agreements with over 40 countries, creating a solid network that supports global trade and mobility. Take the treaty with the US, for example. It allows American citizens in Australia to use mechanisms like the Foreign Tax Credit to offset their tax liabilities, stopping their income from being taxed by both the ATO and the IRS. You can find more detail on how specific treaty rules work for expats at Taxes for Expats. Ultimately, these agreements provide the financial certainty people and companies need to operate confidently across borders, knowing their tax obligations are clear, fair, and predictable.How Australian Tax Treaties Provide Relief
The Power of a Tax Credit: FITO
The most common way treaties provide relief is through the Foreign Income Tax Offset, or FITO. It’s a bit like getting a store credit for the tax you've already paid somewhere else. If you've paid tax to another country on your foreign income, Australia lets you use that amount to reduce your local tax bill. This ensures you don’t get hit with the full rate of tax in both countries. Instead, you effectively just "top up" your tax to the Australian rate if it's higher. If the foreign tax rate was the same or more, you often won't pay any extra Australian tax on that income at all. Here’s how it plays out:- Scenario: You’re an Aussie tax resident and earned $10,000 in dividends from a UK company.
- Foreign Tax Paid: The UK government withholds $1,500 in tax (a 15% rate, as per the treaty).
- Australian Tax: Here in Australia, that $10,000 income might create a tax liability of $3,000 (assuming a 30% marginal rate).
- Applying FITO: You claim a $1,500 FITO, which directly cuts down your Australian tax bill.
Exemption Method: A Different Approach
While FITO is the workhorse, some treaties use a different tool called the exemption method. This is a much more straightforward approach. Put simply, certain foreign income is just not taxed in Australia, period—as long as specific conditions in the treaty are met. This is often used for particular types of employment income or business profits where the treaty gives the other country the sole right to tax that income. It's less common than FITO but is a crucial feature in some of our key agreements.At its heart, a double tax agreement Australia is all about assigning taxing rights. The treaty decides if Australia or the other country gets first dibs on taxing your income, then provides a mechanism like FITO to clean up any overlap.
Lowering Withholding Tax Rates
Another vital job of these treaties is to slash withholding tax rates. This is a type of tax that countries charge on 'passive' income—like dividends, interest, and royalties—that gets paid to someone who isn't a resident. Without a treaty, a country might slap a withholding tax of 30% or more on dividends paid to an Australian resident. A tax treaty almost always puts a cap on this, often setting it at 15% for dividends and 10% for interest and royalties. For non-residents earning income from Australia, understanding these capped rates is critical. We cover this in more detail in our guide on non-resident tax rates in Australia. These reduced rates are a massive carrot for cross-border investment. They make it far more attractive for foreigners to invest in Aussie companies and for Australians to invest overseas, creating a much healthier global economic environment. By providing certainty and reducing tax friction, tax treaties directly grease the wheels of international trade and investment.Exploring Australia's Key Tax Treaty Partnerships
The United States Treaty: A Unique Case
The treaty with the US is arguably one of the most complex, largely due to a single, powerful provision: the 'saving clause'. This is a standard feature in most American tax treaties, and its impact is huge.The saving clause essentially gives the US the right to tax its citizens and Green Card holders as if the treaty didn't exist. This means a US expat living in Australia still has to file US tax returns on their worldwide income. They then rely on mechanisms like the Foreign Tax Credit to avoid being taxed twice on the same dollar.This clause creates some real headaches, particularly when it comes to Australian superannuation. While we see super as a tax-friendly retirement fund, the IRS often views it through a different lens. They might try to tax its growth each year or tax the final payout, creating a compliance nightmare for US citizens here. It's a classic example of why you can't just assume a treaty protects you.
The United Kingdom: A Focus on Pensions and Property
Given the deep historical and family ties between our nations, the UK-Australia treaty is one of the most frequently used. It’s particularly helpful for expats, retirees, and property investors, with a special focus on pensions and capital gains. The agreement lays out clear rules for who gets to tax different types of pension payments, whether they're government service pensions or private ones. It also has specific articles on capital gains tax, clarifying how gains from selling property or shares are handled based on where the asset is and where you live.The New Zealand Treaty: Trans-Tasman Simplicity
The agreement with New Zealand is all about making life easier for the thousands of people and businesses that operate across the Tasman. It’s designed to reflect the incredibly close economic and personal links we share. A few key features really stand out:- Simplified Residency Rules: The treaty’s tie-breaker rules are built for the common scenario of people moving back and forth for work.
- Clear Business Profit Rules: It provides straightforward guidelines for businesses operating in both countries, making sure profits are taxed fairly without being hit twice.
- Entertainers and Athletes: There are even specific articles for visiting entertainers and sportspersons, a nod to the constant cultural exchange between us.
China: A Gateway for Investment and Trade
As one of our biggest trading partners, the treaty with China is a cornerstone of Australia's economic strategy. The main goal of this double tax agreement Australia maintains is to smooth the path for investment by lowering tax barriers. It achieves this by setting firm limits on the withholding tax that can be charged on dividends, interest, and royalties flowing between the two countries. This creates certainty and makes cross-border business far more predictable. The treaty also includes strong provisions for sharing tax information, helping both the ATO and China's State Taxation Administration stamp out tax evasion.Comparing Key Provisions in Australian DTAs
Looking at these treaties side-by-side really brings their differences to life. While the full texts are dense, comparing the standard withholding tax rates on cross-border payments gives a great snapshot of how each one works. These rates on dividends, interest, and royalties are critical, as they directly impact the flow of investment. For instance, the US-Australia treaty sets specific reductions to encourage bilateral trade. For a deeper dive into how these agreements shape economic policy, check out this detailed KPMG report. Here’s a simplified table comparing the standard, treaty-limited withholding tax rates.| Provision | United States | United Kingdom | New Zealand | China |
|---|---|---|---|---|
| Dividends | 15% (can be 0% or 5%) | 15% (can be 0%) | 15% (can be 0% or 5%) | 15% |
| Interest | 10% | 10% | 10% | 10% |
| Royalties | 5% | 5% | 5% | 10% |
Figuring Out Your Tax Residency with Tie-Breaker Rules
Your tax residency status is the absolute bedrock of how a double tax agreement applies to you. Think of it as the master switch that determines where your tax obligations lie. If you get this wrong, you can find yourself in a world of compliance headaches with the Australian Taxation Office (ATO). Before any treaty even enters the conversation, Australia has its own domestic rules for figuring out if you're a resident for tax purposes. These are always the ATO's first point of reference.Australia's Four Residency Tests
To be considered an Australian tax resident, you only need to pass one of these four tests:- The Resides Test: This is the main one. It’s a common-sense test that looks at your overall behaviour and where your life is genuinely based. It considers things like your physical presence, your intentions, and where your family and financial ties are.
- The Domicile Test: If your permanent home—your legal domicile—is in Australia, you're a resident. The only way around this is if you can prove to the ATO that your permanent place of living is genuinely outside Australia.
- The 183-Day Test: This one is just about counting days. If you’re physically in Australia for more than half the financial year (183 days), you're likely a resident. The exception is if your usual home is overseas and you have no intention of moving here.
- The Commonwealth Superannuation Test: This is a specific one for Australian Government employees working overseas at places like embassies, along with their spouses and children.
When Both Countries Think You're Theirs
Let's say you're an Aussie citizen who's taken a two-year contract in the UK. You still satisfy Australia's domicile test because your permanent home is here, but you also meet the UK's residency tests because you're living and working in London. Now you have a problem: both the ATO and the UK's HMRC believe they have the right to tax your entire worldwide income. This is precisely when the 'tie-breaker' rules in the Australia-UK double tax agreement kick in. They provide a clear, step-by-step checklist to resolve the conflict and name a single country of residence for the purposes of the treaty.Tie-breaker rules are a cascading series of questions designed to find the one country you have the strongest connection to. You work through them in order, stopping as soon as one of the tests gives a clear answer.
The Tie-Breaker Checklist Explained
The tests are applied one after the other. You only go to the next question if the one before it doesn't solve the problem.1. Where is your permanent home?
This looks at where you have a permanent home available to you. If you only have one in Australia, then Australia is your tax residence. If you have a permanent home in both countries (or in neither), you have to move on to the next test.2. Where is your centre of vital interests?
This one’s a bit more personal. It digs into where your life is more deeply rooted by looking at where your personal and economic ties are stronger. This includes your family and social connections, your business interests, and even your political and cultural activities.3. Where is your habitual abode?
If your vital interests are split down the middle, the treaty then looks at where you have a "habitual abode"—which is just a fancy way of saying "where do you usually live?". It’s about the frequency and length of your stays in each country.4. What is your citizenship?
If all else fails and you spend equal time in both countries, your citizenship (or nationality) becomes the final deciding factor. Proving your residency status is a big deal, and it usually requires official paperwork. Knowing how to get a tax residency certificate in Australia is often a vital step, as this document serves as formal proof for tax authorities overseas.How DTAs Impact Your Superannuation and Foreign Pensions
For anyone who has lived and worked across different countries, sorting out your retirement funds can feel like navigating a maze of tax rules. A double tax agreement Australia has in place is the key to simplifying this, especially when it comes to your superannuation and any foreign pensions you might have. These agreements are designed to set clear rules on which country gets the right to tax your retirement income. The goal is to stop you from being unfairly taxed by both the country you live in and the country where your pension or super fund is based. The rules can be surprisingly different, often depending on whether you're taking regular pension payments or a one-off lump sum.Lump Sums vs. Pension Payments
As a general rule, most tax treaties give the right to tax ongoing, regular pension payments to the country where you are living at the time you receive them. So, if you're a resident in the UK and drawing a pension from an Australian fund, the Australia-UK DTA typically means the UK gets the primary right to tax those payments. Lump-sum withdrawals are a different story. Many treaties state that a lump sum, particularly from a super fund, can be taxed by the source country—that is, the country where the fund is held. This distinction is absolutely vital when you're planning for retirement. You can find out more about how this works if you are departing Australia and accessing your superannuation. This visual helps to break down how the money flows and where the tax hit happens.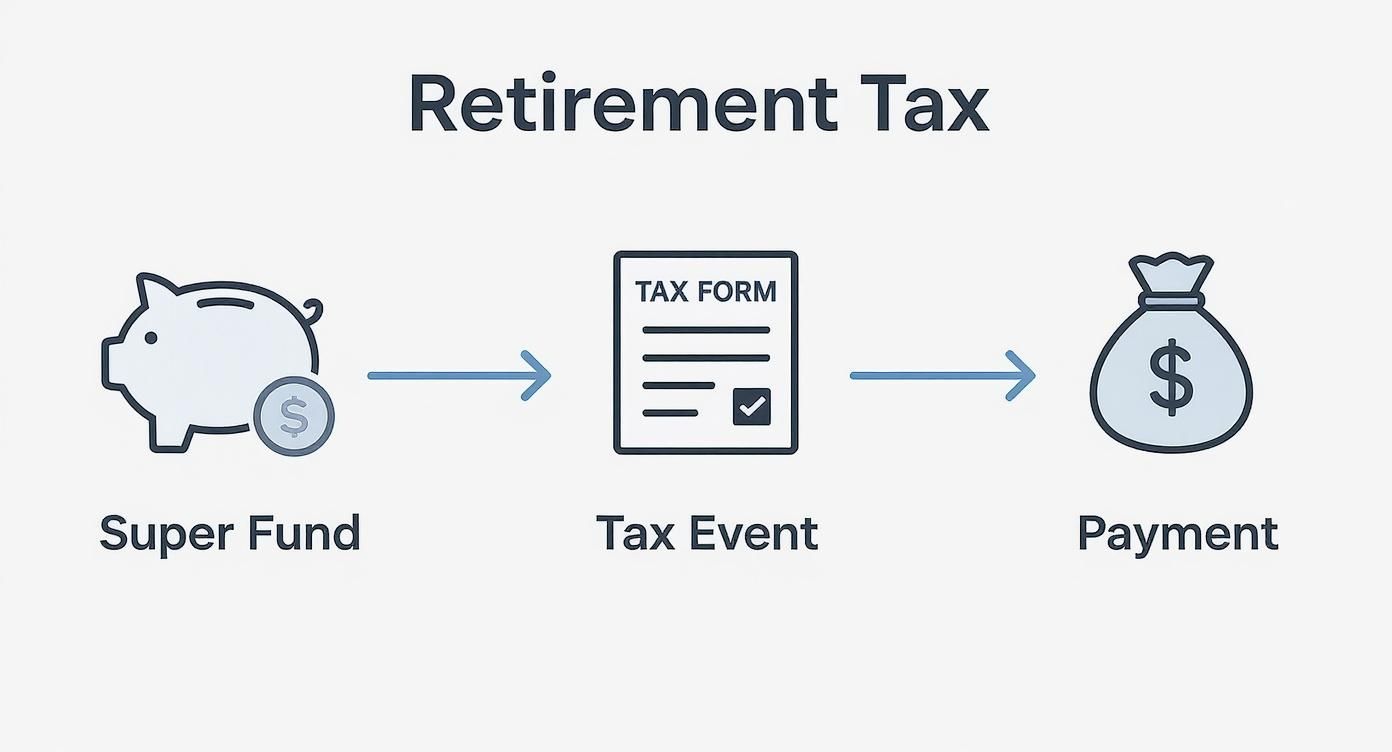
The Unique Case of Australian Superannuation
One of the biggest traps for expats is assuming every country treats superannuation the same way. Many don't. The United States, for instance, often doesn't recognise an Australian super fund as a "pension" in the same way its own treaties define the term. This mismatch can cause some seriously unexpected tax problems. A US citizen living in Australia might suddenly find the IRS wants to tax the earnings inside their super fund each year, even though that growth is tax-advantaged here in Australia. This happens because the US-Australia DTA has a 'saving clause', which essentially allows the US to tax its citizens as if the treaty didn't even exist for certain types of income.For global citizens, understanding the specific clauses within a DTA related to pensions and superannuation is not just a compliance task—it’s an essential part of protecting your retirement nest egg from surprise tax bills that can significantly erode your savings.It’s also crucial to remember that Australia's own super rules add another layer of complexity. For example, from 1 July 2025, earnings on super balances over $3 million will be taxed at 30%, a big jump from the usual 15%. This domestic policy can create even more complications when it interacts with foreign tax systems under a treaty. Ultimately, getting this right comes down to careful planning and a solid understanding of both Australian tax law and the specific double tax agreement Australia has with your other country.
A Practical Guide to Claiming Tax Treaty Benefits
Knowing a double tax agreement Australia has with another country can save you money is one thing. But knowing exactly how to claim those benefits when you lodge your tax return is where it really counts. This isn't just theory; it’s about taking practical steps to ensure you don’t pay a dollar more in tax than you legally have to. The whole process is quite methodical. It boils down to confirming you’re eligible, gathering the right paperwork, and filling out the correct sections of your Australian tax return. Get it right, and you can claim your rightful tax relief while staying on the right side of the Australian Taxation Office (ATO).Starting Your Claim Journey
Before you even touch a calculator, the first step is to confirm you actually qualify under the specific DTA. This means checking that you're an Australian tax resident and that the foreign income you’ve earned is covered by the treaty between Australia and the source country. Once you've ticked that box, it's time to gather your documents. The single most important piece of evidence is proof of the foreign tax you've already paid. This could be a payslip, a dividend statement, or an official tax assessment notice from the tax authority in the other country. You might also need to get a certificate of residency from the ATO. This is an official document that proves to the foreign tax office that you are indeed an Australian tax resident. It’s often the key to unlocking the reduced tax rates offered by the treaty in the first place.Calculating and Claiming the Foreign Income Tax Offset
By far the most common way to get the benefit of a tax treaty in Australia is by claiming the Foreign Income Tax Offset (FITO). This is a non-refundable tax credit that directly cuts down your Australian tax bill.Think of it like this: the ATO is giving you credit for the tax you’ve already handed over to another government, so you don't pay for it twice.Here’s the step-by-step process for claiming your FITO:
- Calculate Your Foreign Income: You'll need to convert all your foreign income and the foreign tax you paid into Australian dollars. Use the exchange rate that was in effect at the time you received the money.
- Determine Your FITO Limit: Your offset is capped. The ATO calculates a limit to make sure the credit you get isn’t more than the Australian tax you would have been liable for on that same income.
- Complete Your Tax Return: You must declare your total foreign income in the right spot (usually under "Foreign source income"). Then, you claim the FITO in the "Offsets" section of your tax return.
Case Study: An Australian Resident with UK Income Sarah is an Australian tax resident who received A$5,000 in dividends from a company in the UK. The UK-Australia DTA states that the maximum withholding tax on these dividends is 15%.This simple process stops her income from being taxed in full by two different countries. It ensures she ultimately pays the higher of the two countries' tax rates, which is the whole point of a double tax agreement Australia signs. It turns a complex piece of international law into a practical, money-saving step on your tax return.
- Foreign Tax Paid: The UK tax authority withholds A$750 (which is 15% of $5,000) before the money even gets to Sarah.
- Declare Income: On her Australian tax return, Sarah must declare the full A$5,000 as foreign income.
- Australian Tax Liability: Let's say Sarah's marginal tax rate is 32.5%. The Australian tax on this income would be A$1,625.
- Claim FITO: Sarah then claims a FITO of A$750—the exact amount of UK tax she already paid.
- Final Outcome: The FITO directly reduces her Australian tax bill. Instead of paying the ATO $1,625 on this income, she only has to pay A$875 ($1,625 - $750).
Answering Your Top Questions About Australian DTAs
When you start digging into the details of a double tax agreement in Australia, a few practical questions almost always come up. Let's tackle some of the most common ones we hear from our clients.Does a Tax Treaty Mean I Don't Have to Declare Foreign Income?
No, and this is a really common (and risky) misunderstanding. Being an Australian resident for tax purposes means you have a legal duty to tell the Australian Taxation Office (ATO) about your worldwide income. A DTA doesn't make that obligation disappear. What it does do is provide the mechanism—usually the Foreign Income Tax Offset (FITO)—to stop you from being taxed twice on the same dollar. You have to declare everything first, then you can claim a credit for the tax you’ve already paid overseas.What if a Foreign Company Pays Me While I'm Working in Australia?
If you are physically in Australia doing the work, that income is almost always considered Australian-sourced and is taxable right here. It doesn’t matter where your employer is based or which country's bank account the money lands in. A tax treaty will nearly always give Australia the first right to tax income earned from work done on its soil. The DTA's job is then to make sure the other country doesn't tax you on that same income, shielding you from that double hit.Key Takeaway: When it comes to employment income, your physical location while performing the work is the single most important factor in deciding who gets to tax you first.
How Can I Find Out if Australia Has a DTA with Another Country?
For the official, legally binding source, your best bet is the Australian Treasury website. The Treasury keeps the complete, up-to-the-minute list of every tax treaty, including the full text of each agreement. If you’re looking for more user-friendly summaries and practical guides on how these treaties work in the real world, the ATO website is also a fantastic resource.Getting your head around the fine print of a double tax agreement Australia has with another country isn't easy and requires specialist knowledge. At Australia Wide Tax Solutions, we guide individuals and businesses through their cross-border tax obligations with clarity and confidence. Get in touch with our expert tax accountants today.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
