

Understanding Your BAS Obligations
- Goods and Services Tax (GST): The 10% tax on most goods, services, and other items sold or consumed in Australia.
- Pay As You Go (PAYG) Withholding: This is the tax you’ve collected from payments made to your employees and, in some cases, other businesses.
- Pay As You Go (PAYG) Instalments: These are regular prepayments you make towards your expected annual income tax bill.
Who Needs to Lodge a BAS?
The main trigger for lodging a BAS is GST registration. Here in Australia, if your business has an annual GST turnover of $75,000 or more, you are required to register for GST and lodge a BAS. For non-profit organisations, that threshold is higher, sitting at $150,000. This isn't a niche requirement. As of 2023, there were over 2.7 million Australian businesses registered for GST, which means millions of business owners are regularly preparing and submitting a BAS. Even if you don’t hit the turnover threshold, you can still choose to register for GST voluntarily. Why would you do that? It allows you to claim GST credits back on your business purchases, which can be a smart move for many businesses. If you want to dig a bit deeper, we cover this in our comprehensive overview of Business Activity Statements.Key Takeaway: Your BAS is more than just another form; it's the complete summary of your business's tax relationship with the ATO. Getting it right starts with knowing exactly what you need to report and why.
Reporting Periods Explained
The ATO will assign you a reporting and payment cycle based on your annual turnover. Most small businesses lodge quarterly, which is a pretty manageable timeframe. It gives you enough time to gather your records without letting the admin pile up into a mountain. The standard reporting periods are:- Quarterly: This is the default for businesses with a GST turnover of less than $20 million.
- Monthly: This is required for businesses with a GST turnover of $20 million or more.
- Annually: This is only an option for a small number of businesses that meet very specific criteria set by the ATO.
Getting Your Financial Records in Order
An accurate Business Activity Statement starts with organised records, not a last-minute scramble through a shoebox full of faded receipts. The real secret to a stress-free BAS is treating your record-keeping as an ongoing habit, not just a quarterly chore. It's about systematically collecting every bit of financial info you need as it comes in. Your mission is to build a complete financial picture of your business. This isn't just about high-level summaries; it’s about having the original documents to prove every single figure you report to the ATO.The Must-Have Documents to Collect
Before you even think about calculating anything, you need your raw data. Think of it like gathering ingredients before you start cooking. For any given BAS period, you need to have collected and be able to easily find the following:- All sales invoices and records: This covers every sale your business made, whether you’ve been paid for it yet or not.
- All expense receipts and supplier invoices: Every single purchase you made for the business needs a tax invoice if you want to claim a GST credit.
- Complete bank and credit card statements: These are non-negotiable for reconciling your accounts and making sure no transaction has slipped through the cracks.
- Payroll reports: You'll need the numbers for gross wages paid and the total PAYG tax you’ve withheld from your team.
A classic trap for new business owners is forgetting about the small cash expenses. That coffee meeting with a client or a quick trip to the post office might seem tiny, but those little GST credits really do add up over a quarter.
Nailing Your Transaction Categories
Once you have your documents, the next job is to categorise them correctly. This is where a lot of businesses get into trouble. Not all sales and purchases are treated the same for GST, and getting it wrong can throw your whole BAS calculation out of whack. Generally, your transactions will slot into one of three main buckets:- Taxable Sales: This is where most goods and services land. You charge GST on these.
- GST-Free Sales: This includes things like basic food, some education courses, and certain medical services. You don't charge GST, but you can still claim credits on the business costs you incurred to make those sales.
- Input-Taxed Sales: This is mainly for financial supplies (like bank fees) and residential rent. You don't include GST in the price, and you generally can't claim any GST credits for related purchases.
Calculating GST and Other Tax Obligations
Okay, you’ve wrestled your financial records into shape. Now it’s time to crunch the numbers and figure out what actually goes onto your Business Activity Statement. This isn't about becoming a master accountant overnight; it's more about following a clear, methodical process. For most businesses, this boils down to three key things: GST, PAYG withholding for your staff, and PAYG instalments for your own income tax. The whole process is a logical flow. Your invoices, receipts, and bank statements are the building blocks for an accurate BAS. This infographic gives a great visual of how it all connects.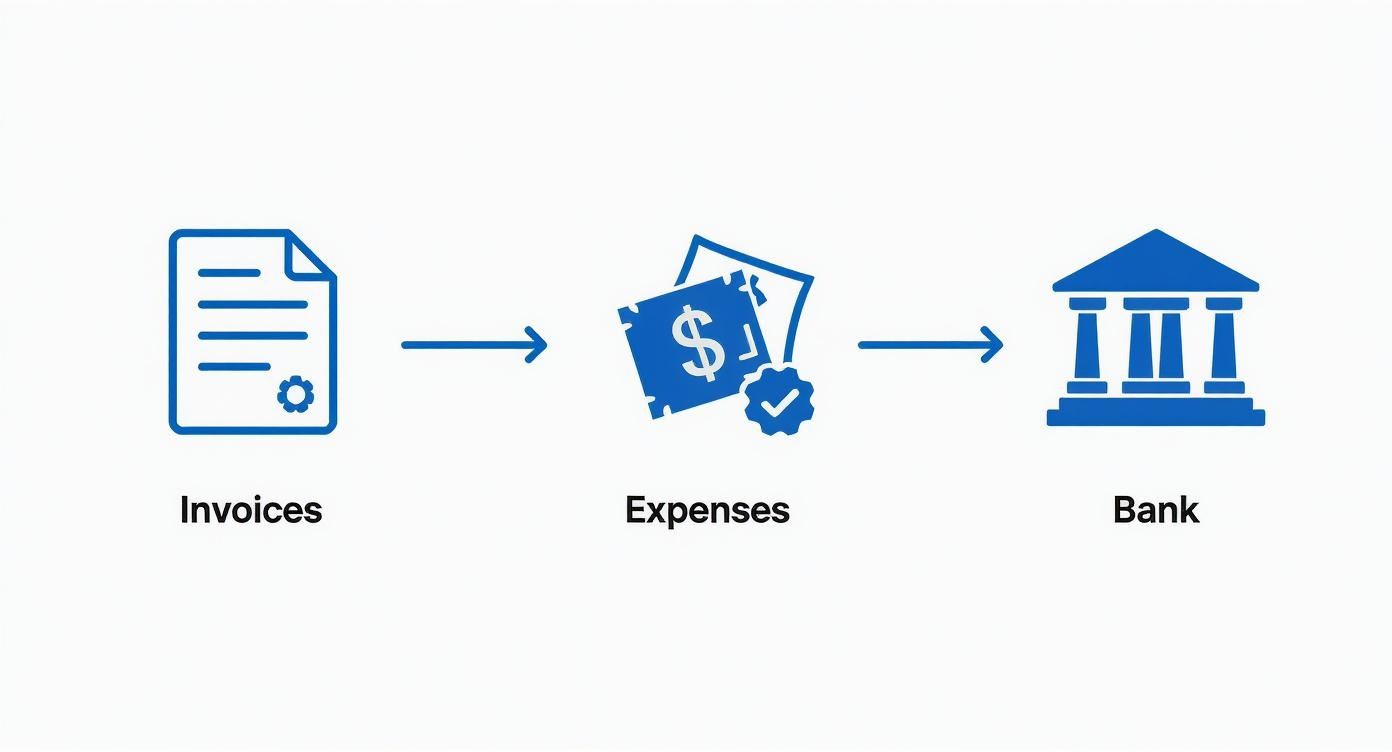
Calculating Your Net GST Position
Your main goal here is to work out the difference between the GST you’ve collected and the GST you’ve paid. The final number will tell you whether you owe the ATO money or if you’re getting a refund for the period. First up, calculate the GST you collected from customers. Go through all your sales invoices for the reporting period and add up the GST amounts. This total is what you report at label 1A (GST on sales) on your BAS. Let's take a freelance consultant as an example. If they invoiced clients for a total of $22,000 (which includes $2,000 in GST) during the quarter, their figure for 1A is simply $2,000. Next, it’s time to claim back your credits. Tally up all the GST you paid on business-related purchases. You'll need valid tax invoices for everything you claim. This total goes into label 1B (GST on purchases). If our consultant spent $5,500 (including $500 GST) on essentials like software subscriptions and professional insurance, their figure for 1B is $500. To get your net GST position, you just subtract 1B from 1A. In our consultant's case: $2,000 - $500 = $1,500. That's the amount they owe the ATO for the quarter. Simple as that.A Quick Tip from Experience: One of the most common mistakes I see is business owners forgetting to claim GST credits on big-ticket items, like a new work vehicle or a piece of expensive machinery. Make sure you have the tax invoice for these capital purchases and properly calculate the GST portion. It can make a huge difference to your bottom line.
Reporting PAYG Withholding and Instalments
Your BAS isn’t just for GST. It’s also where you report the tax you’ve withheld from your employees' wages, known as PAYG withholding. To work this out, just grab your payroll records for the period. You need two figures: the total gross wages you paid and the total income tax you withheld from those wages.- The total salary and wages figure goes to label W1.
- The total tax withheld amount is reported at label W2.
Navigating Lodgment Deadlines and Reporting Cycles
Getting the numbers right on your Business Activity Statement is only half the battle. The other half—which is just as critical—is lodging it on time. Missing a due date is an easy way to attract unwanted attention and penalties from the ATO, something no business owner needs. Staying on top of your reporting schedule isn't just about compliance; it's a core part of good business management and keeping your cash flow predictable. The Australian Taxation Office (ATO) will typically determine your reporting cycle based on your GST turnover. For the vast majority of small and medium businesses, this means lodging quarterly. It’s a good rhythm—frequent enough that the paperwork doesn't become a mountain, but with enough time between lodgments to actually run your business. Once you’re crystal clear on whether you’re lodging monthly, quarterly, or annually, you can build a reliable workflow around those dates.Understanding Your Reporting Period
Your reporting cycle dictates your entire BAS timeline, so it’s essential to know exactly which category your business falls into. Getting this wrong can lead to missed deadlines and a lot of unnecessary stress.- Quarterly Lodgment: This is the standard for most businesses, specifically those with a GST turnover of less than $20 million. If you're a typical small enterprise in Australia, this is likely you.
- Monthly Lodgment: Once your business hits a GST turnover of $20 million or more, the ATO will require you to shift to monthly BAS lodgments.
- Annual Lodgment: This is far less common and is generally reserved for very small businesses that have voluntarily registered for GST and meet other specific criteria.
A Practical Tip: One of the biggest perks of using a registered tax or BAS agent is gaining access to their extended deadlines. For quarterly lodgers, this often means an extra month to get your BAS finalised and submitted. Trust me, that extra breathing room can be a lifesaver during a busy quarter.It's also worth noting that the ATO is tightening compliance. From 1 April 2025, new rules may see businesses with a history of late payments or incorrect reporting being moved from quarterly to monthly GST reporting. You can learn more about these changes and the monthly vs quarterly BAS rules from acttaxgroup.com.au.
Key Lodgment Dates to Remember
When you’re juggling sales, staff, and suppliers, it's incredibly easy for a tax deadline to slip your mind. The simplest solution is often the best: mark up your calendar now so there are no surprises later. Here’s a quick summary of the standard BAS lodgment dates you need to know.Standard BAS Lodgment and Payment Due Dates
This table outlines the key deadlines for both quarterly and monthly filers who manage their own BAS lodgments.| Reporting Period | Quarterly Due Date | Monthly Due Date |
|---|---|---|
| July – September | 28 October | 21st of the following month |
| October – December | 28 February | 21st of the following month |
| January – March | 28 April | 21st of the following month |
| April – June | 28 July | 21st of the following month |
Lodging Your BAS With the ATO
Final Checks Before You Submit
Before you hit that final "submit" button, it’s well worth taking ten minutes for one last review. I can't tell you how many times a quick pre-lodgment check has saved one of our clients the headache of amending a BAS later. Think of it like proofreading an important email before you send it. Here’s a simple checklist we run through with our clients:- Double-Check the Details: Is your ABN and business name correct? Simple, but critical.
- Verify the Reporting Period: Make sure you’re lodging for the right quarter or month.
- Review Key Figures: Quickly glance over the numbers at G1, 1A, and 1B. Do they match your own calculations or software report? A simple typo here is one of the most common mistakes we see.
- Check the Final Figure: Does the final amount payable or refundable actually make sense based on how busy you were that period?
A simple transposition error—typing $5,100 instead of $1,500—can cause a whole lot of unnecessary stress and follow-up from the ATO. This final check is your best defence against those small but impactful human errors.
After You Lodge Your BAS
Once your BAS is successfully lodged, you'll get a confirmation from the ATO. If you have a tax bill to pay, the due date is the same as your lodgment deadline. You can easily pay via BPAY, direct debit, or credit card through the ATO portal. If you’re expecting a refund, the ATO is usually pretty quick, typically processing them within 14 business days. The money will be deposited directly into your nominated bank account. Finally, don’t forget your record-keeping duties. Australian law is very clear: you must keep all records related to your BAS, including tax invoices and calculation worksheets, for at least five years. Storing digital copies in a secure cloud folder is a great way to ensure they are safe, organised, and easy to find if the ATO ever needs to see them. This final step closes the loop on the BAS process, leaving you fully compliant and ready for the next quarter.Common Questions We Hear About Preparing Your BAS
As you get the hang of preparing your BAS, a few specific questions almost always come up. Getting these sorted is the key to lodging with confidence and making sure your business stays on the right side of the ATO. These are the questions we hear most often from business owners who are still learning the ropes. Nailing the answers will help you handle the tricky bits and dodge simple errors that can cause major headaches down the track.Cash vs Accrual: What’s the Difference for GST?
This is a big one. Choosing between cash and accrual methods directly impacts when you report your GST. It's a fundamental choice that needs to line up with how your business actually handles its money. On a cash basis, you only account for GST when money physically changes hands. That means when a customer pays you, or when you actually pay a bill. Many small businesses prefer this method because it perfectly mirrors their real-world cash flow. No cash, no GST to report. Simple. The accrual basis, on the other hand, means you account for GST the moment an invoice is sent or a bill is received—it doesn’t matter when the payment actually happens. Larger businesses with a GST turnover of $10 million or more are generally required by the ATO to use this method."I’ve Made a Mistake on an Old BAS. How Do I Fix It?"
It happens to the best of us. You lodge your BAS, breathe a sigh of relief, and then spot an error from a previous quarter. The good news is you can usually fix it on your current statement, as long as the mistake is within certain time and value limits set by the ATO. For most small errors, a simple adjustment on your next BAS is all you need. But if you’re dealing with a larger amount or the mistake is outside the correction limits, you might have to submit a formal revision for the original BAS. When in doubt, the safest bet is always to chat with a registered BAS or tax agent.Our Pro Tip: Don't ever just ignore a mistake. The ATO’s systems are incredibly good at flagging inconsistencies. Being proactive about fixing errors shows you’re trying to do the right thing and helps you sidestep potential penalties.
The Most Common BAS Mistakes to Steer Clear Of
Even with the best intentions, some mistakes pop up more than others. Knowing what these common traps are is the best way to avoid falling into them. Here are a few of the most frequent errors we see:- Claiming GST credits on things that don't actually have GST included, like basic food, bank fees, or interest on a loan.
- Simple data entry blunders, like transposing numbers when you’re typing figures in from your accounting software.
- Forgetting to keep valid tax invoices for all the business purchases you’re claiming credits for. You have to be able to prove it.
Feeling like the BAS process is more trouble than it's worth? The team at Australia Wide Tax Solutions can take care of your BAS preparation and lodgment from start to finish, guaranteeing accuracy and on-time lodgment, every single time. Get in touch with our experts today.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
