

Your Starting Point for Business Registration in Australia
Launching a business is a huge milestone, but the registration process can seem overwhelming. I'm here to give you a clear roadmap, starting with the big decisions that will shape your entire venture. We'll look at why choosing the right business structure is so much more than just ticking a box and how getting your ABN is the key that unlocks your ability to operate legally. Instead of drowning you in jargon, this is your high-level overview of the journey ahead. You'll go from picking a unique business name to getting your head around your initial tax obligations. Think of this as the strategic briefing before we dive into the nitty-gritty steps that turn your business plan into a fully compliant reality.The Path to a Registered Business
You're about to join a pretty vibrant community. The Australian business scene is thriving, with 2,729,648 actively trading businesses on the books as of mid-2025. That number includes a net increase of 66,650 businesses in just one year, driven by a healthy 16.4% entry rate. Interestingly, companies saw the most significant growth at 4.7%, which shows a real trend towards people setting up more formal business structures right from the get-go. If you're a data nerd, you can dig deeper into these numbers on business entries and exits from the ABS. This infographic breaks down the core phases of the journey to help you picture the path forward.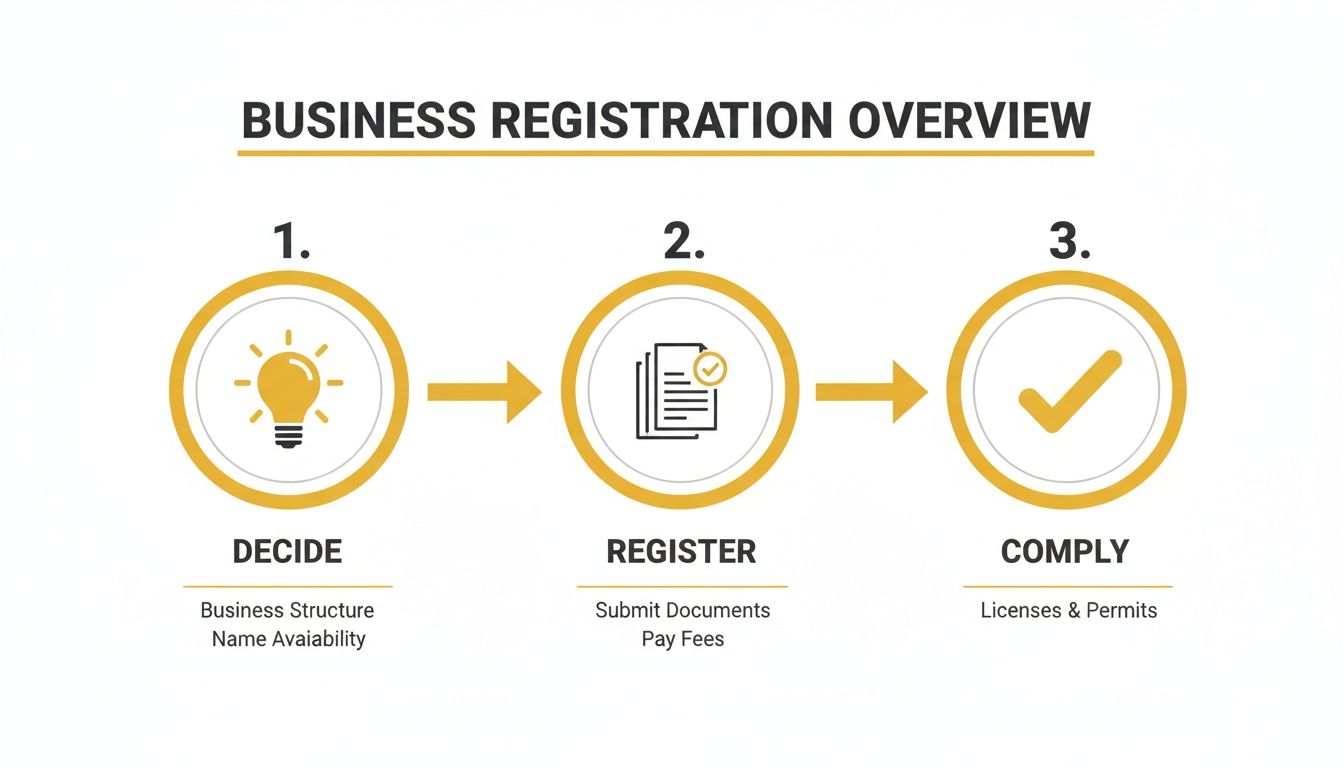
From my experience, the most successful business launches always start with a solid foundation. Getting these initial steps right—your structure, ABN, and name—prevents costly administrative headaches down the track and sets you up for sustainable growth.Let's start breaking these foundational pieces down into simple, manageable actions, beginning with the most critical decision you'll make.
Choosing the Right Business Structure
Deciding on your business structure is hands down one of the most critical calls you'll make when you first get your business off the ground in Australia. This isn't just about filling out forms; it fundamentally shapes your personal liability, how much tax you end up paying, and the sheer volume of admin work on your plate. Get this right from day one, and you’ll save yourself a world of headaches and costly restructuring dramas later on. Think of it this way: a freelance graphic designer just starting out will likely lean towards a sole trader structure. It’s simple, the setup costs are low, and it just makes sense when you're a one-person show. Legally, their personal and business finances are one and the same. While that's straightforward, it also means their personal assets—like their house or car—are on the line if the business gets into hot water with debt.Sole Trader Simplicity Versus Company Protection
As a sole trader, you are the business. You’ll use your personal Tax File Number (TFN) to lodge tax returns and you have total control. It's the most common structure for new ventures for a reason, with over 822,000 sole traders actively operating across Australia. But what if you're launching a tech startup and bringing in investors? Or a construction business where the risks are much higher? In those cases, a proprietary limited (Pty Ltd) company is a far better shield. This structure creates a completely separate legal entity, which protects your personal assets from business debts. This is the power of "limited liability." The company gets its own TFN, lodges its own tax returns, and any profits it makes belong to the company until they’re paid out to shareholders as dividends.The key takeaway is this: your choice of structure must align with both your current situation and your future growth plans. Don't just pick the easiest option without considering where you want to be in five years.
Understanding Partnerships and Trusts
Beyond those two common paths, you've got a couple of other options. A partnership is where two or more people (or entities) run a business together. They're fairly simple to set up, but the catch is that all partners are generally on the hook personally for business debts—including those racked up by another partner. Then there's the trust, which is a more complex setup. Here, a trustee (an individual or a company) holds assets for the benefit of others, known as beneficiaries. Trusts are fantastic for asset protection and offer great tax flexibility, which is why you often see them used for family businesses or investment portfolios. The trade-off? They come with higher setup and ongoing administration costs. The table below gives a quick snapshot of how these structures stack up against each other.Comparing Australian Business Structures at a Glance
| Feature | Sole Trader | Partnership | Company (Pty Ltd) | Trust |
|---|---|---|---|---|
| Legal Status | You and the business are one legal entity | Two or more partners; not a separate legal entity | A separate legal entity from its owners | Trustee holds assets for beneficiaries; not separate entity |
| Liability | Unlimited. Personal assets are at risk | Unlimited. Partners are jointly and severally liable | Limited. Personal assets are generally protected | Trustee liability may be limited; beneficiaries are protected |
| Tax | Taxed at individual marginal tax rates | Profits/losses distributed to partners and taxed individually | Taxed at the flat company tax rate (25% or 30%) | Income distributed to beneficiaries and taxed at their rates |
| Setup Cost | Very low (just ABN registration) | Low (partnership agreement is recommended) | Higher (ASIC registration fees apply) | Highest (requires a formal trust deed) |
Securing Your Australian Business Number (ABN)
Proving You're a Genuine Enterprise
One of the biggest hurdles that trips people up is proving they are actually 'carrying on an enterprise'. This is the Australian Taxation Office (ATO)'s way of separating a real business from a hobby or a passive investment. You have to show a clear plan and a genuine intention to make a profit. It’s the difference between selling a few old books from your shelf on eBay (a hobby) versus buying books specifically to resell online with a clear business plan and a separate bank account (an enterprise). To back up your application, you should be able to demonstrate that you’ve:- Made a conscious decision to start a business and have a plan for it.
- Taken real steps to get started, like buying assets, building a website, or printing business cards.
- Reasonably expect your activities to eventually turn a profit.
What to Prepare for Your Application
To make the application process as smooth as possible, it pays to have your documents ready to go. You won't get far without these key details. Make sure you have:- Your Tax File Number (TFN), plus the TFNs of any partners or directors.
- Proof of identity documents on hand.
- The details of your business structure (sole trader, company, etc.).
- A clear and specific description of your main business activities.
Pro Tip: When describing your business, be specific. Instead of putting "consulting," try something like "providing marketing strategy consulting for small retail businesses." This kind of clarity helps the ABR understand what you do and approve your application without a fuss.For a more detailed walkthrough, our guide to registering an Australian Business Number (ABN) in Australia has even more tips to help you secure your ABN without a hitch.
Registering Your Business Name and Company
The ASIC Registration Process
Getting a company registered is a bigger deal than just reserving a business name. You'll be dealing with the ASIC portal, formally appointing directors, and taking on specific legal responsibilities. It's a step more business owners are taking seriously. In July 2025, for example, while 118,162 new ABNs were registered, a whopping 35,844 of those were new companies. That's a 20.41% jump from the previous year, which tells us that founders are increasingly prioritising the protection and growth potential that a company structure provides. You can see more on this trend in the full New Business Index Report. Be prepared for a fee when you register with ASIC. Currently, setting up a standard proprietary limited company will set you back around $576. For a full walkthrough of what's involved, have a look at our detailed guide on how to set up a Pty Ltd company in Australia.It's vital to remember that a business name registration offers zero ownership or protection over the name itself. It's simply a registration that allows you to trade under that alias. True brand protection comes from trademarking.
Name Selection and Protection
Before you get too attached to a name, you absolutely must check if it's available. A quick search on ASIC’s online tool will show you if your dream business name or company name is already being used anywhere in Australia. A few practical tips from experience:- Be Unique: Don't pick a name that sounds like five other businesses in your industry. You want to stand out, not blend in.
- Check Everywhere: Search the business name register and the company register. Crucially, also check for existing trademarks on the IP Australia website.
- Secure Your Domain: As you're checking names, open another tab and see if the .com.au domain is available. Grab it immediately if it is.
Navigating Your Tax and GST Obligations
The GST Threshold Explained
The Australian Taxation Office (ATO) has a clear rule: GST registration becomes mandatory once your business has a current or projected annual turnover of $75,000 or more. For non-profits, that figure is $150,000. Remember, turnover is your gross business income—every dollar that comes in—not your profit. This is a classic tripwire for new business owners, especially in service-based fields where growth can be unpredictable. Imagine a freelance IT consultant starting out. They might only be making $5,000 a month. But if they suddenly land a big project and their projected income for the year shoots past that $75,000 mark, they have just 21 days to register for GST.Don’t just wait until you hit the $75,000 mark. Proactively monitor your cash flow and forecasts. Registering late can lead to penalties and a messy back-payment process that catches many new entrepreneurs off guard.
Should You Register for GST Voluntarily?
What if you're nowhere near the threshold? You can still choose to register for GST voluntarily. This isn't a simple yes-or-no answer; it’s a strategic decision with real financial consequences.- The Upside: You can claim GST credits on your business purchases. If you've had major setup costs—think computers, specialised equipment, or software—registering lets you claim back the 10% GST you paid on those items.
- The Downside: You must charge GST on all your sales. This effectively increases your prices by 10%. If your customers are the general public (who can't claim GST credits), this could make you less competitive.
- The Admin: It adds another layer of paperwork. Once registered, you are legally required to lodge a Business Activity Statement (BAS) with the ATO, which for most new businesses is a quarterly task.
Other Essential Tax Registrations
GST is just one piece of the puzzle. As your business evolves, other tax registrations will come into play, usually triggered by specific milestones. Two of the most common ones are:- Pay As You Go (PAYG) Withholding: This is non-negotiable the moment you hire your first employee. You're required to withhold tax from their salary and wages and send it to the ATO on their behalf.
- Fringe Benefits Tax (FBT): If you start providing certain benefits to employees—like a company car for private use or paying for their health insurance—you'll likely need to register for FBT.
Final Steps and Staying Compliant
You’ve done the heavy lifting and got the core registrations sorted. But don't pop the champagne just yet. Getting registered is a one-time sprint; staying compliant is a marathon that protects the business you’ve worked so hard to build. Your first practical move? Open a dedicated business bank account. Seriously, do this now. It’s not just a friendly suggestion; it’s absolutely essential for clean financial management. I’ve seen countless new business owners create a bookkeeping nightmare for themselves by mixing personal and business funds. It’s a fast track to chaos at tax time. A separate account gives you a crystal-clear record of income and expenses, which makes tracking your financial health and lodging your BAS a whole lot simpler.Keeping on Top of Your Ongoing Duties
With your banking sorted, your focus now shifts to the recurring tasks that keep your business in good standing. Think of these as your business's regular health check-ups. Ignoring them can lead to penalties and, worse, damage your professional reputation. Here’s what you’ll need to manage:- Business Name Renewal: That business name you registered isn't yours forever. You have to renew it with ASIC every one or three years. Miss the deadline, and you could lose the right to use it.
- ASIC Annual Review: If you're running a company, you'll get an annual statement from ASIC. You must check it, update any company details that have changed, and pay the annual review fee. It's a non-negotiable part of keeping your company registration active.
- Keeping Your ABN Details Fresh: Your details on the Australian Business Register (ABR) must always be current. If you move your business, change your contact info, or alter your structure, you have just 28 days to update it.
Staying compliant is about more than just dodging fines. It's about building a professional operation that earns trust with customers, suppliers, and the ATO. Cutting corners here undermines the very credibility you're trying to build.One last thing that often gets missed in the rush: industry-specific licences. A café needs a food licence from the local council. A builder needs a state-based contractor licence. These aren't optional extras; they're critical for operating legally. Ticking off this final checklist ensures your business starts on solid, lawful ground.
Got Questions? We've Got Answers
Stepping into the world of business registration always brings up a few curly questions. Let's tackle some of the most common ones we hear from entrepreneurs just starting out.How Long Does This Whole Registration Thing Take?
Honestly, it varies. Some parts are incredibly fast. For instance, applying for your ABN online through the Australian Business Register can often spit out your number almost instantly. Registering your business name is usually just as quick once the payment goes through. The real waiting game is typically with a company registration. Once you've lodged all your paperwork with ASIC, you should expect it to take about one to two business days. The longest part of the process is almost always the prep work on your end—finalising your structure and getting all your details in order before you even start the applications.Do I Have to Register for GST Straight Away?
Not necessarily. The key trigger for mandatory GST registration is your turnover. You only have to register once your annual business turnover is projected to hit $75,000 or more. For non-profits, that threshold is higher at $150,000. However, you can choose to register voluntarily before you reach that magic number. Why would you? Registering early means you can start claiming GST credits back on your business purchases. The trade-off is that you must also start charging GST on your sales and lodging regular Business Activity Statements (BAS) with the ATO. It's a strategic choice you'll need to make based on your business model and expected expenses.Quick Tip: ABN vs. ACN An ABN is your 11-digit Australian Business Number, used by all business types for tax purposes. An ACN, on the other hand, is a 9-digit Australian Company Number given only to registered companies. If you set up a company, you'll have both.
The four main structures are sole trader, partnership, company, and trust. A sole trader is simplest and cheapest but offers no liability protection. A company provides limited liability at a flat tax rate but costs more to run. A trust offers tax flexibility and asset protection but is complex to administer. The right choice depends on income, risk profile, and growth plans.
Base rate entities — companies with aggregated turnover under $50 million that derive no more than 80% of income from passive sources — pay 25%. All other companies pay 30%. Shareholders pay income tax on dividends, potentially offset by franking credits for tax already paid at the corporate level.
Consider a company when business net profit consistently exceeds $100,000–$120,000 and the rate differential generates meaningful savings, when you need liability protection from business creditors, when you plan to bring in investors, or when you want to retain earnings at the lower corporate rate rather than distributing everything as personal income.
A family trust (discretionary trust) holds assets for a class of beneficiaries. The trustee decides each year how much income to distribute to each beneficiary. By directing income to members in lower tax brackets, the trust reduces the overall family tax burden. Income retained in the trust is taxed at the highest marginal rate (47%).
Ongoing costs include the ASIC annual review fee (currently $310 for a proprietary company), company tax return lodgement fees, accounting fees for financial statements, and potentially payroll and BAS compliance. Total annual compliance costs typically range from $2,000 to $8,000 depending on activity levels and complexity.
