

Unlocking Your Property's Financial Potential
The Three Pillars of Property Deductions
To get a real handle on your investment, it’s best to sort your expenses into three main buckets. Nailing these categories is the first step in knowing how to prepare an investment property tax return that maximises every claim while keeping the Australian Taxation Office (ATO) happy. These core pillars are:- Immediate Expenses: These are your day-to-day running costs—think council rates, loan interest, insurance, and minor repairs. You claim these in the same financial year you pay them. Simple.
- Borrowing Costs: This covers all the upfront fees you paid to get your investment loan, like establishment fees, valuation fees, and Lenders' Mortgage Insurance (LMI). These costs are spread out and claimed over five years.
- Depreciation: This is the most powerful "non-cash" deduction you have. It's an allowance for the natural wear and tear on the building's structure and the assets inside it, from the carpets to the cooktop. You get to claim this decline in value each year without actually spending a cent.
By mastering these three categories, you're not just tracking expenses; you're building a clear framework for your investment's finances. This organised approach makes tax time a breeze and ensures you don't leave any money on the table.In this guide, we'll dive deep into each of these pillars, breaking them down with practical examples and straightforward advice. Our goal is to arm you with the confidence to manage your property's tax obligations like a pro, turning a complex chore into a key part of your investment strategy.
Claiming Your Ongoing Property Expenses
Once you’ve got tenants in and the rent starts rolling in, you’ll start seeing the day-to-day costs of owning an investment property. These ongoing expenses are your bread and butter when it comes to tax deductions in Australia. Think of it like running a small business—which, in the eyes of the ATO, it is. Every dollar you spend to keep that property running and earning you an income can be claimed in the same financial year you paid for it. This is a massive plus for your cash flow, giving you an immediate tax benefit rather than having to wait years to see the value.The Most Common Immediate Deductions
The list of what you can claim right away is pretty extensive, covering everything from council rates to the interest on your loan. Getting these right isn't just good practice; it's fundamental to making your investment work for you financially. Here are the big-ticket items you can claim as soon as you pay for them:- Interest on Your Investment Loan: This is the heavyweight champion of deductions for most investors. You can claim 100% of the interest portion of your loan repayments. Just remember, you can't claim the part of the repayment that actually pays down the loan principal.
- Council and Water Rates: Every charge from your local council and water authority is fair game. This includes all your standard rates, sewerage access, and any other administrative fees they tack on.
- Land Tax: If your property’s land value tips over your state's threshold, the land tax bill you receive is fully deductible.
- Strata and Body Corporate Fees: Own an apartment, townhouse, or unit? Those regular administrative and sinking fund levies are claimable.
- Insurance Policies: The premiums you pay for building, contents, and landlord insurance are all deductible. These policies protect your asset and your income, so the ATO treats them as a necessary cost of doing business.
Key Takeaway: The golden rule is simple. If you spent the money to directly manage or maintain your rental property while it was genuinely available for rent, it’s almost certainly an ongoing expense you can claim right now.Here’s a quick checklist to help you keep track of the most common immediate deductions. It's a great reference to have on hand throughout the year so nothing slips through the cracks come tax time.
Checklist Of Immediately Deductible Expenses
| Expense Category | What It Covers | ATO Watch Point |
|---|---|---|
| Loan Interest | The interest component of your investment loan repayments. | You cannot claim the principal portion of repayments. Be careful with mixed-purpose loans (e.g., part investment, part private). |
| Rates & Taxes | Council rates, water rates (not consumption paid by tenant), and annual state land tax. | Ensure these are for the period the property was available for rent. |
| Strata/Body Corp | Administrative and sinking fund levies for units, apartments, and townhouses. | Special levies for major capital works may need to be treated as capital expenses, not immediate deductions. |
| Management Fees | Fees paid to a real estate agent for managing the property, advertising for tenants, etc. | Includes letting fees, inspection fees, and postage costs. |
| Insurance | Premiums for landlord, building, and contents insurance policies. | Only the portion related to the investment property is claimable. |
| Repairs & Maintenance | Fixing wear and tear, e.g., repairing a broken appliance, fixing a leak, patching a wall. | Must be a genuine repair to restore something to its original state, not an improvement. |
| Minor Expenses | Bank fees for the loan account, pest control, gardening, cleaning, and stationery. | Keep all receipts, as small amounts add up significantly over a year. |
Repairs Versus Improvements: The Critical Difference
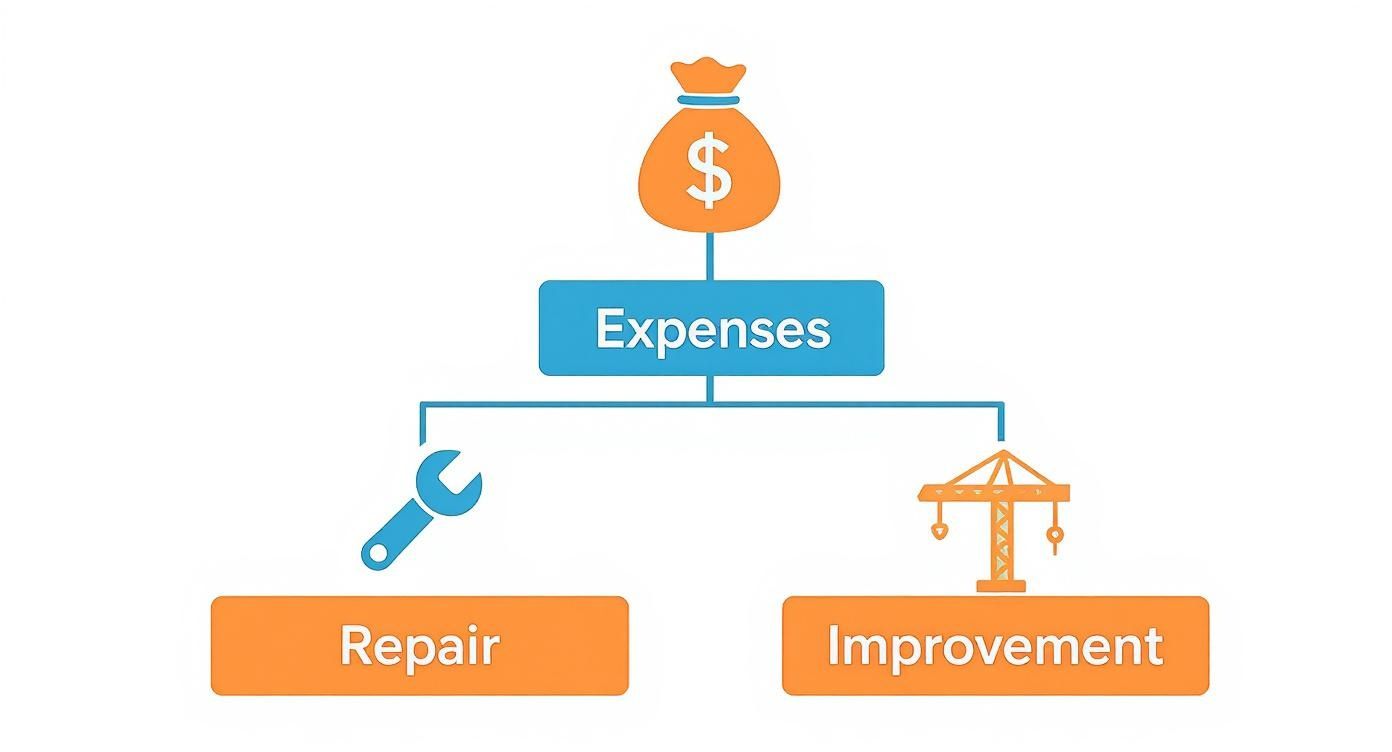
This is the number one spot where property investors get into hot water with the tax office. The ATO looks very closely at this, so understanding the difference between a simple repair and a capital improvement is absolutely essential. A repair is work you do to fix something that’s broken, damaged, or worn out. It’s all about bringing an asset back to its original state. Think fixing a leaking tap, replacing a single broken window, or mending a storm-damaged fence. These costs are 100% deductible in the year you pay them. Easy. An improvement, however, is when you make something substantially better than it was, or add something completely new. This covers renovations, extensions, or replacing an entire structure with a better version. For example, gutting and remodelling a kitchen, building a new deck, or tearing down an old fence to build a brand new, higher-quality one are all capital improvements. You can’t claim these costs immediately. Instead, they get added to your property's "cost base" (which reduces your Capital Gains Tax when you sell) or are claimed over many years as capital works depreciation.Navigating Changing Tax Landscapes
Property tax laws are constantly shifting, and changes at the state level can really throw a spanner in the works for your budget and tax planning. A perfect example is what happened in Victoria, where significant property tax changes in 2025 lowered land tax thresholds. This move instantly made more investors liable for land tax, bumping up their annual costs. While a routine expense like fixing a fence remains an immediate deduction, investors now have to be more vigilant than ever. The ATO is armed with powerful data-matching technology, making it easier for them to spot incorrect claims. You can find more details on how these specific changes affect investors by reading up on Victoria's 2025 property tax changes on randstax.com.au. Your best defence is staying organised and being diligent about categorising every single expense correctly. This not only ensures you claim every legitimate dollar you're entitled to but also means you have clear, justifiable records if the ATO ever comes knocking. Master the difference between a repair and an improvement, and you'll be well on your way to managing your expenses with confidence and avoiding any costly headaches.Unlocking The Power Of Property Depreciation
Beyond the obvious running costs of an investment property lies a powerful, often misunderstood deduction that many investors leave on the table: depreciation. It's frequently the single largest tax deduction you can claim, and the best part? It's a 'non-cash' deduction. This means you don’t actually have to spend a cent during the year to claim it. Think of it like the slow, invisible wear and tear on your property over time. The Australian Taxation Office (ATO) understands that your building and the assets inside it won't last forever, so they allow you to claim a deduction for this decline in value. It’s essentially a reward for investing in property that provides housing for others. For a savvy investor, getting your head around depreciation is like discovering a hidden stream of cash flow. It can be the difference that turns a negatively geared property into a positive one on paper, significantly cutting your taxable income and putting real money back in your pocket.The Two Faces of Depreciation
The ATO splits property depreciation into two distinct categories. You need to claim them separately, and getting this right is crucial if you want to maximise your return while staying on the right side of the tax man. Here are the two types you need to know:- Capital Works (Division 43): This covers the wear and tear on the building's physical structure itself. Think of it as a claim for the "bones" of the building—the foundations, walls, roof, doors, and windows.
- Plant and Equipment (Division 40): This category is for all the fixtures and fittings inside the property. We're talking about items with a shorter lifespan than the building, like carpets, ovens, dishwashers, blinds, and air conditioning units.
Capital Works: The Long Game
Capital works deductions, often just called building depreciation, relate to the original construction cost of the building. As a general rule, you can claim 2.5% of this cost each year for a maximum of 40 years. But there’s a key date you must remember: your property must have been constructed after 16 September 1987 to be eligible. If your place is older than that, don't despair—you can still claim deductions for any major structural renovations or additions completed after this date. For example, if the original construction of your eligible property cost $400,000, you could claim a handsome $10,000 deduction every single year for 40 years. That's a substantial, consistent deduction chipping away at your taxable income, year in and year out.A critical point here: you can only claim the construction cost, not the price you paid for the property. The land your property sits on cannot be depreciated.This infographic helps show where depreciation fits into the bigger picture, clearly separating capital improvements from immediate repairs.
Plant and Equipment: The Assets Within
While capital works cover the building's shell, plant and equipment deductions are all about the removable or mechanical assets inside. These items wear out much faster than bricks and mortar, so you get to claim their value over their much shorter "effective life," as determined by the ATO. The list of eligible items is long, but it includes things like:- Carpets and vinyl flooring
- Ovens, cooktops, and rangehoods
- Dishwashers
- Air conditioners and ceiling fans
- Hot water systems
- Blinds and curtains
- Smoke alarms
Why A Quantity Surveyor Is Non-Negotiable
You're probably thinking, "How on earth am I supposed to know the construction cost of a 30-year-old building or the value of a 10-year-old oven?" This is where a Quantity Surveyor becomes your most valuable player. These professionals are specifically recognised by the ATO as one of the few qualified to estimate historical construction costs and value assets for depreciation. They will physically visit your property, assess everything from the brickwork to the bathroom fans, and prepare a comprehensive tax depreciation schedule.A depreciation schedule isn't just a 'nice-to-have'; for any serious property investor, it's essential. Think of it as your 40-year roadmap, detailing every single depreciable item and calculating the maximum deductions you can legally claim each year.The best part? The one-off fee for this report is 100% tax-deductible. The value it unlocks is immense, with data showing that investors who get a professional schedule prepared claim significantly more. For example, some specialist firms have found their clients claim an average annual deduction of around $8,846—far more than what the ATO's general statistics show. This just proves that without expert help, you are almost certainly leaving thousands of dollars on the table.
How To Deduct Your Borrowing Costs Correctly
While the interest you pay on your investment loan is a simple, year-on-year deduction, the initial costs of setting up that loan are a different beast altogether. This is a classic tripwire for new investors, and getting it wrong can attract unwanted attention from the ATO. Unlike loan interest, you can’t claim all your setup costs in the first year. Instead, these borrowing costs must be claimed gradually over five years. Think of it like a slow-release vitamin for your tax return rather than a one-off shot in the arm. Spreading the deduction this way keeps you compliant and avoids the red flags that come with incorrect upfront claims.What Counts As A Borrowing Cost?
So, what exactly are borrowing costs? In short, they're the expenses you paid directly to get the loan approved and established. They cover all the administrative and legal legwork needed to secure the finance, separate from the actual interest you pay on the borrowed money. The most common deductible borrowing costs include:- Loan Establishment Fees: That one-off fee the bank charges to set up the mortgage.
- Lender's Mortgage Insurance (LMI): A big one. If your deposit was less than 20%, the entire LMI premium is a deductible borrowing cost.
- Valuation Fees: The cost for the lender's mandatory valuation of the property before they gave you the green light.
- Title Search Fees: Fees your solicitor or the bank charged to run searches on the property's title.
- Mortgage Broker Fees: If a broker helped you find the loan, their fee is usually bundled in here too.
The key takeaway is simple: if the expense was directly related to establishing the loan agreement, it's likely a borrowing cost that must be spread over a five-year period.Let's run a quick example. Say your total borrowing costs added up to $10,000 (maybe a $1,000 establishment fee and $9,000 in LMI). You would simply claim a $2,000 deduction on your tax return each year for five straight years.
Distinguishing Borrowing Costs From Capital Costs
It’s absolutely critical not to mix up borrowing costs with capital costs. They play completely different roles in your tax strategy. While borrowing costs reduce your taxable income each year, capital costs work very differently. Capital costs are the expenses tied to the actual purchase of the property, not the loan itself. These include things like:- Conveyancing and solicitor's fees for the property transfer.
- Stamp duty paid to the state government.
- Building and pest inspection fees.
Don't Forget Professional Fees
Finally, there’s a third category to remember: professional fees that you can claim immediately. The most important one is the fee you pay a registered tax agent or accountant to prepare and lodge your tax return, specifically the part that deals with your rental property schedule. This is a standard operating expense of running your investment, and you can claim it in full in the year you paid it. Keeping these three categories—borrowing costs, capital costs, and professional fees—separate is vital for accurate investment property tax deductions in Australia.Common Mistakes And ATO Red Flags To Avoid
Mixing Private And Investment Expenses
This is easily one of the most common errors we see, especially when loans are involved. If you have a single loan facility covering both investment and private use, you absolutely must get the interest apportionment right. Here's a classic ATO red flag scenario:- What Not To Do: An investor redraws $30,000 from their investment property loan to buy a new car for personal use. They then carry on claiming 100% of the interest on the entire loan balance.
- The Correct Approach: You can only claim the interest on the loan portion that's actively working for the investment property. The interest on that $30,000 car redraw is a private expense. It is not deductible.
Misclassifying Repairs As Improvements
As we've touched on, the line between a repair and an improvement can get a bit blurry. The ATO knows this, which is why they watch this area like a hawk. Trying to claim a major renovation as an immediate "repair" deduction is a guaranteed way to attract their attention.Think of it like this: fixing a single leaking pipe is a deductible repair. But if that small job snowballs into a full bathroom renovation—complete with new tiles, a modern vanity, and a frameless shower screen—it's now a capital improvement. Those costs have to be depreciated over years, not claimed in one hit.Getting this wrong can lead to serious penalties. Always, always keep detailed invoices that clearly spell out the work done. This is your primary evidence to justify how you've classified the expense.
Claiming Expenses For An Unavailable Property
To claim deductions, your property must be genuinely available for rent. Simple as that. You can’t claim expenses for periods when you're using it for a personal holiday or have pulled it off the market. For example, blocking out December for a family getaway at your beach house means you can't claim the loan interest or holding costs for that month. The property must be actively advertised and ready for a tenant to move in. Keep copies of property listings and emails with your agent as proof of its availability. And on a related note, it’s critical that you https://awts.net.au/blog/declare-all-investment-income-in-your-tax-return/. Forgetting to declare rental income is another huge red flag for the ATO.Forgetting The Rules Have Changed
Tax laws don’t stand still, and it’s your job as an investor to keep up. One major change that still trips people up years later is the rule on travel expenses. You can no longer claim any deductions for the cost of travelling to inspect your residential rental property. That means no deductions for flights, car expenses, accommodation, or meals. This rule was brought in specifically to stop investors from trying to write off their personal holidays. While the fundamentals of deductions like interest and council rates are fairly stable, the ATO's focus on compliance has only grown sharper. Diligent record-keeping isn't just good practice; it's essential for protecting your investment and ensuring you meet your tax obligations with confidence.Your Top Tax Deduction Questions, Answered
Even when you feel like you've got a handle on the rules, real-world situations can throw a spanner in the works. Nailing the day-to-day application of tax law is what really separates a good investor from a great one. Let’s tackle some of the most common questions we hear, clearing up the confusion so you can manage your property with confidence. We'll dive into the tricky bits—like what happens when your property is empty, what paperwork you really need, how negative gearing actually works, and when it’s time to call in a professional.Can I Claim Deductions For My Property When It Is Vacant?
Yes, you absolutely can, but there’s one non-negotiable condition: the property must be genuinely available for rent. This is a key phrase the Australian Taxation Office (ATO) pays very close attention to. This means you need to be actively looking for a tenant at a fair market rent. For instance, if your property sits empty for a couple of weeks between tenants but you've got it listed with an agent, you can keep claiming all your usual running costs—loan interest, council rates, insurance, you name it. The rental income might have stopped for a moment, but the costs of holding that investment definitely haven't. The moment you take the property off the market for personal use, however, the deductions stop. If you block out a month for your family to use as a holiday home, or you're doing renovations that aren't related to getting it ready for the next tenant, it's no longer "genuinely available for rent." For that period, the expenses are on you.ATO Pro Tip: Keep a clear paper trail showing the property was available. This means saving copies of online rental listings, your agreement with the property manager, and even records of rental applications you received. In an audit, this documentation is your best friend.
What Records Do I Need To Keep For My Investment Property?
Getting your record-keeping right is the single most important habit for any property investor. It's not just a good idea; it's a legal requirement. The ATO expects you to keep detailed records of all income and expenses for at least five years from the date you lodge your tax return. Think of your records as the complete financial story of your investment property. You’ll need:- Proof of Income: Bank statements showing every dollar of rent that has come in.
- Proof of Expenses: Dated receipts and invoices for every single claim, whether it’s a $5 tap washer or a $2,000 insurance premium.
- Loan Documents: All the paperwork from your lender, especially statements that clearly show the interest you’ve paid.
- Purchase & Legal Docs: The original contract of sale, conveyancing documents, and proof of stamp duty paid. These are crucial for calculating Capital Gains Tax later.
- Depreciation Schedule: The detailed report from a qualified quantity surveyor.
How Does Negative Gearing Work With Tax Deductions?
You'll hear the term 'negative gearing' thrown around a lot in Australian property circles, and it’s all about your tax deductions. It’s what happens when your property’s total deductible expenses for the year add up to more than the rental income it brings in. This creates what's called a net rental loss. The real power of this strategy is what you can do with that loss. The ATO allows you to subtract this net rental loss from your other taxable income, like your salary. Let's run a quick example. Say your property earns $30,000 in rent for the year. But after you add up all your deductions—loan interest, council rates, repairs, and depreciation—your total expenses come to $40,000. You’ve made a net rental loss of $10,000. You can then take that $10,000 loss and use it to reduce your other taxable income. If you earn a $90,000 salary, that loss brings your taxable income down to $80,000, meaning you pay less tax. The strategy is built on the idea that the property's value will grow over time (capital growth) to deliver the real profit, while the tax deductions help you manage the cash flow hit in the meantime.Do I Really Need An Accountant For My Investment Property?
While the law doesn't force you to use an accountant, going it alone with an investment property tax return is a huge risk. Australian property tax law is notoriously complex, full of tricky rules and frequent updates that can easily catch out even the sharpest DIY investor. And the penalties for getting it wrong can be steep. A good accountant who lives and breathes property investment is an invaluable part of your team. They will:- Keep you compliant with every ATO rule.
- Advise on the right way to structure your investment from day one.
- Make sure you claim every single legitimate deduction available.
- Provide strategic advice on Capital Gains Tax (CGT) for when you decide to sell.
Navigating the complexities of property tax is crucial for maximising your returns. The team at Australia Wide Tax Solutions specialises in preparing rental property schedules, ensuring you claim every legitimate deduction while remaining fully compliant with the ATO. Whether you're a first-time investor or managing a large portfolio, our expert accountants can provide the clarity and support you need. Book a consultation today to make your investment work smarter for you.
Depreciation reduces an asset's cost base. When you sell, previously claimed Division 40 depreciation triggers a balancing adjustment. For Division 43 capital works deductions claimed from 1 July 2017, the amount reduces the building's cost base, increasing the eventual capital gain. The interaction between depreciation and CGT requires careful calculation at time of sale.
A quantity surveyor prepares a tax depreciation schedule by physically inspecting the property and identifying all depreciable assets and their values. The ATO accepts these estimates for depreciation claims where original receipts are unavailable. The fee is tax deductible. A schedule maximises your annual depreciation claims based on a comprehensive site assessment.
Division 43 covers the capital works deduction on structural components (walls, floors, roof) at 2.5% per year for buildings constructed after 15 September 1987. Division 40 covers plant and equipment (appliances, carpet, blinds) depreciated over their ATO-determined effective life. Post-May 2017 legislation restricts Division 40 claims on second-hand residential assets for new buyers.
Yes. The May 2017 restrictions on second-hand plant and equipment only apply to residential properties. Commercial property investors can still claim Division 40 depreciation on second-hand assets. Division 43 capital works deductions apply to both property types based on construction date, not acquisition date.
Keep the purchase contract, settlement statement, receipts for capital improvements, and a quantity surveyor's depreciation schedule. The ATO can request these records for five years after the relevant income year. Without records, depreciation claims can be reduced or disallowed on audit, and you may lose the ability to substantiate cost base adjustments at sale.
