

Understanding the Core Concept of Negative Gearing
Think of a negatively geared property like planting a fruit tree. In the early years, you’re spending money on water, fertiliser, and general care (your expenses) long before you see a single piece of fruit (your rental income). It costs you money out-of-pocket, but you're not just throwing cash away. You’re nurturing an asset that you expect to grow significantly in value over time, eventually becoming very profitable. That’s the essence of negative gearing in Australia—it’s a forward-thinking strategy, not a sign of a failing investment. A property is officially 'negatively geared' when its deductible running costs are greater than the income it generates, creating a net rental loss. Under Australian tax law, this loss isn't just a setback; it's a tool. Investors can offset this loss against their other income, like the salary from their day job.How It Impacts Your Tax
The immediate appeal of negative gearing is its effect on your tax bill. By lowering your total taxable income, you reduce the amount of tax you owe the ATO. For most people, this results in a bigger tax refund at the end of the financial year. That refund can then be used to help cover the cash shortfall required to hold onto the property each month.The goal isn't to lose money forever. It's a calculated trade-off: accept a manageable cash flow loss today in exchange for a potential tax benefit now and, most importantly, significant capital growth in the future.
Positive vs Negative Gearing at a Glance
To really get your head around negative gearing, it helps to see how it stacks up against the alternatives. Most property investments will fall into one of these three camps.| Gearing Type | Income vs Expenses | Impact on Your Taxable Income | Primary Investment Goal |
|---|---|---|---|
| Negative Gearing | Expenses are higher than income | Reduces taxable income | Capital Growth |
| Neutral Gearing | Income and expenses are roughly equal | No significant impact | Balanced Growth & Income |
| Positive Gearing | Income is higher than expenses | Increases taxable income | Positive Cash Flow |
Key Elements at Play
For this strategy to actually work, a few critical pieces of the puzzle have to fit together perfectly. You need to understand how each one contributes to the big picture.- Rental Income: This is simply the total rent you get from your tenants. Knowing what is rental income and how the ATO sees it is the absolute first step.
- Deductible Expenses: These are all the costs you can claim that are related to owning and managing the property. We're talking loan interest, council rates, insurance, property management fees, repairs—the lot.
- Capital Growth: This is the big one. It’s the increase in your property’s market value over time. Without strong capital growth, the whole strategy falls apart, as this is what's meant to ultimately outweigh all the short-term losses you've accumulated.
How Negative Gearing Actually Works for You
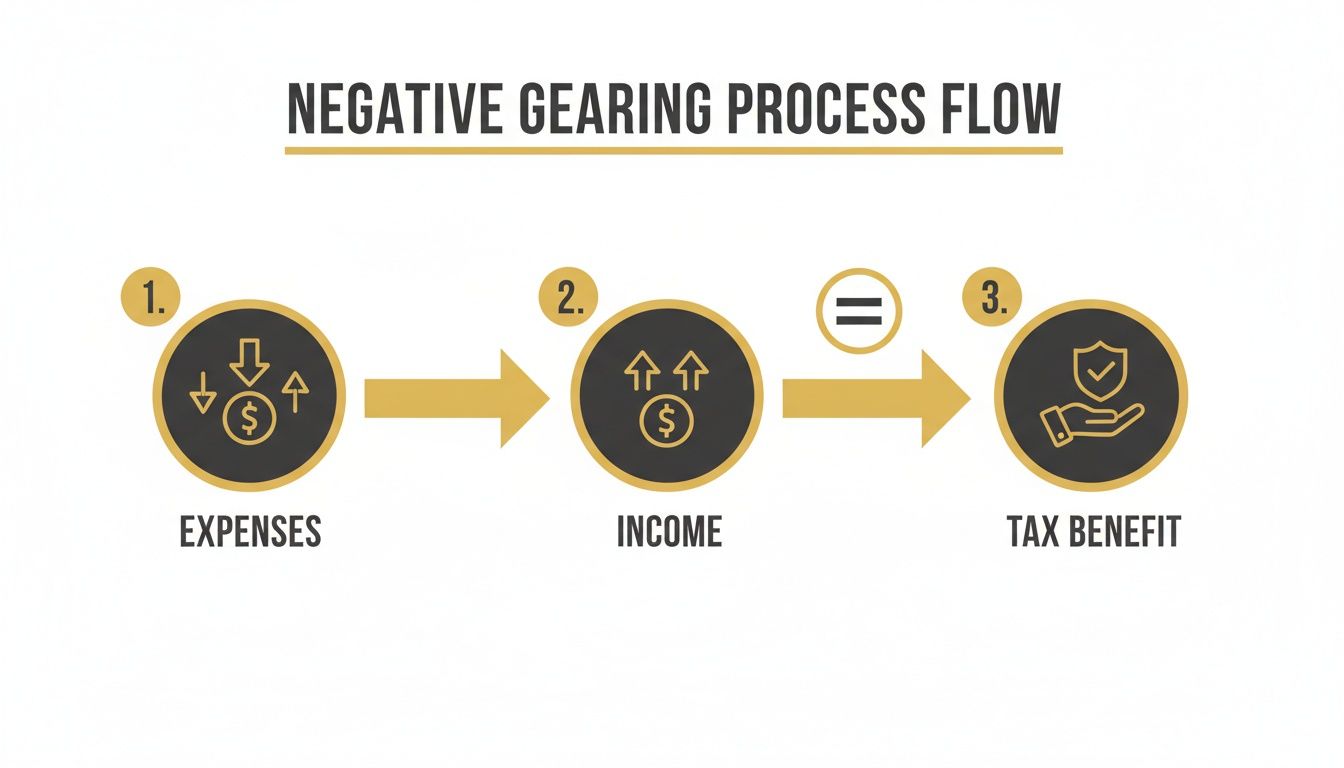
Theory is one thing, but seeing how negative gearing plays out with real numbers is where it all starts to click. Let's walk through the practical steps of how a negative gearing property investment directly impacts your finances, specifically within the Australian tax system. It all boils down to a simple bit of maths. You add up all the money your property brings in, then subtract every dollar you spend keeping it running.The Fundamental Formula: Rental Income - Deductible Expenses = Net Rental Profit or LossWhen your expenses are higher than your income, you have a net rental loss. This "loss" is the key to unlocking the tax benefits of the strategy.
Identifying Your Deductible Expenses
First things first: you need to track every single cost tied to owning and managing your investment property. The Australian Taxation Office (ATO) allows a surprisingly wide range of claims, and each one helps build your net rental loss. Common expenses you can claim include:- Loan Interest: This is usually the big one—the interest component of your mortgage repayments.
- Council and Water Rates: The regular bills from your local council and water authority.
- Insurance: Landlord insurance, building insurance, and public liability cover all count.
- Property Management Fees: What you pay a real estate agent to look after the tenancy.
- Repairs and Maintenance: The cost of fixing a leaky tap, patching a fence, or other general upkeep. Just be aware that initial repairs for damage that was there when you bought the place are treated differently.
- Strata Levies: For units or townhouses, these are the regular fees for maintaining common areas.
A Practical Walk-Through Example
Let's put this into practice with a real-world scenario. Meet Alex, a savvy investor. Alex earns a salary of $100,000 a year from his job as a graphic designer. He's just bought an investment property that brings in $26,000 in annual rent ($500 per week). Over the financial year, his property expenses add up:- Loan Interest: $25,000
- Council & Water Rates: $3,000
- Insurance: $1,500
- Property Management Fees: $2,000
- Repairs & Maintenance: $2,500
Connecting the Loss to Your Tax Return
Now for the final piece of the puzzle: applying this loss to Alex's tax return. The net rental loss from his property is deducted directly from his other taxable income.- Original Taxable Income: $100,000
- Net Rental Loss: -$8,000
- New Taxable Income: $92,000
The Real Pros and Cons of This Investment Strategy
The Major Advantages of Negative Gearing
The whole appeal of this strategy really boils down to two key benefits that work hand-in-hand to grow your net worth over time. These are the main reasons thousands of ordinary Aussies use negative gearing to get ahead. First up, you get an immediate tax benefit. That net rental loss you make each year isn't just a number on a spreadsheet; you can deduct it from your other income, like your salary. This move directly lowers your taxable income for the year, which usually means a healthier tax refund comes your way. And that refund is a crucial piece of the puzzle. Most investors use that lump sum to help cover the out-of-pocket costs from the year, making the whole venture much more sustainable. The second, and arguably the most important, benefit is the potential for long-term capital growth. This is the end game. While the tax perks help you hang onto the property, the real payday comes when the asset's value has climbed significantly over the years.A successful negative gearing strategy is built on the belief that the future capital gain will dwarf the total short-term losses you rack up along the way. When it works, it’s a powerful wealth-building engine.
The Unavoidable Risks and Disadvantages
As good as the benefits sound, the risks are just as real and need your full attention. Turning a blind eye to the downsides can lead to a world of financial pain, so it’s vital to be prepared for what could go wrong. The most immediate sting is the consistent cash flow shortfall. Every single month, the rent you collect won't be enough to cover the mortgage and all the other running costs. This means you absolutely must have enough spare cash from your job or other sources to bridge that gap, month in and month out. It demands strict budgeting and a rock-solid financial footing. Another huge risk is a flat or falling property market. The entire strategy hangs on your property's value going up. If the market stagnates for years or, even worse, goes backwards, you're stuck covering a monthly loss with nothing to show for it. That's the nightmare scenario for any negatively geared investor. Finally, you've got to be ready for curveballs you can't control.- Rising Interest Rates: If rates go up, your mortgage repayments increase, making your monthly shortfall even bigger and putting more pressure on your budget.
- Extended Vacancy Periods: If your property sits empty for a couple of months, you’re on the hook for 100% of the costs with zero rental income to soften the blow.
- Unexpected Major Repairs: A burst hot water system or a fried air conditioner can set you back thousands in an instant, adding even more financial strain.
Who Actually Uses Negative Gearing in Australia?
The Real Demographics of Australian Investors
Let's cut through the myths and look at what the data actually tells us. The numbers from the tax office paint a surprisingly clear picture of the typical investor.Australian Taxation Office (ATO) statistics consistently show that the majority of people who negatively gear are not in the top tax brackets. They are the essential workers who form the backbone of our communities.Recent data busts the myth wide open. A massive chunk of the 1.26 million Aussies declaring a net rental loss are on pretty modest incomes. In fact, around 79% of these investors earn $80,000 or less per year. And they’re not building huge property empires, either. The vast majority (73%) own just one investment property. For most, this is about getting a single, solid foothold on the investment ladder. You can explore the detailed breakdown of these negative gearing facts for yourself.
A Strategy for Our Essential Workers
So, who are these everyday investors? The data on their professions is fascinating—they’re the people you see and rely on every single day. Some of the most common jobs using negative gearing include:- Teachers: Over 28,000 teachers (and another 54,000 in related teaching roles) are using the strategy.
- Nurses: More than 27,600 nurses are leveraging negative gearing to plan for their financial future.
- Clerical Staff: A huge 62,000 clerical and office workers are also active property investors.
- Salespeople: Around 47,000 salespeople are using this method to build wealth.
Why Middle-Income Earners Use This Strategy
For a teacher, a nurse, or an office administrator, a salary alone often isn't enough to guarantee a comfortable retirement. Negative gearing offers a potential pathway to bridge that gap. The tax benefits make holding onto the asset more affordable in the short term, while the property itself hopefully grows in value over the long haul. The goal isn't just about shaving a bit off a tax bill. It's about a long-term vision for financial security. It’s a strategy that demands careful planning and a stable income to cover the cash shortfall. For hundreds of thousands of Australian families, it represents a calculated decision: trade a small, manageable short-term loss for the potential of a life-changing long-term gain. This makes it less of a tax loophole and more of a democratising force in the property market.The True Cost and Economic Impact of Negative Gearing
While the tax return benefits for an individual investor are pretty clear, negative gearing is part of a much bigger, and often fiercely debated, economic puzzle. To really get it, you need to zoom out from your own tax situation and look at the strategy's true cost to the federal budget and what it’s actually supposed to do for the housing market. Negative gearing is a significant line item on the national balance sheet. It represents a hefty chunk of tax revenue the government deliberately gives up each year. This "cost" is simply the grand total of all the net rental losses claimed by property investors right across the country. And that cost has been climbing. Back in 2008-09, the total net rental loss claimed by investors was around $4.6 billion. Just a few years later, in 2012, it had jumped to $7.9 billion. More recently, the Parliamentary Budget Office (PBO) projects this trend will continue, with the foregone tax revenue expected to grow from $3.6 billion in 2014-15 to a forecast $8.2 billion by 2029-30. If you’re interested in the official numbers, you can learn more about the economic impact of these tax deductions from treasury reports.The Core Economic Justification
So, if it costs the government billions, why on earth does this policy exist? The main economic argument is that negative gearing acts as a powerful carrot, encouraging private citizens to invest in residential property. The idea is that this private investment boosts the total supply of rental housing available on the market. The logic is simple: more investors buying or building properties means more homes are available for tenants.By encouraging everyday Australians to become landlords, the government effectively outsources part of the job of housing the nation's renters. This takes some of the pressure off public and social housing systems.This increased supply is meant to foster a more competitive rental market, which, in theory, helps keep rent prices from spiralling out of control. It’s a policy designed to fire up housing supply using private-sector money.
A Real-World Policy Experiment
We don't just have to rely on theory to see what happens when this incentive is taken away. Australia actually ran a real-world policy experiment back in the 1980s that gives us a powerful case study. In July 1985, the Hawke Labor government abolished negative gearing for property investments. The plan was to close what was seen as a tax loophole and take some heat out of the property market. The results, however, were fast and dramatic.- Investment Dried Up: Without the tax break, private investment in property fell off a cliff.
- Rental Supply Shrank: Fewer new rental properties were coming onto the market.
- Rents Skyrocketed: With supply tightening, a rental crisis erupted. Rents in major cities like Sydney and Perth surged, putting immense pressure on tenants.
A Brief History of Negative Gearing in Australia
To really get your head around negative gearing’s role in today’s property market, it pays to look back. This isn’t some modern tax loophole; it’s a principle that’s been deeply woven into Australia’s economic fabric for over a century, shaping how we’ve invested in property for generations. The basic idea—that an investor can offset losses from one business against income from another—has been a fundamental part of our tax system for a very, very long time. It wasn't invented specifically for property; it just applies to it like any other business. For a negative gearing property investment, this simply means the annual loss can trim down the taxable income you earn from your day job. But that doesn’t mean it’s been a smooth ride. The policy's fairness and economic impact have been hotly debated for decades, which led to one of the most revealing economic experiments in our history.The Great Policy Experiment of the 1980s
The most dramatic chapter in this story unfolded in the mid-80s under the Hawke Labor government. Facing concerns about housing affordability and tax fairness, the government made a bold call. On 1 July 1985, it effectively scrapped negative gearing, stopping new investors from deducting rental losses against their salaries. The goal was to cool the property market and level the playing field. What happened next, however, was a swift, severe, and largely accidental lesson in supply and demand.Almost overnight, private property investment dried up. With the tax incentive gone, fewer people were willing to buy or build rental homes, causing the supply of available properties for tenants to shrink dramatically.This sudden vacuum in the rental market created a perfect storm, especially in the big cities.
- Soaring Rents: With fewer properties to go around, landlords could charge a whole lot more. Sydney, in particular, saw sharp and painful rent increases.
- Plummeting Vacancy Rates: The number of empty rental properties dropped to crisis levels, making it incredibly tough for families to find a place to live.
- Intense Public Pressure: Tenants were facing a brutal rental market. The outcry from renters, along with the property industry, put immense pressure on the government to do something.
Common Questions About Negative Gearing
Even after you get your head around the basics, diving into a negative gearing property investment can still throw up a few tricky questions. Getting clear, no-nonsense answers is the key to feeling confident before you jump into what is a serious long-term strategy. Let's tackle some of the most common queries we hear from investors just starting out.Is Negative Gearing Only for High-Income Earners?
This is probably the biggest myth in property investing, and it’s just plain wrong. While it's true that the tax breaks are more significant for those on the highest marginal tax rates, the data from the Australian Taxation Office (ATO) tells a different story. Year after year, it shows the vast majority of people using negative gearing are everyday, middle-income Aussies. We're talking about teachers, nurses, and office workers. For them, it’s not some clever tax dodge; it's a practical way to get a foothold in the property market and build a nest egg for their future, rather than just hoping their super will be enough.What Happens When My Property Becomes Positively Geared?
Honestly, this is the endgame for most investors. It’s the moment your property grows up. It becomes positively geared when the rental income finally overtakes all your deductible expenses, meaning it's paying for itself and then some. This usually happens after years of rental increases or after you've hammered down a good chunk of your mortgage. When this switch happens, you no longer have a rental loss to claim against your salary. Instead, the property is turning a profit, which gets added to your taxable income. Yes, it means you'll pay a bit more tax, but that's a great problem to have. It's the sign of a healthy, self-sustaining investment that's now putting cash back into your pocket.Becoming positively geared is a huge milestone. Your property transforms from a wealth-building asset you have to financially support into one that actively boosts your monthly income.
Can I Claim Depreciation on My Investment Property?
Absolutely, and if you're not, you're leaving money on the table. Depreciation is a fantastic non-cash deduction that can make your on-paper loss much bigger, which directly translates to a larger tax refund. It's simply an allowance for the natural wear and tear on the building and its fittings over time. There are two main types you can claim:- Capital Works (Division 43): This is for the building's core structure—think the original roof, walls, floors, and foundations.
- Plant and Equipment (Division 40): This covers all the removable items inside, like ovens, carpets, blinds, hot water systems, and air conditioners.
What Are the Biggest Risks of Negative Gearing?
Let's be clear: this whole strategy lives or dies on one thing—future capital growth. The number one risk is that the property’s value simply doesn't grow as you hoped. If the market goes flat or, even worse, drops, you're stuck covering a very real cash loss every single month for absolutely no long-term gain. Beyond that, there are other serious risks to watch out for:- Rising Interest Rates: A jump in rates will blow out your mortgage repayments and make that monthly cash shortfall even deeper.
- Long Vacancy Periods: An empty property is a financial drain. You get zero rental income, but the bills—mortgage, council rates, insurance—keep coming.
- Unexpected and Costly Repairs: A burst pipe or a broken hot water system can create a sudden financial crisis you need to solve immediately.
Navigating the complexities of rental property deductions and capital gains is crucial for making your investment a success. The experts at Australia Wide Tax Solutions specialise in helping property investors maximise their returns and ensure full compliance. Book your consultation online or visit our Sydney office to get professional tax advice tailored to your investment goals.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
