

Before we even look at the specific australian non resident tax rates, we need to get one thing crystal clear: your tax residency status. This is the absolute starting point, because it decides how you’re taxed from your very first dollar earned in Australia.
Why does it matter so much? Because residents get a tax-free threshold, but non-residents don't. It's a game-changer.
How Australian Tax Residency Affects Your Tax Rate
Think of your tax residency status as the foundation of your entire Australian tax situation. It has very little to do with your passport or where you happen to be standing at any given moment. Instead, it’s a specific label the Australian Taxation Office (ATO) gives you based on your unique ties to the country.
It's a bit like a club membership. Tax residents are 'members' and get certain perks – the biggest one being the tax-free threshold. This means they can earn a certain amount of income each year before paying a cent of tax. Non-residents, or 'non-members', miss out on this benefit and are taxed on their Australian-sourced income right from dollar one.
The Key Residency Tests Explained
To figure out which category you fall into, the ATO uses a few different tests. It’s not a simple pass/fail on a single question; they look at the whole picture of your life and connections to Australia. The main one is called the 'resides test'.
The resides test is basically a common-sense check to see if you are genuinely living in Australia. The ATO will look at things like your physical presence, why you’re in the country, where your family and business connections are, and where you keep your assets. It’s a holistic view.
If the resides test doesn't make you a resident, the ATO has three other statutory tests up its sleeve.
- The Domicile Test: This one looks at your permanent home. If your permanent home, by law, is in Australia, you're usually considered a resident unless the ATO is convinced your permanent place of living is actually outside Australia.
- The 183-Day Rule: If you're physically in Australia for more than half the financial year (183 days or more), you might be considered a resident. But it’s not automatic. It also depends on whether your usual home is outside Australia and if you have no plans to actually live here long-term.
- The Superannuation Test: This is a specific one for Australian government employees working overseas in certain roles and who are members of specific government super schemes.
Getting your head around these rules is vital. You can dive deeper into all the specifics in our detailed guide on the Australian tax residency test.
Real World Scenarios of Residency Status
Let's put this into practice with two classic examples we see all the time.
Scenario 1: The Backpacker
A backpacker comes to Australia on a working holiday visa. Their goal is to travel around for a year, picking up casual jobs to fund their adventures. They live out of hostels, don't have a fixed address, and their family and main assets are all back home.
Even if they stay longer than 183 days, they'll almost certainly be classed as a non-resident for tax purposes. Everything about their behaviour points to them being a visitor, not someone setting up a permanent life here.
Scenario 2: The Expat
An engineer from overseas takes a two-year contract with an Australian company. She moves to Sydney with her family, signs a 12-month lease on a house, opens local bank accounts, and even joins the local footy club.
This person is a textbook example of an Australian resident for tax purposes. All her actions show she intends to make Australia her home, even if it's only for a fixed contract period.
Key Takeaway: Correctly figuring out your residency status is the single most important step. Get it wrong, and you could end up paying the wrong amount of tax and facing penalties from the ATO.
Nailing this from the start means you'll be applying the right tax rates and meeting your obligations without any nasty surprises.
Why Non Residents Are Taxed Differently
So, what’s the big deal about being a non-resident for tax purposes? It all boils down to one fundamental concept: the tax-free threshold. This is the single biggest financial perk for Australian residents, and as a non-resident, it’s completely off the table for you.
Think of the tax-free threshold as a yearly head start. For Australian residents, it’s a buffer that lets them earn up to $18,200 without paying a single cent in tax. It's designed to support those who live, work, and contribute to the Australian system.
As a non-resident, however, this benefit vanishes. This means you are taxed from the very first dollar you earn from an Australian source. There's no buffer, no allowance. Every dollar is on the ATO's radar.
The Logic Behind the Different Rules
The government's reasoning for this split is tied to a sort of social contract. The tax paid by residents funds the public services they directly use—things like healthcare, roads, and social security. The tax-free threshold is part of this system, offering some relief to those living within it.
Since non-residents typically aren't tapping into these local services in the same way, the tax system is structured differently. It simplifies things and makes sure your tax liability is linked to your economic connection to Australia, not your social one. This decision tree gives you a visual of the first few questions the ATO asks to figure out your residency status.
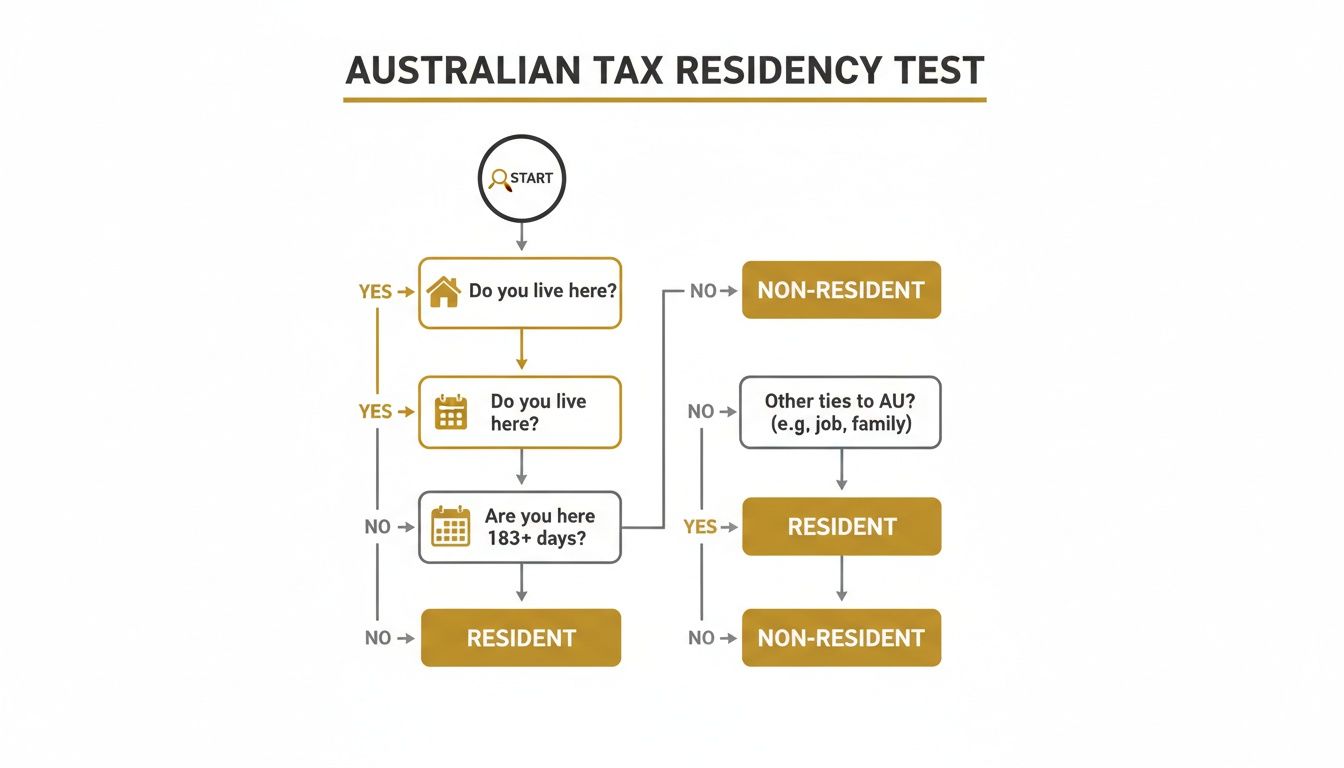
As the flowchart shows, simple questions about where you live and for how long are just the starting point. It’s not always straightforward.
This clear distinction in tax treatment has been in place since 1 July 2005. The Australian Taxation Office (ATO) applies higher marginal rates to ensure non-residents pay tax from dollar one of their Australian-sourced income. While a resident pays no tax on their first $18,200, a non-resident starts paying tax immediately, leading to a much higher tax bill on the same income.
Beyond the Tax-Free Threshold
Losing the tax-free threshold is the main event, but it's not the only difference that will affect your final tax bill.
- Limited Tax Offsets: Most tax offsets, which are direct discounts on the tax you owe, are off-limits for non-residents. A big one is the popular low-income tax offset.
- Medicare Levy Exemption: On the plus side, you almost certainly won't have to pay the Medicare levy, which is 2% of taxable income for most residents.
- Capital Gains Tax (CGT): The CGT rules are much tougher. Non-residents generally miss out on the 50% CGT discount for assets held for more than 12 months.
Key Insight: Being taxed differently isn't a penalty. It simply reflects your relationship with Australia. The system is designed to tax the economic activity you conduct here, separate from the benefits and obligations tied to being a permanent resident.
Understanding these differences is the first critical step. It explains why the Australian non resident tax rates are what they are, and why your tax outcome can look so different from that of a resident earning the exact same amount. If you're from a country with a tax treaty with Australia, it's also worth looking into how a Double Tax Agreement with Australia might affect your final position.
Current Australian Non-Resident Tax Rates and Brackets
Alright, let's get into the numbers—the part you've been waiting for. Understanding the specific Australian non-resident tax rates is the key to figuring out your tax bill. Unlike the resident tax system, which gives Aussies a generous tax-free threshold, the non-resident system is brutally simple: you pay tax from the very first dollar of Australian-sourced income you earn.
This section will walk you through the brackets, show you how they work, and clarify what kind of income the Australian Taxation Office (ATO) actually cares about. My goal is to make sure you can calculate your tax obligations with confidence.
Understanding Marginal Tax Rates
Before we jump into the table, you need to get your head around Australia's marginal tax rate system. It’s a progressive system, which just means the more you earn, the higher your tax rate becomes—but crucially, that higher rate only applies to the slice of income within that specific bracket.
Think of your income like water filling a set of buckets, with each bucket representing a tax bracket.
- Your first lot of earnings starts filling the first bucket. Every dollar in this bucket gets taxed at the lowest rate.
- Once that bucket is full, any extra income spills over into the next bucket.
- The money landing in this second bucket is taxed at a higher rate than the first.
- This continues for each bracket.
This setup ensures you don't suddenly get hit with a higher tax rate on all your income just because you earned one dollar over the threshold. It's a much fairer way of doing things.
Australian Tax Rates for Foreign Residents
Now for the main event. Here are the current income tax brackets that apply to non-residents for tax purposes. Remember, these rates only hit your Australian-sourced income.
| Taxable Income | Tax on this Income |
|---|---|
| $0 – $120,000 | 32.5 cents for each $1 |
| $120,001 – $180,000 | $39,000 plus 37 cents for each $1 over $120,000 |
| $180,001 and over | $61,200 plus 45 cents for each $1 over $180,000 |
As you can see, the tax kicks in at a hefty 32.5% from your very first dollar. This is a massive shock for many, especially when compared to the resident system where the first $18,200 is completely tax-free.
Key Insight: The absence of a tax-free threshold is the single biggest factor affecting a non-resident's tax bill. Two people earning the exact same income can end up with wildly different tax outcomes based purely on their residency status.
What Is Australian-Sourced Income?
Knowing the rates is only half the battle. You also need to know exactly which income they apply to. The ATO is only interested in your Australian-sourced income—that is, any money you make that has a direct link to Australia.
Some of the most common examples we see include:
- Employment Income: This is the big one. It covers any salary or wages you were paid by an Australian employer for work you physically did in Australia.
- Rental Income: If you own an investment property down under—say, an apartment in Melbourne—the rent you collect is Australian-sourced.
- Capital Gains: Any profit you make from selling certain Australian assets, most commonly real estate, is taxed here.
- Business Income: Money earned from a business that you operate within Australia falls squarely into this category.
- Royalties and Dividends: Payments you receive from Australian companies or for the use of assets located in Australia are also included.
Put simply, if the economic activity that generated the cash happened in Australia, the ATO considers it taxable here. This rule ensures your tax obligations are tied directly to the profits you pull from the Australian economy, no matter where you live now. Getting these definitions right is crucial for correctly declaring your income and applying the right Australian non-resident tax rates.
How Different Types of Income Are Taxed
Getting a handle on the core Australian non resident tax rates is the first step, but it's only half the story. The next crucial piece of the puzzle is understanding that not all income you earn in Australia gets treated the same way. The Australian Taxation Office (ATO) has different rules depending on where the money comes from, so a one-size-fits-all approach just won't cut it.
Think of it like different types of fuel for a car. Your regular salary is like standard unleaded—it goes through the main tax engine using the marginal rates. But things like investment returns are more like a premium or specialty fuel, and they go through a completely different process.
This section breaks down how the ATO handles your main income streams: employment, passive investments, and capital gains.
Knowing these distinctions is absolutely essential for filing your tax return correctly and avoiding a nasty surprise from the ATO.
Employment and Personal Services Income
For most non-residents, income from your job is the main thing you'll be dealing with. This bucket includes your salary, wages, commissions, or any bonuses you get from an Australian employer for work you do in Australia. This is the income that gets taxed at the marginal non-resident rates we've already covered.
Thankfully, the process is usually pretty straightforward because of the Pay As You Go (PAYG) withholding system. Your employer estimates the tax you’ll owe on each payslip and sends that money directly to the ATO for you. This means the tax is taken out before the money even hits your bank account.
When it's time to lodge your annual tax return, you declare your total income and the total tax that’s already been paid. The tax return then squares everything away, confirming if the right amount was withheld.
Passive Income from Investments
Now, this is where things get interesting. Passive income, like interest from an Aussie bank account or dividends from Australian shares, is treated very differently. Instead of adding it to your other income and taxing it at your marginal rate, this income is usually hit with a final withholding tax.
This is a flat-rate tax that the person or company paying you (like the bank or the company paying the dividend) withholds and sends straight to the ATO. It's done and dusted.
- Interest: A final withholding tax of 10% is normally applied to interest paid to non-residents.
- Dividends: The rate here is usually 30%. However, this can be lower if you live in a country that has a specific tax treaty with Australia.
Key Takeaway: The beauty of the withholding tax system is its simplicity. Once that flat rate is withheld, that income is dealt with. You generally don't even need to declare it on your Australian tax return, as your tax obligation has already been sorted.
This makes life much easier for non-residents with straightforward investment portfolios. It’s still critical, though, to check the details of any tax treaties that might apply to your situation.
Capital Gains Tax for Non-Residents
Capital Gains Tax (CGT) is an area where the rules for non-residents get particularly strict. A capital gain is the profit you make when you sell an asset, and when it comes to non-residents, the ATO is really only focused on one major asset class: Australian real estate.
Unlike residents, who pay CGT on most assets they own worldwide, non-residents are generally only liable for CGT when they sell what the ATO calls 'taxable Australian property'. Most of the time, this means:
- Real estate located in Australia (a house, apartment, or block of land).
- Certain business assets used in a business based in Australia.
But here’s the biggest kicker for non-residents: the denial of the 50% CGT discount. Australian residents who own an asset for more than 12 months can cut their taxable capital gain in half. Non-residents lost this massive concession for any assets they bought after 8 May 2012.
Let that sink in. If you make a $100,000 capital gain on an Australian property, a resident might only pay tax on $50,000 of it. As a non-resident, you’d be taxed on the full $100,000, which can make a dramatic difference to your final tax bill.
How to File Your Australian Tax Return from Overseas
Knowing the Australian non-resident tax rates is one thing, but that knowledge is pretty useless if you can't actually lodge your tax return correctly. For non-residents living abroad, the whole process can feel a bit daunting, full of strange forms and deadlines you're not used to. This is your practical, no-stress guide to getting it done.
We'll walk through the essential steps, from making sure you have a Tax File Number (TFN) to getting your documents in order and choosing the smartest way to lodge. The goal here is to take the mystery out of it so you can meet your obligations with confidence and on time.
Getting Started: Your Filing Checklist
Before you even think about lodging, there are a few things you absolutely must have in place. Think of this as your pre-flight check for a smooth tax journey.
- Get a Tax File Number (TFN): Your TFN is a unique nine-digit number that the Australian tax system uses to identify you. If you’ve worked in Australia before, you'll already have one. If not, applying for a TFN is the mandatory first step.
- Gather Your Income Statements: Round up all your relevant income summaries. This means your income statement (which used to be called a PAYG payment summary) from your employer, plus details of any other income you earned from Australian sources, like rental income or capital gains.
- Note the Key Deadlines: The Australian financial year runs from 1 July to 30 June. If you’re lodging the return yourself, the deadline is almost always 31 October. Pop that in your calendar, because missing it can lead to penalties.
It's worth remembering why this is so important to the Australian government. Personal income tax, which covers both residents and non-residents, has ballooned from 40% of Commonwealth tax receipts back in the 1950s to a projected 56% for the 2024–25 financial year. This context, which you can read more about at the Treasury, explains why the Australian Taxation Office (ATO) has such specific rules—it's their primary source of revenue.
Choosing Your Lodgement Method
Once your documents are ready, you’ve got three main ways to get your return to the ATO. Each has its own pros and cons, and the best one for you really depends on your circumstances.
- Online with myGov: If you have a myGov account linked to the ATO, this seems like a convenient option. The catch? Setting this up from overseas can be a nightmare if you don't have an Australian phone number or bank account for all the identity verification steps.
- By Paper Form: This is the old-school method. You download the paper tax return form, fill it out by hand, and mail it to the ATO. It's straightforward but incredibly slow, offers zero guidance, and leaves a massive margin for error.
- Using a Registered Tax Agent: For most non-residents, this is the most sensible and stress-free way to go. A qualified tax agent who specialises in expat tax issues already knows all the specific challenges you're facing.
Key Insight: A tax agent can do more than just make sure your return is accurate. They can legally lodge it for you, often with a much later deadline that extends well past 31 October. That extra time and expertise can be a lifesaver.
For a more detailed look at the steps involved, check out our guide on lodging a non-resident tax return in Australia. Hiring a professional is especially valuable if your finances involve multiple income streams or tricky capital gains calculations. They make sure you tick every box and avoid any costly mistakes.
Common Tax Mistakes Non-Residents Make
Trying to navigate Australia’s tax system from the outside can feel like a minefield. It’s all too easy to make a simple mistake that ends up being surprisingly expensive. Knowing the common pitfalls ahead of time is your best defence to meet your obligations and stay on the right side of the Australian Taxation Office (ATO).
Most of these errors come from straightforward misunderstandings about how the rules apply to non-residents, and thankfully, they are easily avoided with a bit of planning. Think of this section as your essential checklist for getting it right from day one.
Incorrectly Determining Your Residency Status
This is, without a doubt, the biggest and most costly mistake we see. Many people assume that because they’re on a temporary visa or only plan to be in Australia for a short time, they are automatically a non-resident for tax purposes. That's a dangerous assumption.
The ATO's residency tests are complex. They look at your behaviour, your ties to the country, and your intentions—not just your visa status. Getting this wrong means you might incorrectly apply the Australian non-resident tax rates or, even worse, claim the tax-free threshold you aren't entitled to. This can lead to a significant tax debt and penalties down the track.
Key Takeaway: Never guess your residency status. Always work through the ATO's official tests or get professional advice to be certain before you lodge your first tax return.
Forgetting to Declare All Australian Income
Another frequent slip-up is failing to declare every dollar earned from Australian sources. Your main salary from an employer is usually the easy part, but it’s the other income streams that often get forgotten.
This can include things like:
- "Side-hustle" income from freelance gigs or delivery driving.
- Interest earned sitting in an Australian bank account.
- Capital gains from selling Australian assets, like property.
- Rental income collected from an Australian investment property.
The ATO has incredibly sophisticated data-matching systems that link up with banks, employers, and other government agencies. It's not a matter of if they find undeclared income, but when. Always report everything.
Misunderstanding Superannuation Tax Rules
Finally, the rules around superannuation create a lot of confusion and headaches. When you leave Australia for good, you can claim your super back through a Departing Australia Superannuation Payment (DASP). The catch? This payment is taxed.
The tax rate on your DASP depends on various factors within your super fund, and many people are shocked to find a hefty chunk is withheld. It’s vital to understand these specific tax implications before you apply to get your super back, so you know exactly what to expect. This simple step ensures there are no nasty financial surprises when you're finalising your affairs in Australia.
Your Top Questions Answered
Trying to get your head around Australian tax rules from overseas can feel like a minefield. To clear things up, here are some straight answers to the questions we hear most often from non-residents.
Can I Claim the Tax-Free Threshold as a Non-Resident?
Unfortunately, no. This is one of the biggest shocks for many non-residents. While Australian residents get to earn up to $18,200 tax-free, this privilege is not available to you.
As a non-resident, you’re taxed on every single dollar of Australian-sourced income you earn, right from the very beginning.
Do Non-Residents Pay the Medicare Levy?
Generally, you don't. The Medicare levy is a 2% tax on income that helps fund Australia’s public health system, and it usually only applies to Australian residents.
If you find that tax for Medicare has been accidentally withheld from your pay, don't worry. You can claim an exemption when you lodge your tax return to get that money back.
What Is the Deadline for Lodging My Tax Return?
The Australian financial year is a bit different from many other countries, running from 1 July to 30 June.
If you're lodging your own tax return, the deadline is strictly 31 October. However, working with a registered tax agent like us at Australia Wide Tax Solutions gives you a massive advantage—we can often secure an extended deadline, sometimes pushing it well into the next year.
Key Reminder: Missing the lodgement deadline isn't something the Australian Taxation Office (ATO) takes lightly. It can lead to penalties and interest charges that quickly add up. It’s always smarter to file on time or get a professional on your side who can lock in an extension.
What Happens If I Don't Lodge a Tax Return at All?
Ignoring your tax obligations is a serious misstep. The ATO has powerful systems designed to find people who've earned income in Australia but haven't filed a return.
Getting caught can result in hefty penalties, interest charges on what you owe, and could even create problems for future visa applications or your ability to come back to Australia. It's always better to face your obligations, even if you’re lodging late.
Making sense of the australian non resident tax rates from the other side of the world is tough. For real peace of mind and expert guidance, you can trust the professionals at Australia Wide Tax Solutions. We specialise in making sure non-residents get their tax right, without the stress.
Let us handle the complexity so you can get on with what's important.
The ATO provides guidance through ato.gov.au, the Small Business Support Line (13 28 66), and Online Services for individuals and businesses. For complex situations, a registered tax agent provides advice tailored to your specific circumstances and professional indemnity protection. You can verify agent registration at the TPB register at tpb.gov.au.
Most tax records must be kept for five years from the date of lodgement or the date the transaction occurred, whichever is later. Records must be in English or convertible to English and must be sufficient to explain the income and deductions in your return. The ATO can request records at any time during the retention period.
Consider a registered tax agent when your affairs involve multiple income sources, business activity, investment properties, capital gains, or overseas income. Agents extend your lodgement deadline, provide safe harbour protection, and take professional responsibility for the advice given. Verify registration at tpb.gov.au.
The failure to lodge penalty is based on penalty units ($313 per unit from 1 July 2023), accruing per 28-day period for late returns and BAS lodgements. Incorrect information penalties range from 25% to 75% of the tax shortfall depending on whether the behaviour was careless, reckless, or intentional. Proactive disclosure before an audit begins typically results in significantly reduced penalties.
Tax minimisation is the legal arrangement of your affairs to reduce tax — claiming all eligible deductions, using appropriate structures, and timing income and expenses. Tax avoidance involves arrangements that technically comply with the law but achieve outcomes parliament did not intend. The ATO can apply Part IVA anti-avoidance rules to cancel benefits from avoidance arrangements.
