

Of course. Many of the costs you sink into your rental property can be claimed as tax deductions in Australia. The main condition is that the property was genuinely on the rental market when you incurred the expense.
- Understanding Your Rental Property Tax Deductions
- Claiming Interest on Your Investment Loan
- Capital Works and Depreciation Deductions Explained
- Claiming Your Day-to-Day Running Costs
- Common Mistakes and ATO Focus Areas
Getting these deductions right can seriously reduce your taxable income and give your investment’s cash flow a healthy boost. But it’s crucial to know exactly which costs are eligible and how to claim them correctly.
Understanding Your Rental Property Tax Deductions
The easiest way to think about this is to treat your rental property like a small business. Any legitimate cost you incur to earn rental income is a potential tax deduction. This guide is here to demystify the world of rental property tax deductible expenses for Aussie investors.
The Australian Taxation Office (ATO) sorts these deductions into three main buckets, based on when you can claim them. Getting your head around these categories is the first step to legally shrinking your tax bill and making smarter investment moves. When you get it right, you not only improve your cash flow but also keep the ATO happy, avoiding the stress of a potential audit.
The Three Types of Rental Deductions
The secret to maximising your claims is understanding that the ATO doesn't treat all expenses the same. You can't just claim everything in the same financial year you paid for it.
Immediate Deductions: These are the costs you can claim in full in the same income year you paid them. They're usually the day-to-day running expenses, like council rates, property management fees, and minor repairs.
Deductions Over Several Years: Some expenses provide a benefit that lasts longer than one year, so you have to spread the claim out over a set period. A classic example is borrowing expenses, such as loan setup fees, which are typically claimed over five years.
Capital Works Deductions: These deductions are for the big-ticket items—the building's structure itself and any major improvements you make. Known as Division 43 deductions, you can generally claim these costs at a rate of 2.5% per year for up to 40 years from the date the construction was completed.
To help you get a quick handle on what's what, we've put together a simple summary table. This is your go-to reference for spotting common deductions and understanding when you can claim them.
At-a-Glance Guide to Common Rental Deductions
| Expense Category | What It Covers | When to Claim |
|---|---|---|
| Running Costs | Council rates, water charges, land tax, property management fees, advertising for tenants. | Immediately (in the year incurred) |
| Maintenance & Repairs | Fixing a broken window, plumbing repairs, replacing a faulty appliance with a similar model. | Immediately (if it's a repair, not an improvement) |
| Borrowing Expenses | Loan application fees, lender's mortgage insurance, title search fees. | Over 5 years (if over $100) |
| Depreciating Assets | Ovens, dishwashers, carpets, blinds, air conditioners. | Over the asset's effective life (depreciation schedule) |
| Capital Works | Building construction costs, major renovations, structural improvements. | Over 40 years (at 2.5% per year) |
This table is a great starting point, but remember that every investor's situation is unique. The key is to keep meticulous records for every dollar you spend.
The core principle is simple: if you spent money to generate rental income, that expense is likely deductible. The complexity lies in figuring out when and how much you can claim.
For a deeper dive into how to legally reduce your taxable income and keep more of your earnings, you can explore detailed strategies on how to Maximize Your Short Term Rental Tax Deductions. This approach helps you make the most of every eligible expense.
Claiming Interest on Your Investment Loan
For most Aussie property investors, the interest you pay on your investment loan is the single biggest tax deduction you can claim. It's often the cornerstone of making a property investment financially viable.
But it’s not as simple as just claiming every dollar of interest paid. The Australian Taxation Office (ATO) has a very clear rule that governs this deduction: the 'purpose test.' Think of it like this: the ATO only allows you to claim interest on the portion of the loan that was used to produce rental income. Getting this right is absolutely crucial.
The Critical Purpose Test
This test is pretty straightforward if you take out a single loan to buy one rental property. Simple. But where things get messy is when you start redrawing from that loan or refinancing and using some of the money for personal reasons.
Maybe you used a redraw to buy a new car, pay for a family holiday, or clear some credit card debt. Once you do that, the loan has a mixed purpose.
You absolutely must apportion the interest. You can only claim the slice of the interest that directly relates to the investment property. Mixing personal and investment funds in the same loan account is a classic mistake, and it's a huge red flag for the ATO.
The ATO is laser-focused on this: you cannot claim interest on parts of a loan used for private expenses. It's one of the first things they look at during an audit, so keeping meticulous records isn't just a good idea—it's non-negotiable.
Let's look at an example. The ATO's guidance on rental property deductions is built around this 'purpose test.' If you borrowed $500,000 solely to buy a property that you rent out, then the interest on that entire amount is in play. At a rate of 6.5%, that could be around $32,500 in deductible interest for the year.
This simple flowchart helps you see where different types of expenses fit.
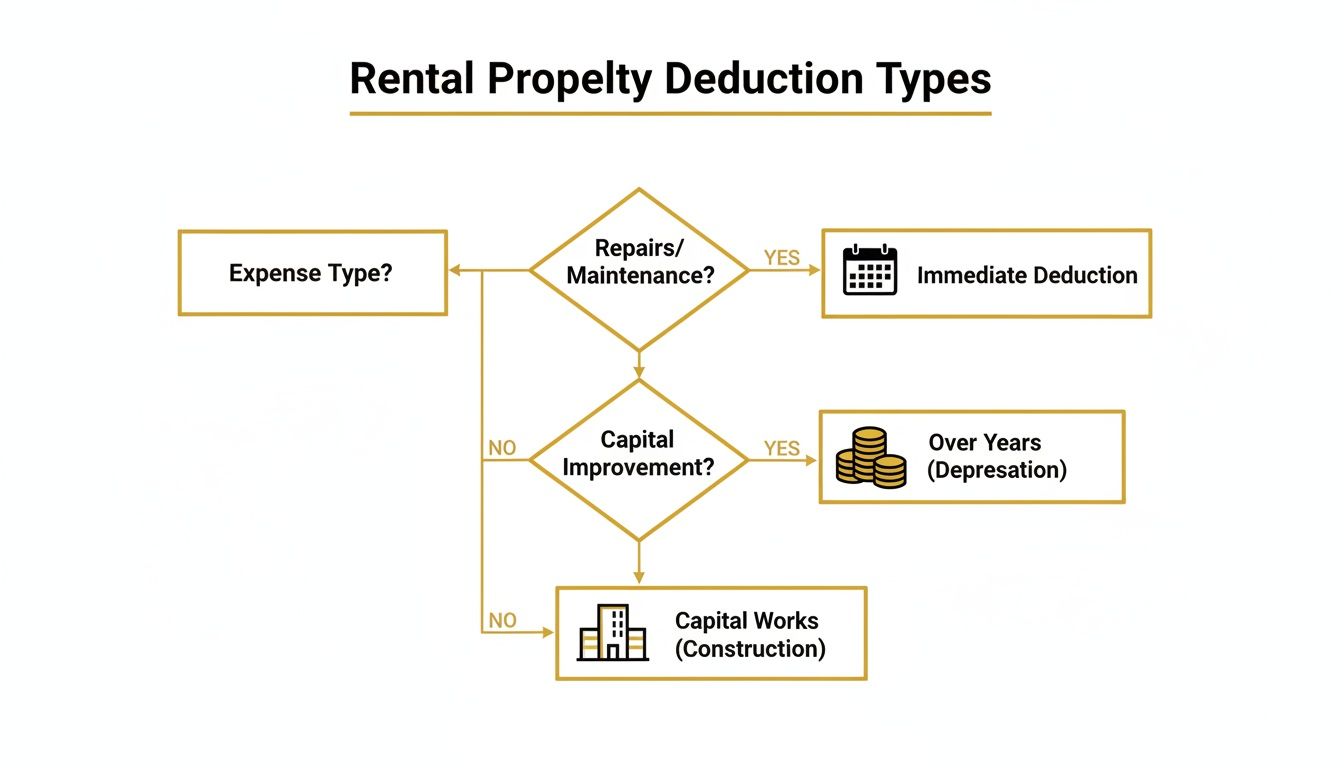
As the flowchart shows, expenses fall into different buckets. Some you can claim straight away, while others you have to claim over several years (depreciation) or as long-term capital works.
How to Calculate Your Claim Correctly
To make sure you're only claiming what you're entitled to and stay out of trouble with the ATO, you need to follow a clear process.
- Identify the Purpose: Go through your loan statements. Pinpoint exactly what every dollar drawn from the loan was used for. Was it for the deposit? Stamp duty? Or was it for a new boat?
- Separate the Portions: If your loan has a mixed purpose, you must calculate the exact percentage used for the investment versus your private life. The cleanest way to handle this is with a split loan from the very beginning.
- Calculate Deductible Interest: Apply the investment percentage to the total interest charged for the financial year.
For instance, say your $500,000 loan is split 80% for the rental property ($400,000) and 20% for personal use ($100,000). You can only claim 80% of the total interest paid on that loan. If you get this apportionment wrong, you could be facing hefty penalties.
Capital Works and Depreciation Deductions Explained
Beyond the day-to-day running costs, some of the most powerful deductions you can claim are what we accountants call 'non-cash' deductions. It’s a slightly strange concept, but it simply means you're claiming the gradual wear and tear on your property and everything in it—even though you’re not physically spending money on it that year.
These deductions fall into two main camps: Capital Works and Plant & Equipment Depreciation. Getting your head around both is absolutely essential if you want to unlock the full tax-saving power of your investment.
Capital Works Building Deductions
Think of Capital Works—also known as Division 43 deductions—as a claim for the ageing of the building's permanent structure itself. It covers the wear and tear on things that are fixed to the property, like the original walls, roof, floors, doors, and windows. It also applies to any major structural improvements or renovations you might undertake, such as building a new deck or remodelling a bathroom.
For properties that qualify, you can generally claim these costs at a set rate over a very long time. Capital works deductions allow you to claim 2.5% per year over 40 years on the building’s construction cost or improvements. So, if the eligible construction portion of your rental cost $400,000, you could claim a $10,000 deduction every single year, which makes a massive difference to your taxable income.
Plant and Equipment Depreciation
Plant and equipment (or Division 40) assets are all the items inside the property that have a limited lifespan. The easy way to think about them is as items that can generally be removed without causing major damage to the building.
A few common examples include:
- Ovens, cooktops, and rangehoods
- Carpets and vinyl flooring
- Blinds and curtains
- Air conditioning units
- Hot water systems
- Smoke alarms
Each of these items loses value over time, and you're able to claim that decline as a depreciation deduction. How much you can claim comes down to the asset’s cost and its ‘effective life’ as set out by the ATO. To really squeeze every last dollar out of these claims, it’s vital you understand how to calculate depreciation on your rental property the right way.
A critical rule change from May 2017 means you can no longer claim depreciation on previously used plant and equipment assets in second-hand residential properties. This means if you buy an established property, you can't claim the oven or carpets that were already there. However, you can still claim any brand-new assets you purchase and install yourself.
Because working out what’s what and putting a value on it all is so complex, getting a specialist involved is often the smartest move. A qualified quantity surveyor can inspect your property and put together a comprehensive tax depreciation schedule for you. This report splits out the capital works from the plant and equipment, values every item, and maps out the deductions you can claim for up to 40 years. It’s a one-off investment that very often uncovers thousands in deductions you would have otherwise missed.
Claiming Your Day-to-Day Running Costs
While the big-ticket items like loan interest grab most of the attention, the day-to-day running costs of your investment property are just as critical for your tax return. These are the expenses you can claim in full, in the same financial year you paid for them, giving you an immediate benefit.
Think of these as the essential, ongoing costs of keeping your rental property ticking over. They are routine, expected, and directly linked to earning that rental income.
Immediately Deductible Expenses
Some of the most common running costs you can claim as a rental property tax deductible expense cover a whole range of everyday payments.
- Council and water rates: These regular charges are fully deductible for the time your property was rented or genuinely on the market for rent.
- Land tax: This state-based tax is another immediate deduction that property investors can claim.
- Property management fees: Using an agent to manage tenants and collect rent? Their fees are a direct cost of doing business and are 100% deductible.
- Advertising for tenants: Any money spent listing your property online or in print to find new tenants can be claimed straight away.
Another significant running cost, and one that is generally tax-deductible, is insurance. A good landlord insurance policy is absolutely crucial for protecting your investment against risks like tenant damage or loss of rent. Keeping all your receipts and statements for these expenses is vital, and our guide on record-keeping requirements for the ATO can help you stay organised.
The Crucial Line Between Repairs and Improvements
This is a classic trip-up for many investors. The ATO draws a very clear line between a 'repair' and an 'improvement', and it massively changes when you can claim the cost.
A repair is work done to fix something that’s broken or worn out, simply to restore it to its original condition. Replacing a few cracked tiles or fixing a leaking tap are perfect examples. You can claim these costs immediately.
An improvement, however, is any work that makes something better, more valuable, or changes its character. Knocking out a wall for an open-plan living space or swapping a basic kitchen for a high-end one are clear improvements.
The key difference is restoration versus enhancement. Repairs restore function, while improvements add value or upgrade the asset. Improvements are treated as capital works and must be claimed over many years, not immediately.
Why Apportionment Is Non-Negotiable
You can only claim expenses for the period your property was genuinely available for rent. If you used the property for your own private holiday for four weeks of the year, you must reduce your claims to match.
For example, if the property was available for rent for 48 out of 52 weeks (that's about 92% of the year), you can only claim 92% of your running costs like council rates and insurance. The ATO's data-matching systems are very good at spotting incorrect apportionment, so getting this calculation right is essential to staying compliant.
Not all rental property expenses are a simple, one-off deduction. Some costs deliver a benefit that stretches far beyond a single financial year, and the Australian Taxation Office (ATO) needs you to account for them that way.
Think of it like paying for a five-year magazine subscription upfront. You wouldn't dream of claiming the entire cost in the first year because the benefit—the magazines arriving at your door—is spread over the full five years. The tax rules for certain long-term rental costs work on the exact same principle.
These specific costs are called borrowing expenses. They are the costs you paid directly to take out the loan used to buy your investment property.
What Are Borrowing Expenses?
Borrowing expenses are much more than just the interest on your loan. They cover a whole range of upfront fees you pay to secure the finance for your rental property.
The most common examples we see include:
- Loan establishment fees: These are the administrative charges your bank or lender hits you with just for setting up the loan.
- Lender’s Mortgage Insurance (LMI): This can be a huge one. It’s an insurance premium required by lenders when your deposit is below a certain threshold, usually 20% of the purchase price.
- Title search fees: The costs you pay a solicitor or conveyancer to check that the property’s title is clean and clear.
- Stamp duty on the mortgage: It's crucial to understand this is different from the stamp duty on the property purchase itself. Stamp duty on the mortgage is a borrowing expense, while stamp duty on the property is a capital cost.
- Mortgage broker fees: If you used a broker to find your loan, their commission or fee may be deductible here.
Here’s the key rule: if the total of these costs is over $100, the ATO requires you to claim the deduction over five years. If the total is $100 or less, you can claim the whole lot in the same financial year you paid it.
Example: You paid a $2,500 loan application fee to your bank. Because this is well over $100 and relates to the entire life of your loan, you have to spread the deduction over five years. This works out to a neat $500 deduction you can claim each year for five consecutive years.
A Common Mistake: Initial Repairs
One of the most frequent errors we see new investors make is getting tripped up by "initial repairs". They confuse these with the standard, immediately deductible repairs you make once a property is up and running.
If you buy a place that needs fixing up before you can rent it out for the first time, these costs are almost always considered capital expenses by the ATO.
For instance, say you buy a property with a broken back fence. You fix it before your first tenant even sees the place. That repair cost is not an immediate deduction. Instead, the ATO views it as part of the property's acquisition cost—you were improving the asset to get it ready for its income-producing life. This cost gets added to your property's cost base and is claimed over time as part of the capital works deduction, not as a lump sum repair.
Common Mistakes and ATO Focus Areas
Navigating your rental property deductions can feel a bit like walking a tightrope, but staying on the right side of the Australian Taxation Office (ATO) is easier than you think. The key is to avoid a few common, yet simple, errors. With powerful data-matching technology, the ATO is more skilled than ever at spotting incorrect claims, making rental properties a major focus area for them.
Understanding the common pitfalls is your best defence against a potential audit. So many investors trip up on the same few issues, turning legitimate tax savings into stressful compliance headaches. Think of this section as your checklist for sidestepping those mistakes and lodging your return with confidence.
Incorrectly Apportioning Expenses
One of the biggest red flags for the ATO is failing to properly apportion expenses for private use. This is a classic mistake, especially with holiday homes. If you used your beach house for a few weeks over summer or stayed in the property while doing renovations, you absolutely cannot claim 100% of the year's expenses. It’s a non-negotiable.
You must work out the percentage of the year the property was used privately and reduce your claims accordingly. This rule applies to every single cost, including loan interest, council rates, and insurance. The ATO scrutinises holiday home claims very closely, so it pays to be meticulous with your calculations.
A core ATO principle is that you can only claim expenses for the period your property was genuinely available for rent. Claiming deductions for periods of private use is a fast track to an audit and potential penalties.
Confusing Repairs with Improvements
Another frequent mix-up is misclassifying capital improvements as immediate repairs. The distinction is critical.
A repair restores something to its original working order—like fixing a broken fence panel. The cost is immediately deductible in the same financial year. An improvement, however, makes something better, different, or more valuable than it was originally. Think replacing the entire old fence with a new, modern one. These costs are capital in nature and must be depreciated over several years.
Similarly, be wary of initial repairs. Any work you do to fix defects that existed when you bought the property is generally considered a capital cost. These expenses are seen as part of acquiring the asset and must be claimed as capital works, not as an instant deduction.
Poor Record Keeping
Finally, we come to the most fundamental mistake of all: failing to keep good records. It might sound basic, but it’s the bedrock of every claim you make.
Without receipts, invoices, and bank statements to prove your expenses, your claims can be denied entirely during an audit. The ATO requires you to keep records for all income and expenses for five years after you lodge your tax return. Getting your documentation in order isn't just good practice; it's a non-negotiable requirement for claiming any rental property deduction.
Your Rental Property Tax Questions Answered
When you're navigating the world of rental property tax, a few common questions always seem to pop up. We hear them from investors all the time. Let's tackle some of the most frequent queries with clear, direct answers to help you stay compliant while making sure you claim everything you're entitled to.
Can I Claim Travel Expenses for Inspecting My Rental Property?
Unfortunately, the short answer is generally no. Since 1 July 2017, the ATO has disallowed deductions for travel expenses related to inspecting, maintaining, or collecting rent for a residential rental property.
There are some very limited exceptions, like for investors who are classed as carrying on a property rental business, but the criteria to qualify are incredibly strict. It’s always best to chat with a tax professional to see if your specific situation meets these narrow requirements before you even think about making a claim.
What Happens If My Rental Expenses Are More Than My Income?
When your total deductible expenses for the year are greater than your rental income, you have what's known as a 'negatively geared' property. This situation creates a rental loss.
This loss isn't just a number on a page; it can typically be offset against your other income, like your salary or business income. Doing this reduces your overall taxable income for the year. This is a common and completely legitimate tax strategy for many Australian property investors, turning a cash-flow loss into an immediate tax benefit.
The ability to offset rental losses against other income is a cornerstone of negative gearing. It allows investors to reduce their tax liability while holding a long-term growth asset.
How Long Do I Need to Keep Records for My Rental Property?
Good record-keeping is non-negotiable. The ATO requires you to keep records for all your income and expenses for five years from the date you lodge your tax return. This includes all receipts, bank statements, property manager reports, and loan documents.
For Capital Gains Tax (CGT) purposes, the rules are even stricter. You must keep all records related to buying and selling the property for the entire time you own it, plus an additional five years after you sell it and lodge that year’s tax return.
Can I Claim Deductions for a Vacant Rental Property?
Yes, you absolutely can. You're able to claim expenses for a rental property for any period it is genuinely available for rent, even if it’s temporarily sitting empty between tenants.
The key phrase here is 'genuinely available'. This means you must be actively advertising the property for rent at a realistic market rate. You can't just leave it empty and hope for the best. You also cannot claim deductions for any periods when the property is not on the rental market or when you're using it for your own private purposes. Our guide on how to prepare an investment property tax return offers further insights into getting this right.
Depreciation reduces an asset's cost base. When you sell, previously claimed Division 40 depreciation triggers a balancing adjustment. For Division 43 capital works deductions claimed from 1 July 2017, the amount reduces the building's cost base, increasing the eventual capital gain. The interaction between depreciation and CGT requires careful calculation at time of sale.
A quantity surveyor prepares a tax depreciation schedule by physically inspecting the property and identifying all depreciable assets and their values. The ATO accepts these estimates for depreciation claims where original receipts are unavailable. The fee is tax deductible. A schedule maximises your annual depreciation claims based on a comprehensive site assessment.
Division 43 covers the capital works deduction on structural components (walls, floors, roof) at 2.5% per year for buildings constructed after 15 September 1987. Division 40 covers plant and equipment (appliances, carpet, blinds) depreciated over their ATO-determined effective life. Post-May 2017 legislation restricts Division 40 claims on second-hand residential assets for new buyers.
Yes. The May 2017 restrictions on second-hand plant and equipment only apply to residential properties. Commercial property investors can still claim Division 40 depreciation on second-hand assets. Division 43 capital works deductions apply to both property types based on construction date, not acquisition date.
Keep the purchase contract, settlement statement, receipts for capital improvements, and a quantity surveyor's depreciation schedule. The ATO can request these records for five years after the relevant income year. Without records, depreciation claims can be reduced or disallowed on audit, and you may lose the ability to substantiate cost base adjustments at sale.
Navigating the complexities of rental property tax can feel overwhelming, but you don't have to do it alone. The expert team at Australia Wide Tax Solutions can help you confidently lodge your return and maximise every single legitimate claim. Contact us today to ensure your investment is working for you.
